Bybit Options Weekly Review: March 17-24
AI Summary
Show More
Quickly grasp the article's content and gauge market sentiment in just 30 seconds!
Week of March 17–24, 2026
I. Weekly Market Recap
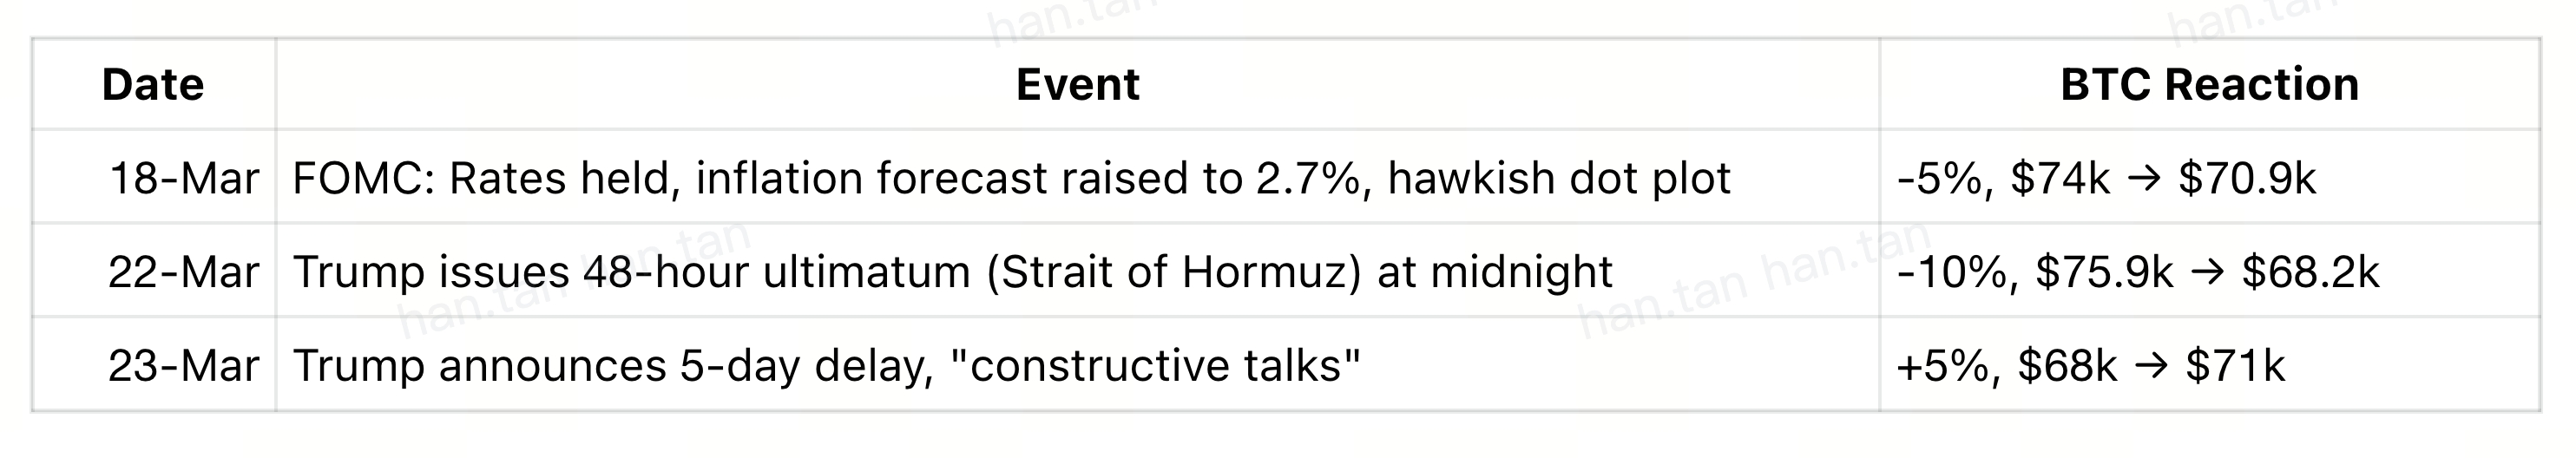
The most dramatic week of Q1, with three major events converging to create a rare market stress test:
Price Action:
BTC: Weekly high $75,912 (3/21) → plunged to $68,241 (Trump ultimatum) → rebounded today to $70,645
ETH: Mirrored BTC, weekly high ~$2,350 → dropped to $2,050 → bounced to $2,180
Net weekly change: BTC -6%, ETH -7%; Fear & Greed Index fell from 28 to 11 (Extreme Fear)
Three-Event Timeline:
II. Options Market Key Data
Weekly Expiry Settlement (3/20):
BTC: 23,000 contracts, notional $1.6B, PCR 0.88, Max Pain $70,000
ETH: 176,000 contracts, notional $370M, PCR 1.04, Max Pain $2,150
Volatility Trends:
BTC Realized Volatility (RV) pulled back from ~80 to 50; DVOL ranged between 50%–58% for the week. ETH DVOL held at 65%–72%, approximately 15pts above BTC
DVOL briefly compressed after FOMC, then spiked again on the Trump ultimatum, forming a "V-shaped" volatility curve for the week
Skew (25δ):
Early this month, the Put/Call premium ratio reached 2.0 — the highest since summer 2022. Put IV averaged ~66%, roughly 17pts above Call IV, sitting at the 89th historical percentile — signaling extremely defensive market pricing
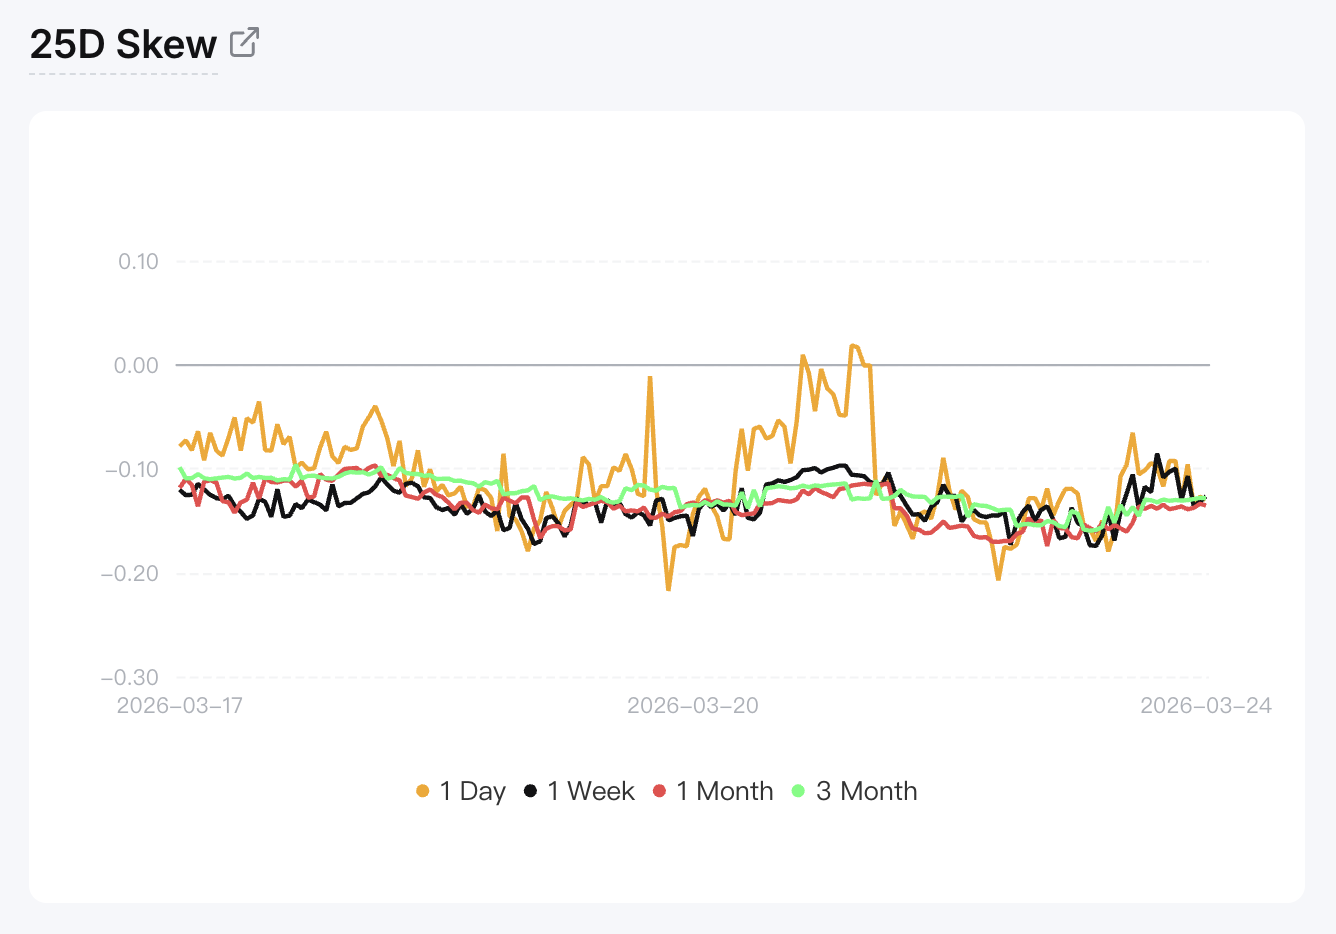
Skew recovered slightly on the "constructive talks" news, but remains negative overall with Put demand dominant
PCR Trends:
3/13 settlement: BTC PCR 0.9 (sharply down from last week's 1.70), ETH 1.21
3/20 settlement: BTC PCR 0.88, ETH 1.04 — structure trending toward neutral, but directional pressure remains externally driven
III. Macro Background
Federal Reserve (March 18th):
Rates held at 3.50%–3.75%; 2026 inflation forecast raised from 2.5% to 2.7%; dot plot maintains only one rate cut for the full year; long-run rate neutral raised from 3.0% to 3.1%
Markets are now pricing a ~35% probability of a rate hike in October — dovish expectations have completely reversed
US–Iran War (Day 23):
Closure of the Strait of Hormuz has disrupted ~20% of global oil supply; the IEA called it "the largest global energy security challenge in history"
Brent crude surged to $111 intraweek before falling back to $100; the 5-day pause window offers short-term relief, but no ceasefire yet in sight
IV. Outlook for Next Week (3/25–3/31)
The 3/27 monthly expiry (end of Q1) is the key focus:
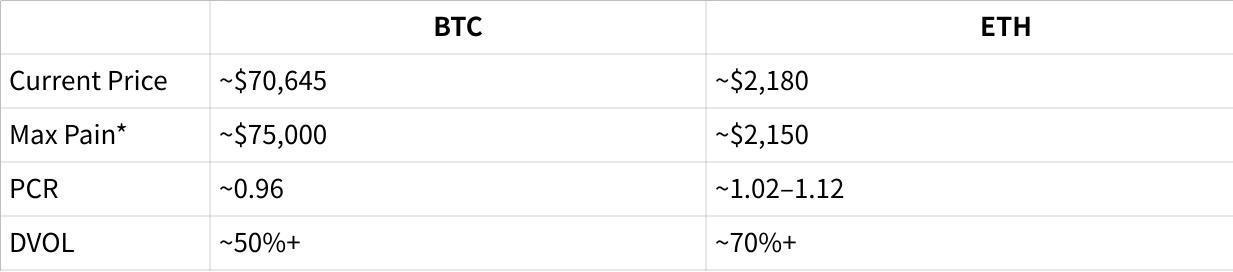
⚠️ BTC is currently ~$4,400 below the monthly max pain level — theoretically subject to upward gravitational pull, but requires a macro/geopolitical catalyst
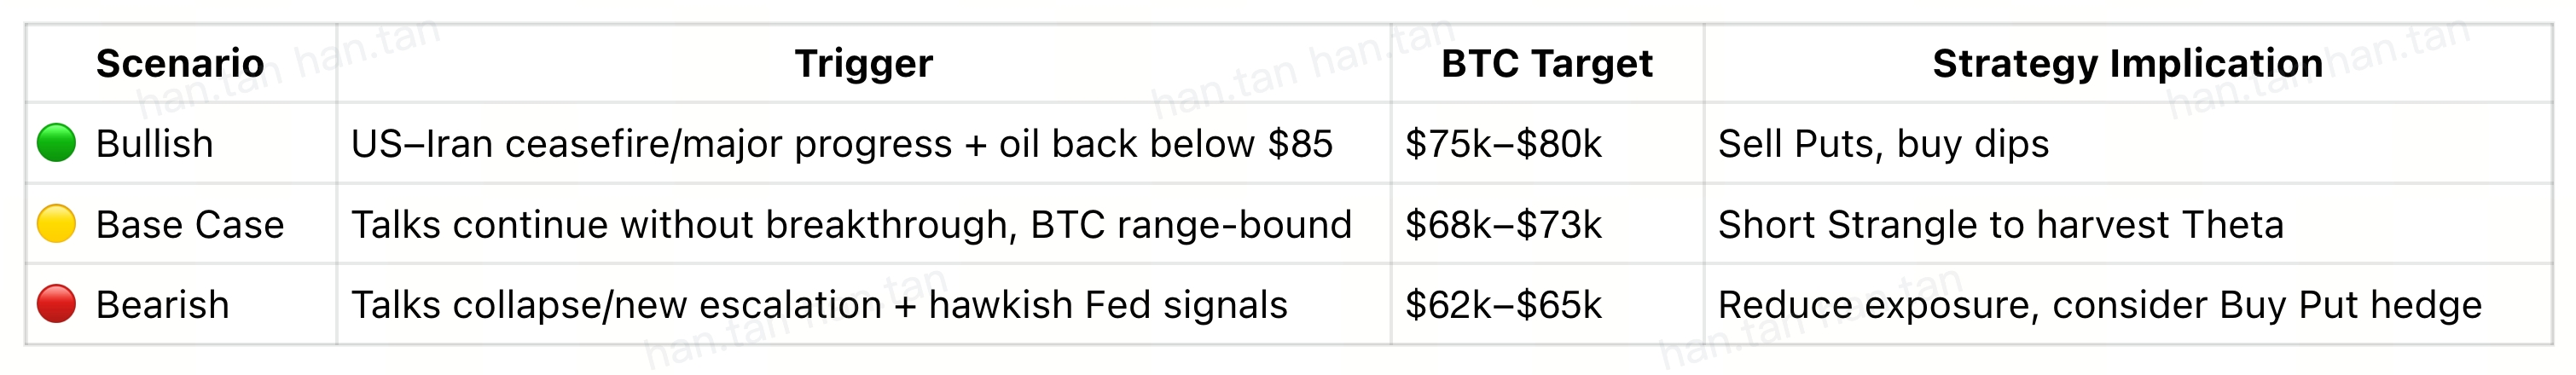
Three Scenarios:
V. Trading Recommendations
Current Recommendation: Short Volatility (3/27 expiry)
Sell BTC Put $60,000-$62,000 → annualized ~10%-14%, APY ~12%-15% below spot, below February's low of $63k — only reached in extreme panic; suitable for sellers willing to accumulate at the bottom
Sell BTC Call $76,000-$77,500 → annualized ~10%-17%, APY ~7.8%-10% above spot — requires breaking above pre-FOMC highs with a major geopolitical de-escalation; currently a low-probability outcome
Risk Warnings:
US–Iran talks collapse = immediate downside breach of the $62k strike
Surprise ceasefire/deal = rapid upside breach of the $76k strike
The option market is pricing combined likelihood of these two extreme scenarios is currently below 10%. This translates to a 90% probability of earning the stated APY. However, we strongly recommend to size positions conservatively and maintain sufficient margin to weather tail events
🏆 Weekly Summary:
Last week's market was entirely dominated by the dual shock of hawkish FOMC signals and geopolitical escalation, with BTC's correlation to risk assets fully re-asserting itself.
BTC's correlation to the S&P 500 reached 89% during the 3/19 selloff — fully entering macro-driven mode.
In the near term, US–Iran negotiation progress is the single biggest variable: a ceasefire is a bull catalyst; a breakdown means a fresh test of lows.
Options sellers retain an edge in the elevated DVOL environment, but position sizing and tail-risk hedging remain non-negotiable.