alhamee
4135Me gusta0Compartir en el chat41Aficionados3Seguir
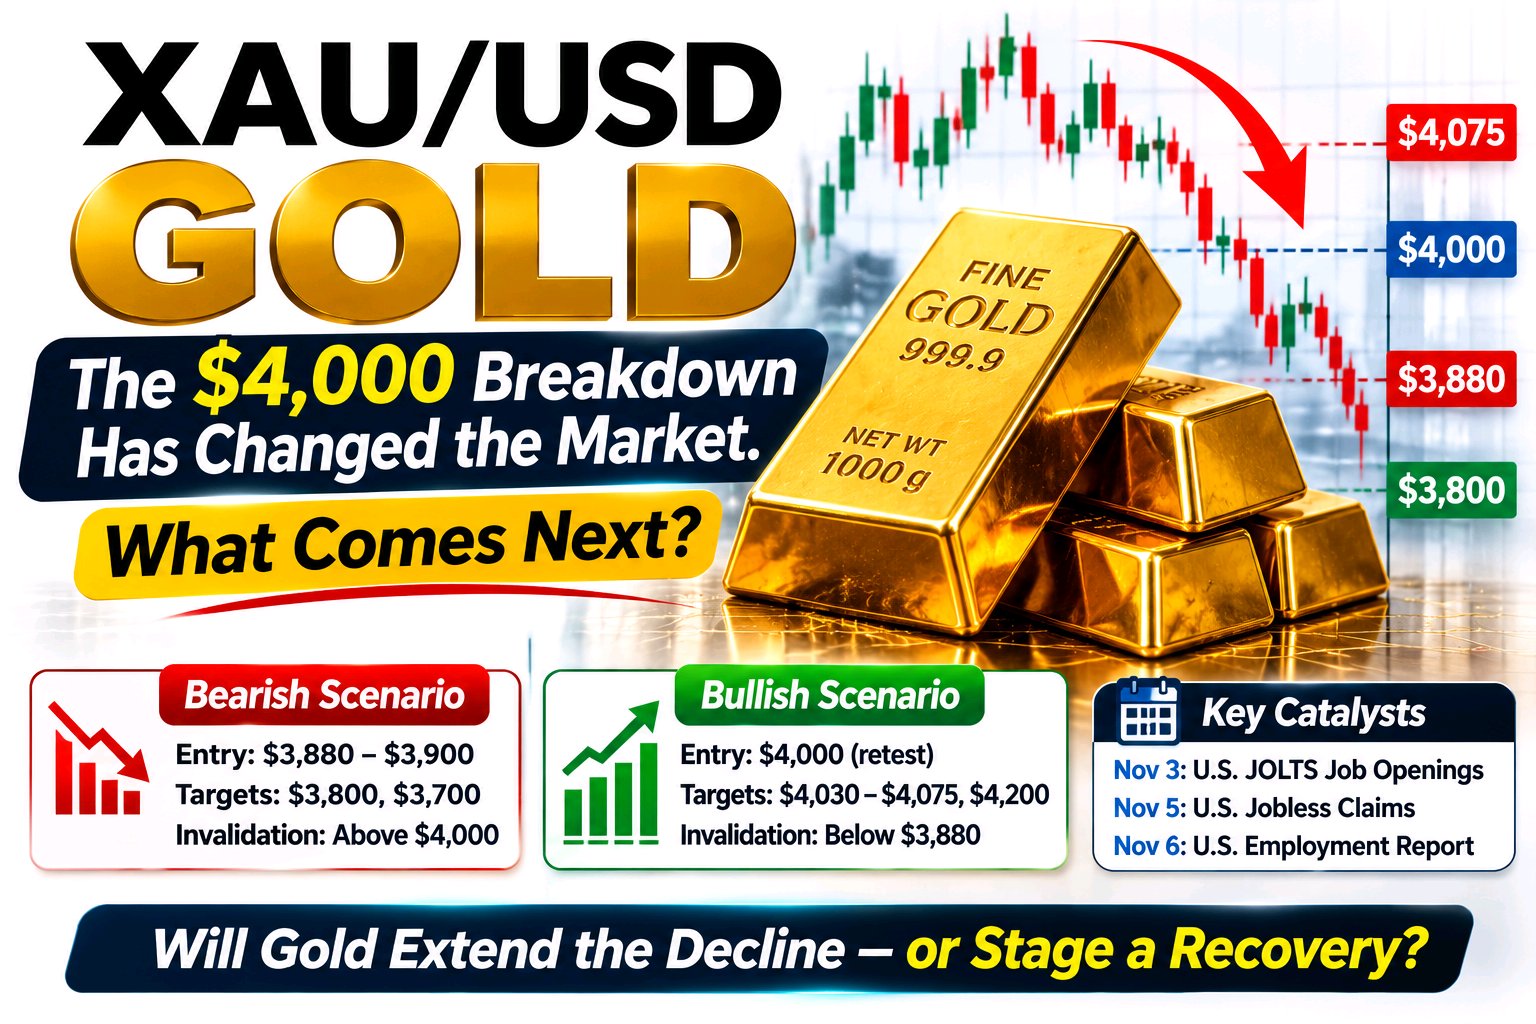
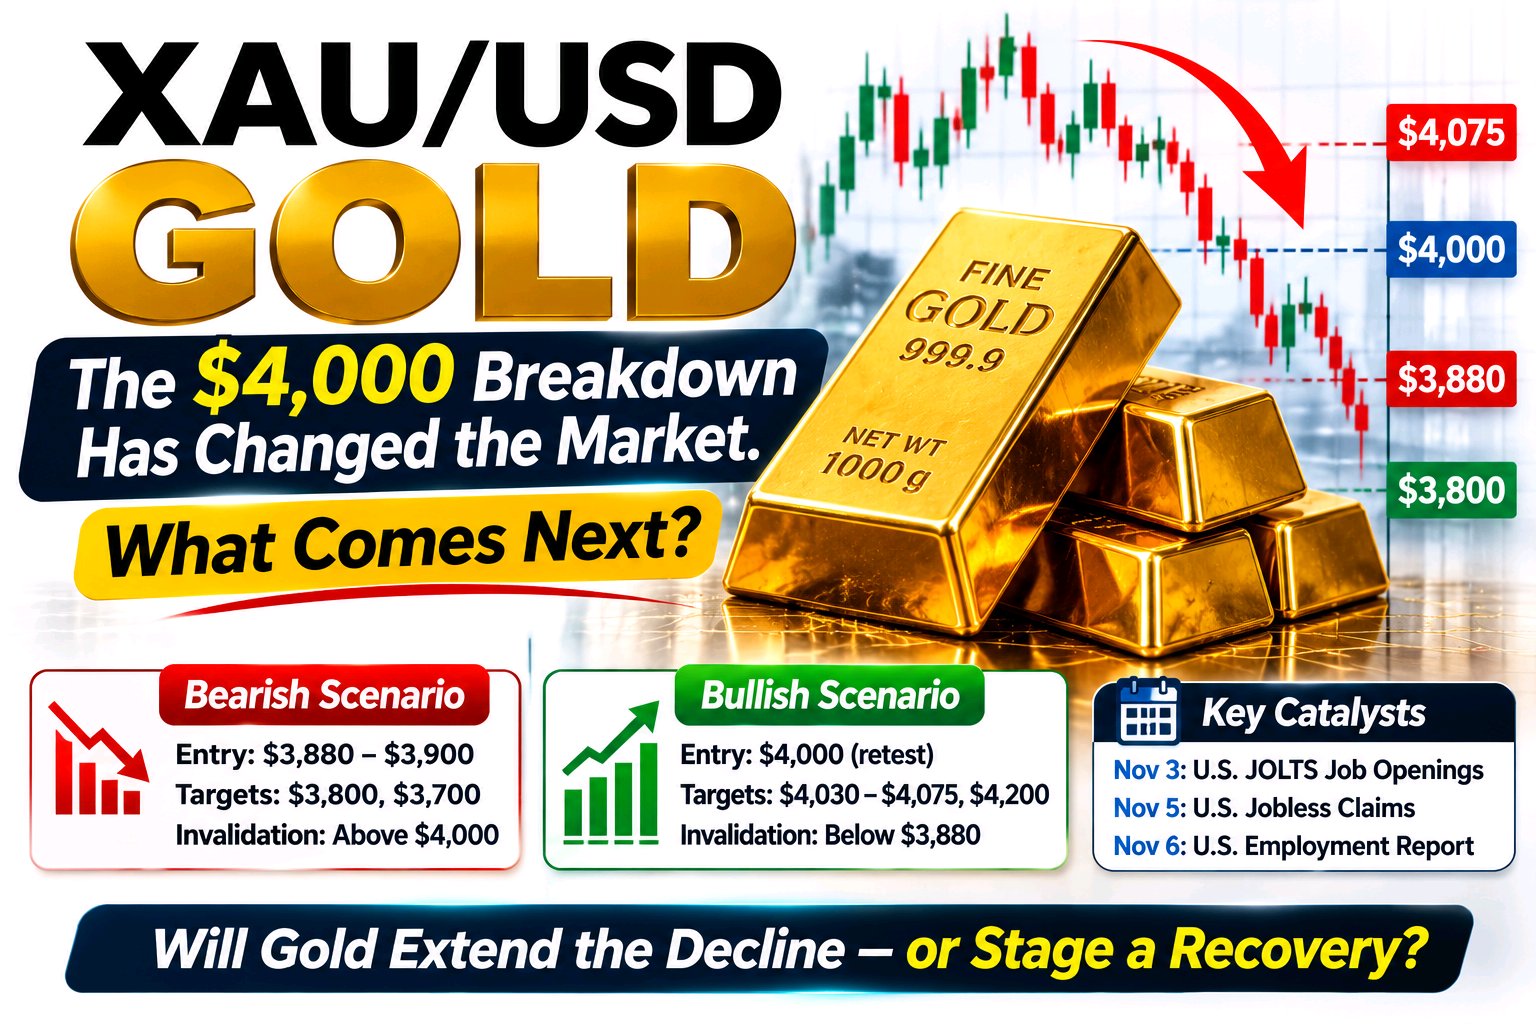
El oro se mantiene en los $4,400, pero el IPC podría provocar el siguiente gran movimiento $XAUT/USDT cotiza alrededor de los $4,400 después de caer por debajo de ese nivel el lunes. El oro al contado alcanzó brevemente los $4,396 aproximadamente, extendiendo la presión tras el informe de empleo de EE. UU. del viernes, que resultó ser más fuerte de lo esperado. Las nóminas de agosto aumentaron en 162,000 frente a las 56,000 esperadas, mientras que el desempleo se mantuvo en el 4.1%, lo que llevó a los mercados a valorar en cerca de un 60% la probabilidad de una subida de tipos de la Fed en septiembre. Lo menos evidente es cuánta presión macro está absorbiendo el oro sin colapsar por completo. El rendimiento más alto de los bonos del Tesoro, el aumento de los precios del petróleo y las renovadas expectativas de subidas de tipos de la Fed están actuando en contra del metal. Sin embargo, el riesgo geopolítico está apoyando simultáneamente la demanda de refugio seguro, mientras que el dólar ha tenido dificultades para ampliar sus ganancias. Eso deja al oro atrapado entre dos fuerzas opuestas. También hay un desarrollo interesante específicamente para $XAUT. Tether está cerrando Alloy y aUSDT mientras redirige explícitamente sus recursos hacia productos con mayor demanda, mayor liquidez y mejores oportunidades a largo plazo, incluido XAU₮. Los usuarios actuales de aUSDT tienen hasta el 17 de septiembre para devolver sus aUSDT y recuperar su garantía en XAU₮ a través de la plataforma. Técnicamente, los $4,400 son ahora el campo de batalla. Bajista: rechazo alrededor de los $4,450–$4,500 → pérdida de los $4,400 → objetivo en los $4,350, luego $4,300. Alcista: recuperar los $4,500 y romper los $4,540 → abre el camino a los $4,600, luego $4,700. Invalidación: una aceptación sostenida por debajo de los $4,300 debilitaría significativamente la estructura de recuperación actual. El próximo gran catalizador es la inflación de EE. UU. El IPP llega el jueves y el IPC el viernes. Un dato de inflación más caliente podría reforzar la narrativa de subida de tipos de la Fed, mantener los rendimientos elevados y poner a los $4,400 bajo una presión seria. Un IPC más suave podría revertir parte de ese reajuste agresivo y darle al oro espacio para atacar los $4,500 nuevamente. Pero aquí está la distinción importante: El oro no necesita subir todavía. Necesita demostrar que los $4,400 son una base real. No quiero perseguir el rebote. Quiero ver que los $4,500 pasen de ser resistencia a soporte. Hasta entonces, esta sigue siendo una zona de decisión, no una reversión confirmada. ¿El oro recuperará los $4,500 antes del IPC, o finalmente cederán los $4,400? $XAUTUSDT #ByXIMPACT
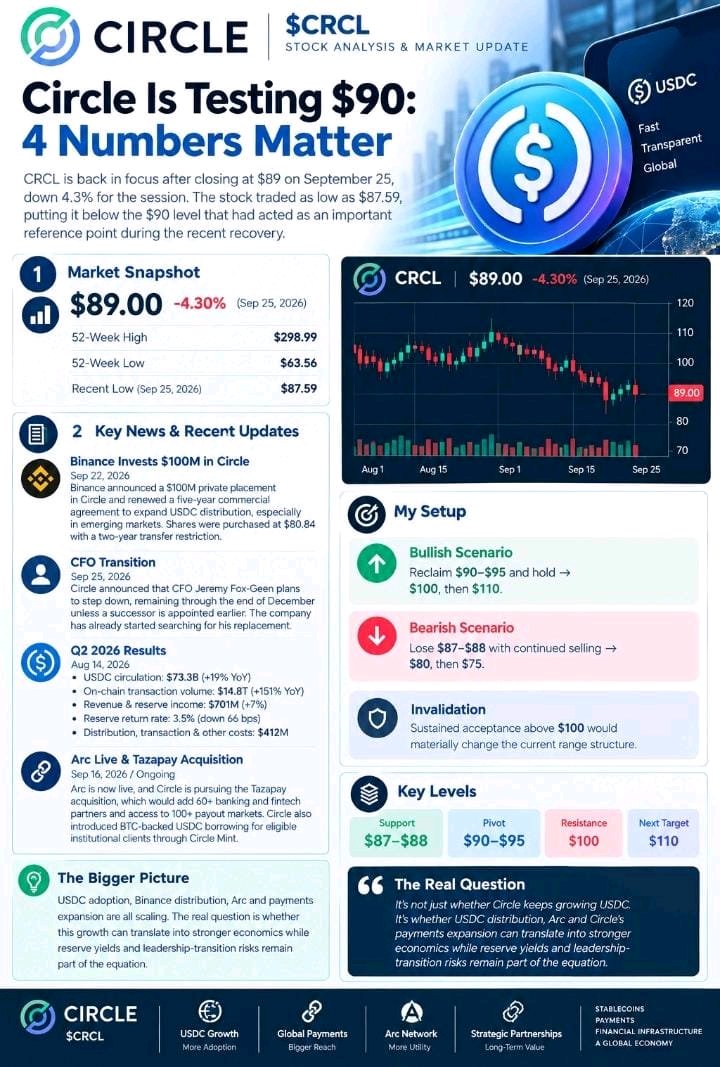
CRCL y TSLA: Dos historias de crecimiento, dos pruebas
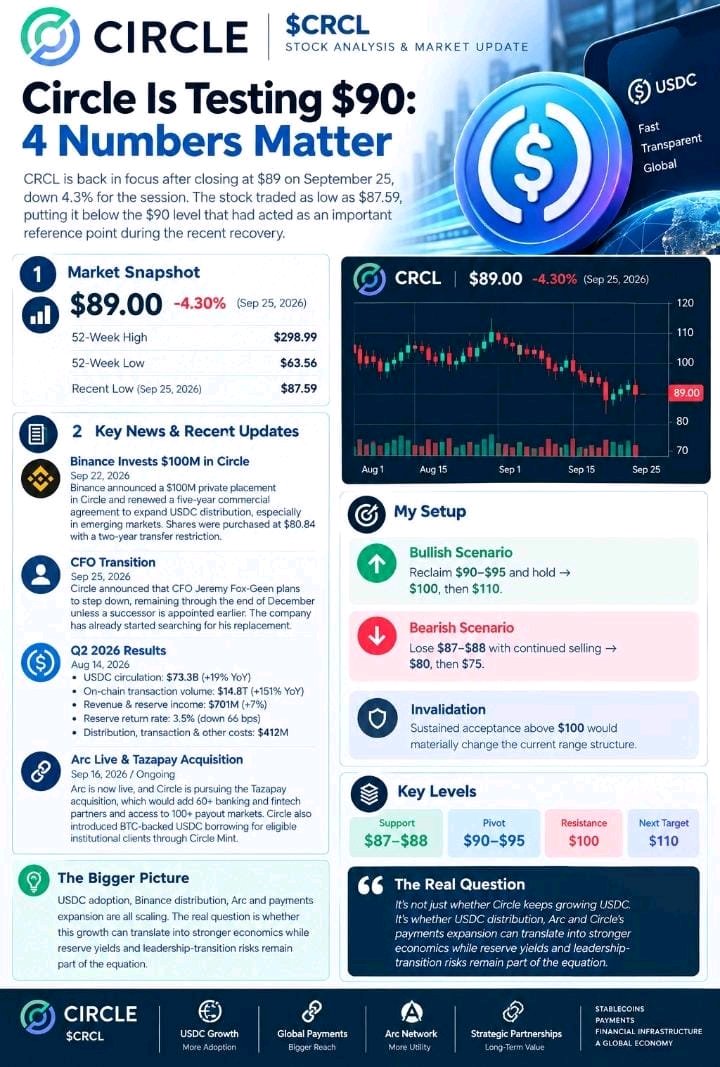
Circle y Tesla están contando historias de crecimiento muy diferentes, pero ambas se están acercando a niveles donde la ejecución importa más que la narrativa. CRCL cerró en $89 el 25 de septiembre, con una baja del 4.3% en la sesión. La presión inmediata surge después de un fuerte repunte en septiembre, pero el panorama fundamental sigue activo: Binance invirtió $100 millones en Circle a $80.84 por acción y renovó una asociación de cinco años con USDC. Circle también lanzó la red principal Arc con más de 100 constructores institucionales y del ecosistema, mientras que la circulación de USDC superó los $74 mil millones. El nuevo riesgo es la transición de la gestión. Circle anunció que el CFO Jeremy Fox-Green dejará su cargo, con una transición planeada hasta diciembre, a menos que llegue un sucesor antes. Esto sucede mientras el negocio se está expandiendo: la circulación de USDC en el segundo trimestre alcanzó los $73.3 mil millones (+19% interanual), el volumen en cadena llegó a $14.8 billones (+151%) y los ingresos más los ingresos por reservas alcanzaron los $701 millones. TSLA cerró en $372.11 el 25 de septiembre, con una baja del 1.54%. Tesla ahora tiene varios catalizadores convergiendo: las entregas del Semi han comenzado desde sus instalaciones en Nevada, las cuales están planificadas para 50,000 camiones anualmente, mientras que la compañía recibió recientemente un pedido de 2,500 Semis de un grupo que incluye a Microsoft y PepsiCo. Los reguladores checos también aprobaron provisionalmente el sistema FSD de Tesla esta semana. Pero la historia de autonomía de Tesla todavía enfrenta una prueba regulatoria. La NHTSA está investigando la certificación de hasta 1,000 Cybercabs, y se le ha ordenado a Tesla responder preguntas sobre la certificación antes del 30 de septiembre. Eso crea dos configuraciones muy diferentes. Configuración de CRCL Alcista: recuperar $90–$95 → $100, luego $110. Bajista: perder $87–$88 → $80, luego $75. Configuración de TSLA Alcista: recuperar $380–$385 → $400, luego $420. Bajista: rechazo por debajo de $380 y pérdida de $365 → $350, luego $335. La parte interesante no es simplemente si CRCL puede hacer crecer USDC o si Tesla puede hacer crecer la autonomía. Es si Circle puede convertir la adopción de stablecoins en una economía duradera, mientras que Tesla demuestra que sus ambiciones de autonomía y nuevos productos pueden escalar sin que la ejecución y los problemas regulatorios se conviertan en el cuello de botella.. $TSLAXUSDT $CRCLXUSDT #ByXIMPACT
AAPL: The Event Delivered, But Price Still Needs To Confirm Apple gave investors plenty to digest yesterday: the $1,999 iPhone Duo, iPhone 18 Pro and Pro Max, upgraded AirPods, Apple Watch Series 12 and Ultra 4, plus a deeper AI push through its latest software experience. The foldable iPhone is clearly the headline, but for investors, the bigger question is whether this product cycle can translate into a meaningful upgrade cycle. What caught my attention is the reaction in AAPL itself. Despite the scale of the announcements, Apple finished around $315.34, down roughly 0.28%, with price still trading inside its broader ascending channel rather than breaking higher. 📈 The chart remains constructive, but AAPL is now approaching a key decision area. Higher lows are still developing inside the rising channel, while price continues to test the upper boundary. That makes the technical breakout more important than the event headline itself. If AAPL can push through the channel resistance and hold above it with volume, the structure would favor another upside leg. But there is another possibility. The market may be telling us that the iPhone Duo, higher Pro pricing and AI improvements were already partially priced in. Major Apple launches can also produce short-term sell-the-news reactions before the market reassesses the longer-term earnings impact. So I'm watching price confirmation rather than chasing the narrative. Bull case: breakout above channel resistance → volume confirmation → continuation toward the next resistance. Bear case: rejection at the upper boundary → loss of the rising channel → deeper pullback before another breakout attempt. The event delivered the narrative. Now AAPL needs to deliver the price confirmation. Would you buy the dip inside the channel, or wait for AAPL to break and hold above resistance first? $AAPLXUSDT #ByXIMPACT
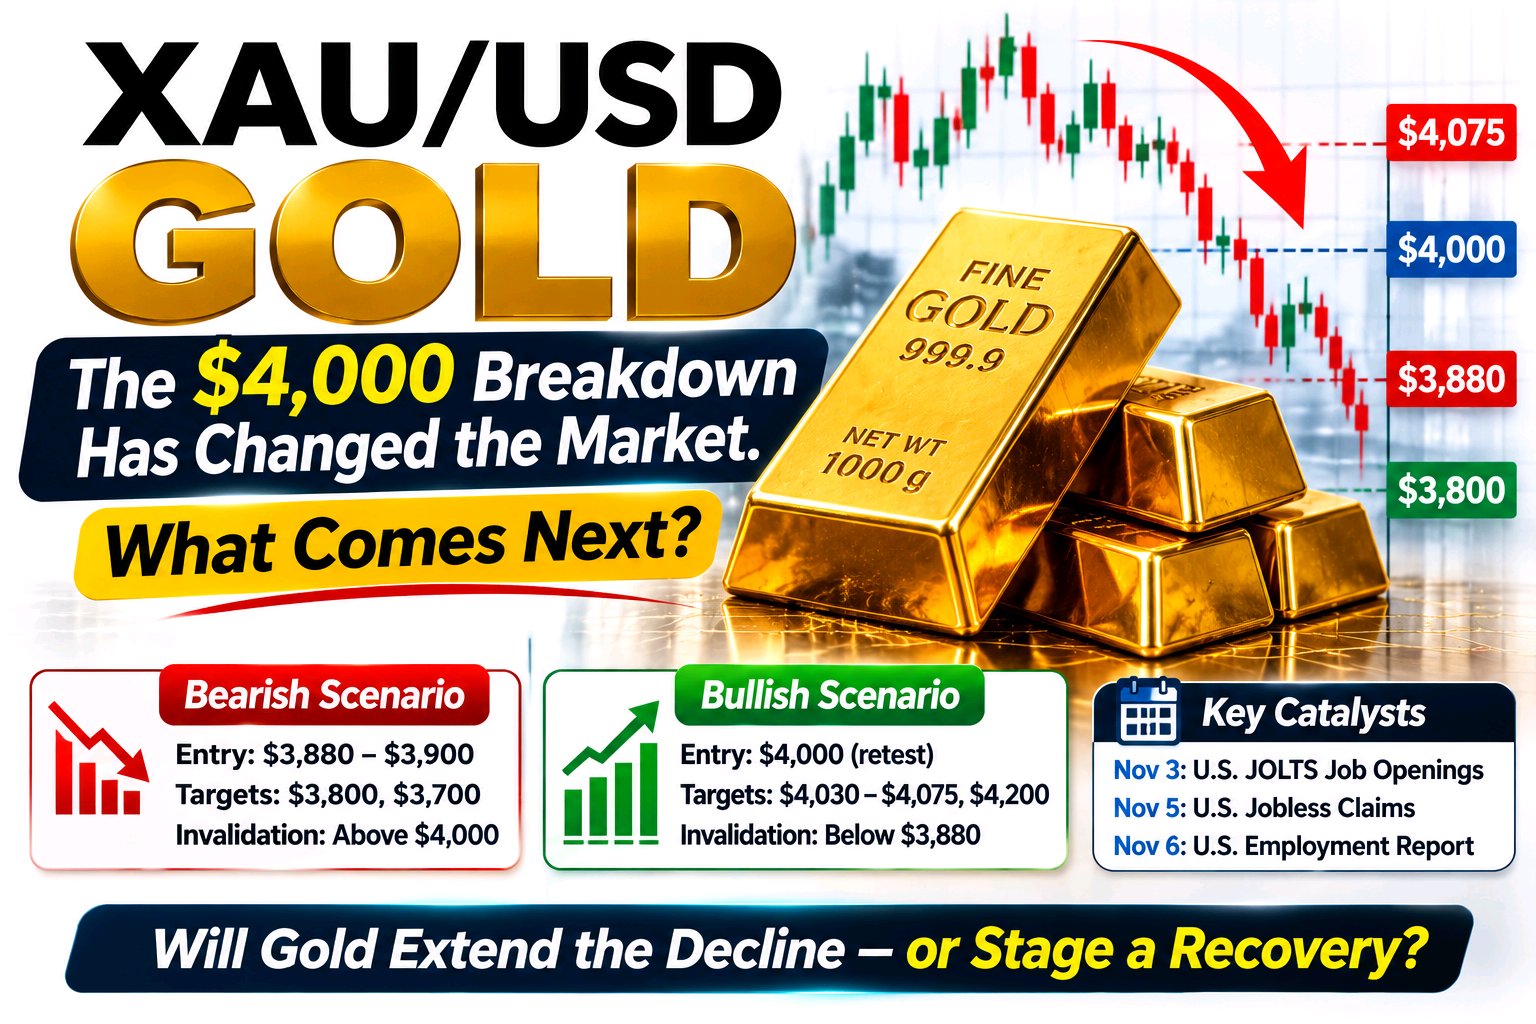
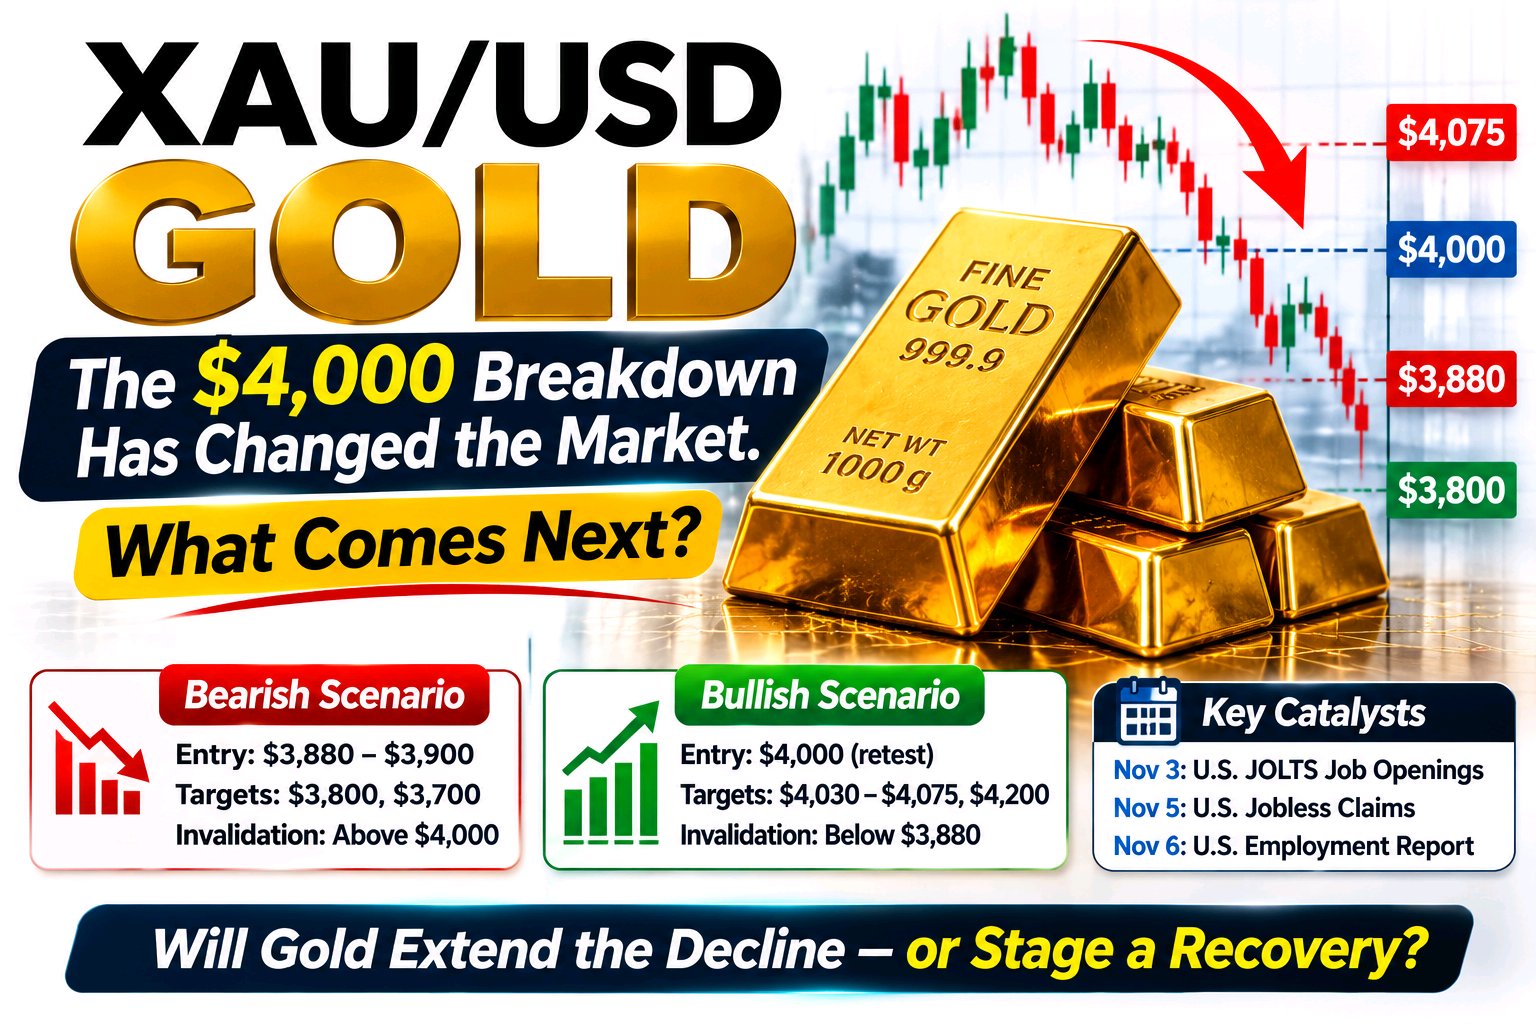
The Gold is breaking below $4,300 and this selloff is becoming more than a normal pullback. XAU/USD fell to around $4,303 on Wednesday, its lowest level in more than three weeks, with gold now facing a fourth straight session of losses. The move comes as renewed U.S.-Iran tensions push oil higher, while the U.S. 10-year yield climbs toward 4.81% and markets price roughly a 70% chance of a Fed hike this month. The less-obvious part is the reaction to geopolitical risk. Normally, escalating conflict should strengthen gold's safe-haven bid. But this time, higher oil prices are creating another problem: inflation expectations are rising alongside yields, making the Fed more likely to stay restrictive. That is allowing the dollar and Treasury yields to overpower gold's traditional safe-haven demand. Technically, $4,300 is now the battleground. Gold is trading below its 200-day moving average, so buyers need to reclaim lost levels before the structure starts looking constructive again. Bearish: rejection around $4,350–$4,400 → targets $4,250, then $4,200. Bullish: reclaim $4,400 and hold → opens a recovery toward $4,480–$4,520. Invalidation: sustained acceptance above $4,520 would weaken the current bearish structure. The next major catalyst is U.S. labor data. A weak ADP/NFP sequence could reduce Fed-hike expectations and give gold the liquidity relief it needs. A strong labor report would reinforce the higher-yields narrative and potentially put $4,300 under much greater pressure. Gold isn't losing because safe-haven demand disappeared. It's losing because the market is currently treating inflation and higher rates as the bigger risk.. $XAUTUSDT #ByXIMPACT
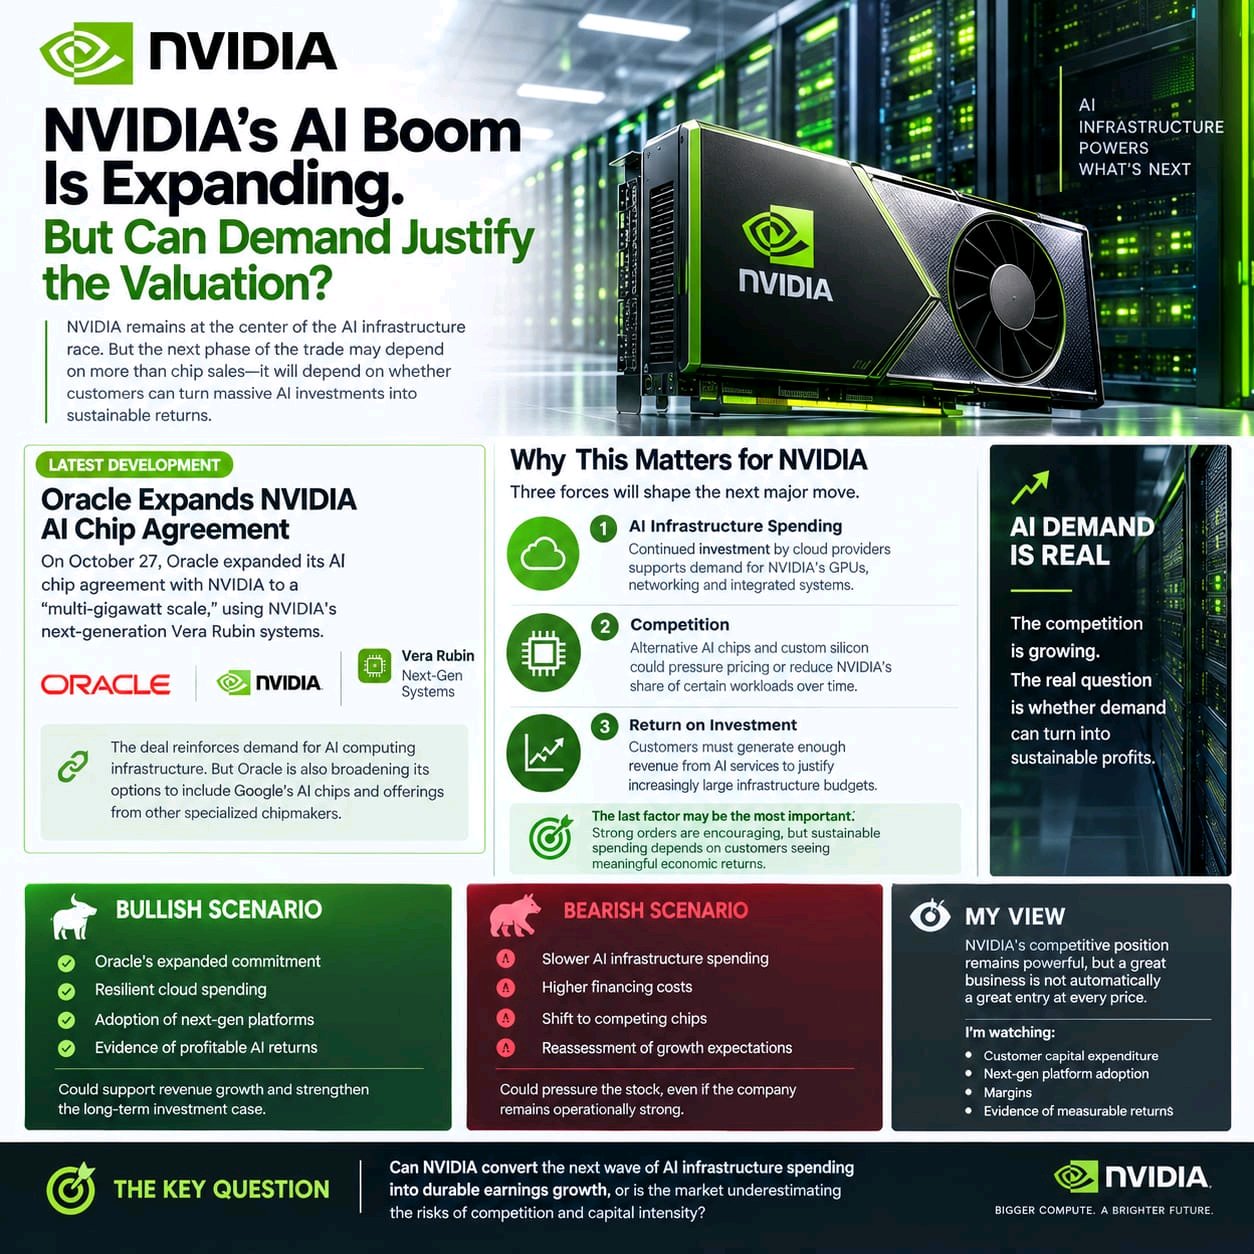
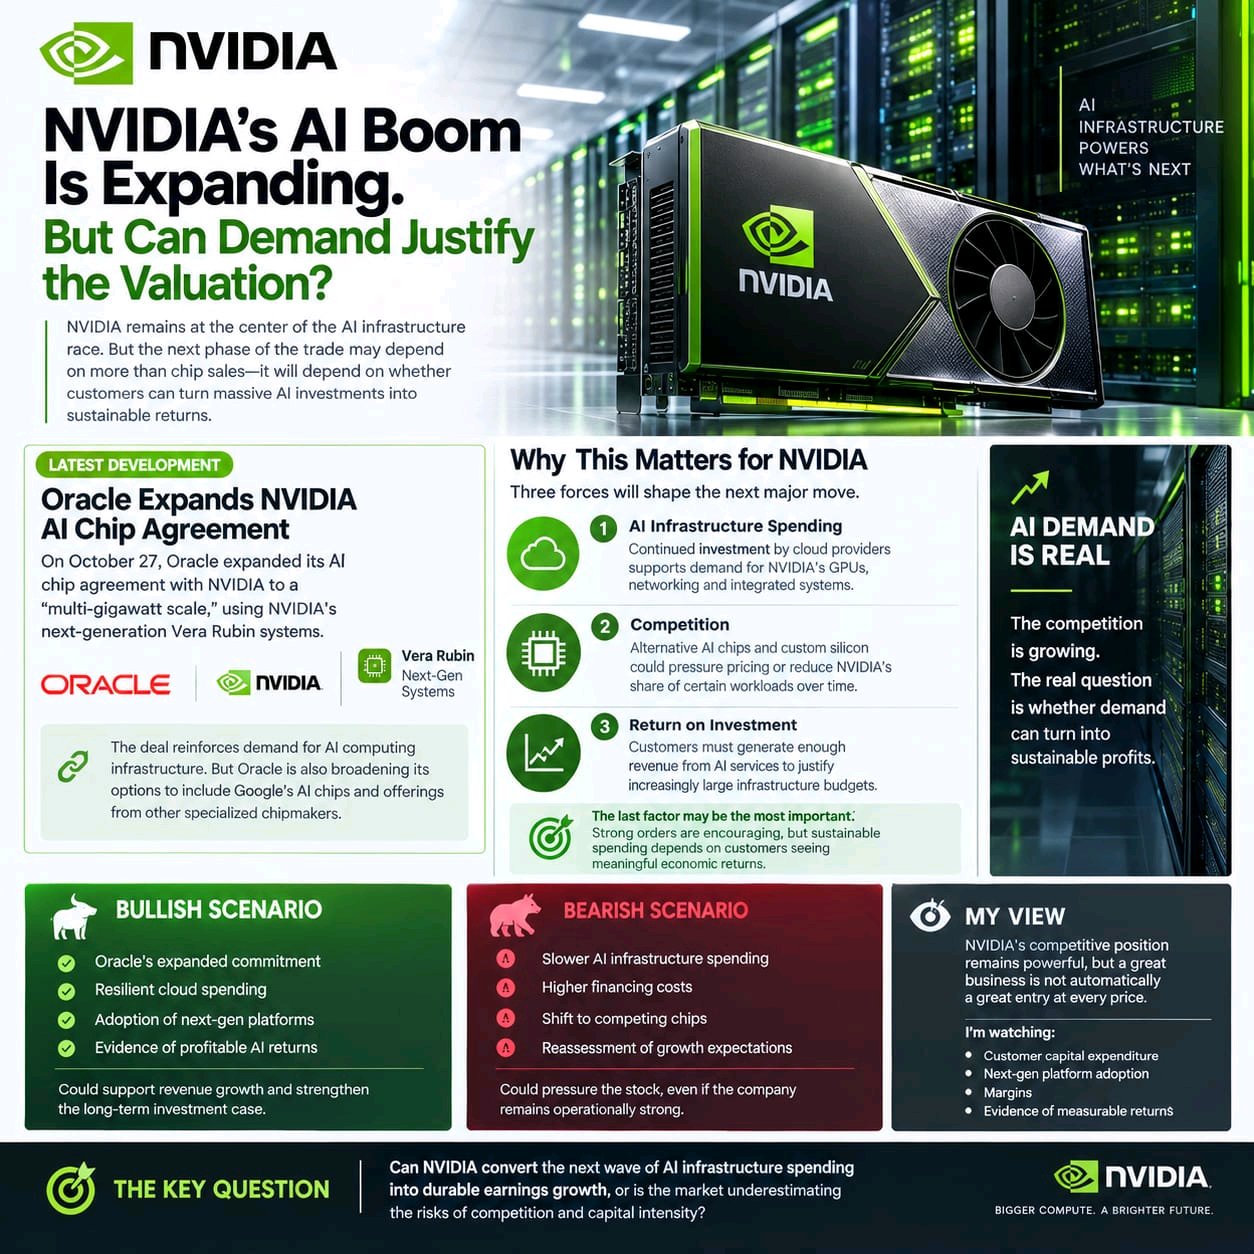
Nvidia is still growing at a rate most mega-cap companies can’t touch but the stock is starting to face a different test. Nvidia just reported $96.2B in quarterly revenue, up 106% YoY and 18% sequentially. Data Center revenue reached $89B, up 117% YoY. Even more important, management guided Q3 revenue to $108B ±2%. The less-obvious signal is the gap between fundamental growth and market expectations. Nvidia's Vera Rubin platform is already ramping into full production across major AI infrastructure partners, meaning the company isn't relying only on Blackwell to sustain the cycle. But macro has suddenly become a bigger problem. The U.S. 10-year yield has pushed toward 4.8%, while September Fed hike expectations have risen toward 67–68% as oil and inflation concerns intensify. That creates pressure on high-valuation technology stocks even when their underlying businesses remain strong. So the setup is becoming more interesting. Bullish: hold the $215–$220 area and reclaim $225–$230 → momentum can target $240, then $250. Bearish: lose $215 → watch $205, with $195 becoming the deeper support zone. Invalidation: sustained acceptance above $230 would weaken the short-term bearish thesis. The AI story hasn't broken. The question is whether NVDA can continue climbing while yields are telling investors to demand a higher return for owning growth. That's the divergence I'm watching now: record AI demand versus increasingly hostile macro conditions. $NVDAXUSDT #ByXIMPACT
Tesla and SpaceX are entering an important stretch where execution matters more than the Musk narrative. Tesla delivered 480,126 vehicles in Q2 and deployed 13.5 GWh of energy storage, but its China-made EV sales growth slowed sharply to 3.6% YoY in August. Meanwhile, Cybercab has moved into commercial deployment in Austin, but NHTSA has asked Tesla to answer questions by September 30 about its self-certification. SpaceX is facing a different test. Q2 revenue surged 91.9% YoY to $7.8B, with AI revenue jumping 247.5% to $2.6B and Starlink connectivity revenue reaching $4.3B. But the growth requires enormous investment: AI capex alone reached $15.8B in Q2. SpaceX is now targeting September 28 for Starship Flight 14, its first revenue-generating Starship mission, carrying 26 Starlink V3 satellites. The market is also giving investors a clear technical test. TSLA is around the $390 area, while SPCX closed at $148.36 on September 23 after falling 4.11%; the latest session has pushed it back toward the $146–$150 zone. SpaceX's upcoming lockup expiration is another near-term supply consideration, with roughly 328 million shares becoming eligible to trade. My setup: • $TSLA Bullish: reclaim $400 → $420, then $450. • $TSLA Bearish: lose $370 → $355, then $340. • $SPCX Bullish: reclaim $155–$160 → $175, then $190. • $SPCX Bearish: lose $145 → $135, then $125. The interesting question isn't which company has the bigger Musk-led narrative. It's whether Tesla can turn autonomy into a scalable business while SpaceX converts Starlink and AI growth into enough cash flow to support its massive capital spending without the market demanding a reset in valuation first.. $TSLAXUSDT $SPCXXUSDT #ByXIMPACT
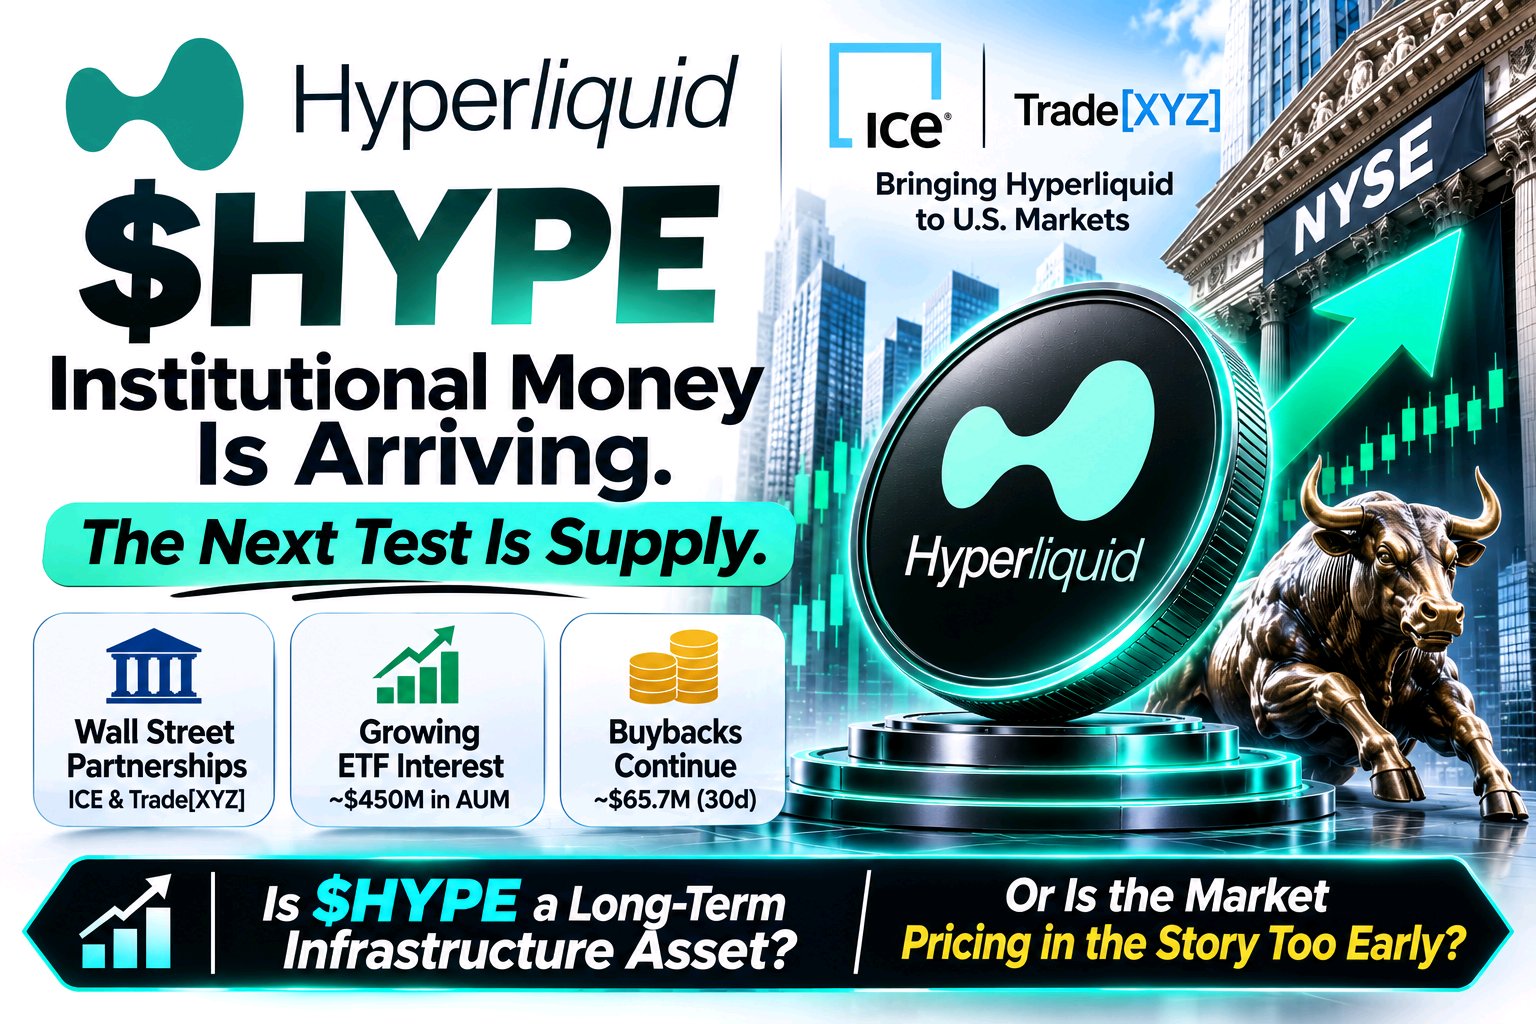
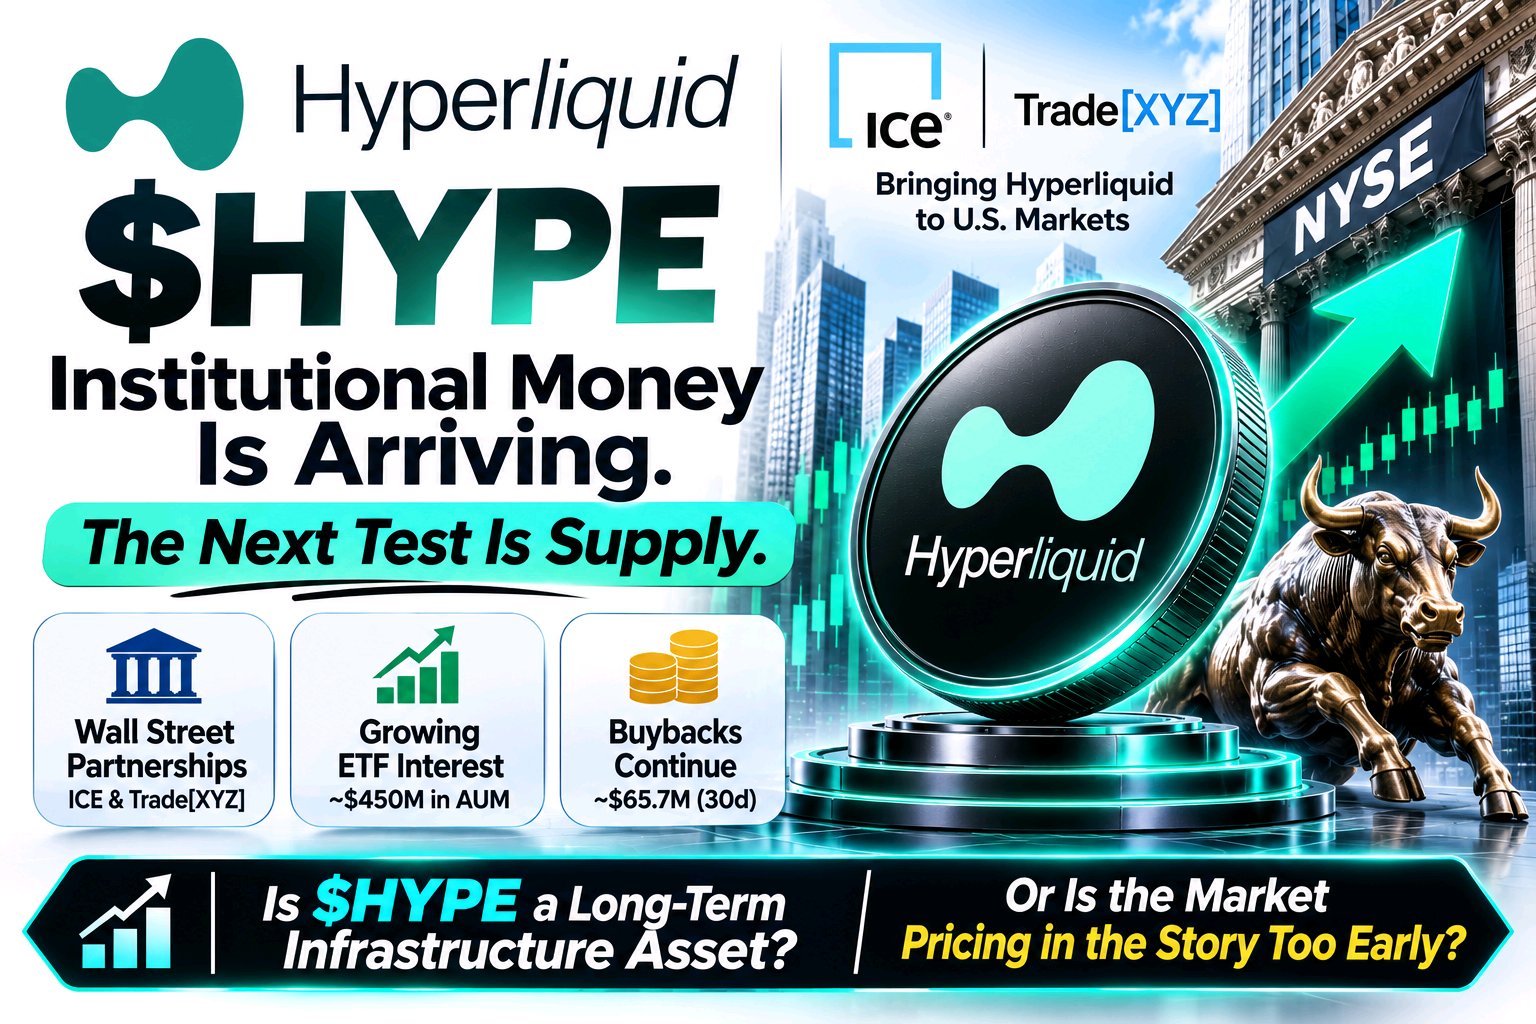
$HYPE: El dinero institucional está llegando. La próxima prueba es la oferta. Hyperliquid está entrando en una fase distinta. La pregunta ya no es solo si los traders quieren un exchange de derivados on-chain. Es si las instituciones financieras tradicionales pueden ayudar a convertir a Hyperliquid en infraestructura para un mercado mucho más amplio, y si los holders de HYPE se verán beneficiados. Tres acontecimientos destacan. 1. Wall Street está explorando la infraestructura de Hyperliquid. El 29 de octubre, ICE anunció una asociación con Trade[XYZ] para desarrollar mercados perpetuos regulados en EE. UU. utilizando la tecnología de Hyperliquid. Los productos planeados podrían cubrir cripto, acciones, materias primas y divisas. Un hecho separado el 26 de octubre vio a Hyperliquid identificar a Payward, la empresa matriz de Kraken, como su primer implementador de HIP-3 regulado por la CFTC, sujeto a aprobaciones. Estos movimientos sugieren que el mercado potencial de Hyperliquid se extiende más allá de los traders nativos de cripto. Pero ninguno de los anuncios garantiza la acumulación directa de valor para los holders de HYPE. 2. Los productos de inversión regulados están creando otro canal de demanda. Los productos de inversión de HYPE al contado ofrecen a los inversores tradicionales exposición sin requerir que gestionen tokens directamente. Para el 30 de octubre, tres productos retenían colectivamente aproximadamente $450 millones de dólares en activos, según datos de seguimiento de flujos de ETF. Esa es una señal alentadora del interés de los inversores, pero los activos bajo gestión no son lo mismo que los flujos diarios frescos, y los flujos pueden revertirse. 3. La presión de la oferta sigue siendo parte de la ecuación. El próximo desbloqueo importante programado para los contribuyentes principales es el 6 de noviembre, con aproximadamente 9.92 millones de HYPE listados para liberación por los rastreadores de mercado actuales. Desbloquear tokens no significa automáticamente que se venderán, pero crea otro evento de oferta que el mercado debe absorber. Mientras tanto, el Fondo de Asistencia de Hyperliquid continúa comprando HYPE utilizando ingresos relacionados con el protocolo. Un rastreador estimó aproximadamente $65.7 millones en recompras durante los 30 días anteriores al 31 de octubre. La pregunta importante es si la demanda sostenida puede superar a la nueva oferta que entra en circulación. Mi opinión: Hyperliquid está construyendo un caso creíble como infraestructura de mercado financiero. Las asociaciones institucionales, los productos de inversión regulados y las recompras impulsadas por el protocolo son desarrollos significativos, pero la señal a largo plazo más fuerte sería un uso real creciente junto con una demanda duradera de HYPE. Estoy observando tres cosas: el progreso regulatorio, las entradas reales a los ETF y cómo maneja el mercado el desbloqueo de noviembre. ¿Se está convirtiendo $HYPE en un activo de infraestructura a largo plazo, o el mercado está descontando la historia institucional demasiado pronto? #ByXIMPACT $HYPEUSDT
El oro se mantiene en los $4,400 pero el IPC podría desencadenar el próximo gran movimiento $XAUT/USDT cotiza alrededor de los $4,400 después de caer por debajo de este nivel el lunes. El oro al contado alcanzó brevemente los $4,396 aproximadamente, extendiendo la presión tras el informe de empleo de EE. UU. del viernes, que fue más fuerte de lo esperado. Las nóminas de agosto aumentaron 162,000 frente a las 56,000 esperadas, mientras que el desempleo se mantuvo en el 4.1%, lo que llevó a los mercados a valorar en un 60% la posibilidad de una subida de tipos de la Fed en septiembre. Lo menos evidente es cuánta presión macro está absorbiendo el oro sin venirse abajo por completo. El aumento de los rendimientos de los bonos del Tesoro, la subida de los precios del petróleo y las renovadas expectativas de subidas de tipos de la Fed están actuando en contra del metal. Pero, al mismo tiempo, el riesgo geopolítico está respaldando la demanda de refugio seguro, mientras que al dólar le ha costado extender sus ganancias. Eso deja al oro atrapado entre dos fuerzas opuestas. También hay un desarrollo interesante específicamente para $XAUT. Tether está cerrando Alloy y aUSDT mientras redirige explícitamente recursos hacia productos con mayor demanda, liquidez más profunda y mejores oportunidades a largo plazo, incluido XAU₮. Los usuarios actuales de aUSDT tienen hasta el 17 de septiembre para devolver sus aUSDT y recuperar su colateral en XAU₮ a través de la plataforma. Técnicamente, los $4,400 son ahora el campo de batalla. Bajista: rechazo alrededor de los $4,450–$4,500 → perder los $4,400 → objetivos en $4,350, luego $4,300. Alcista: recuperar los $4,500 y romper los $4,540 → abre camino a $4,600, luego $4,700. Invalidación: una aceptación sostenida por debajo de los $4,300 debilitaría significativamente la estructura de recuperación actual. El próximo gran catalizador es la inflación en EE. UU. El IPP llega el jueves y el IPC el viernes. Una cifra de inflación más alta podría reforzar la narrativa de subida de tipos de la Fed, mantener los rendimientos elevados y poner a los $4,400 bajo una seria presión. Un IPC más suave podría revertir parte de esa repricing agresiva y darle al oro espacio para atacar nuevamente los $4,500. Pero aquí está la distinción importante: El oro no necesita repuntar todavía. Necesita demostrar que los $4,400 son una base real. No quiero perseguir el rebote. Quiero ver que los $4,500 pasen de resistencia a soporte. Hasta entonces, esta sigue siendo una zona de decisión, no una reversión confirmada. ¿El oro recuperará los $4,500 antes del IPC, o finalmente cederán los $4,400? $XAUTUSDT #ByXIMPACT
CRCL & TSLA: Two Growth Stories, Two Tests
Circle and Tesla are telling very different growth stories, but both are approaching levels where execution matters more than the narrative. CRCL closed at $89 on September 25, down 4.3% for the session. The immediate pressure comes after a strong September rebound, but the fundamental backdrop remains active: Binance invested $100M in Circle at $80.84 per share and renewed a five-year USDC partnership. Circle also launched Arc mainnet with more than 100 institutional and ecosystem builders, while USDC circulation had surpassed $74B. The new risk is management transition. Circle announced CFO Jeremy Fox-Green will step down, with a transition planned through December unless a successor arrives sooner. That comes while the business is scaling: Q2 USDC circulation reached $73.3B (+19% YoY), on-chain volume hit $14.8T (+151%), and revenue plus reserve income reached $701M. TSLA closed at $372.11 on September 25, down 1.54%. Tesla now has several catalysts converging: Semi deliveries have begun from its Nevada facility, which is planned for 50,000 trucks annually, while the company recently received an order for 2,500 Semis from a group including Microsoft and PepsiCo. Czech regulators also provisionally approved Tesla's FSD system this week. But Tesla's autonomy story still faces a regulatory test. NHTSA is investigating the certification of up to 1,000 Cybercabs, and Tesla has been ordered to answer questions about the certification by September 30. That creates two very different setups. CRCL setup Bullish: reclaim $90–$95 → $100, then $110. Bearish: lose $87–$88 → $80, then $75. TSLA setup Bullish: reclaim $380–$385 → $400, then $420. Bearish: rejection below $380 and loss of $365 → $350, then $335. The interesting part isn't simply whether CRCL can grow USDC or Tesla can grow autonomy. It's whether Circle can convert stablecoin adoption into durable economics, while Tesla proves that its autonomy and new-product ambitions can scale without execution and regulatory issues becoming the bottleneck.. $TSLAXUSDT $CRCLXUSDT #ByXIMPACT
AAPL: The Event Delivered, But Price Still Needs To Confirm Apple gave investors plenty to digest yesterday: the $1,999 iPhone Duo, iPhone 18 Pro and Pro Max, upgraded AirPods, Apple Watch Series 12 and Ultra 4, plus a deeper AI push through its latest software experience. The foldable iPhone is clearly the headline, but for investors, the bigger question is whether this product cycle can translate into a meaningful upgrade cycle. What caught my attention is the reaction in AAPL itself. Despite the scale of the announcements, Apple finished around $315.34, down roughly 0.28%, with price still trading inside its broader ascending channel rather than breaking higher. 📈 The chart remains constructive, but AAPL is now approaching a key decision area. Higher lows are still developing inside the rising channel, while price continues to test the upper boundary. That makes the technical breakout more important than the event headline itself. If AAPL can push through the channel resistance and hold above it with volume, the structure would favor another upside leg. But there is another possibility. The market may be telling us that the iPhone Duo, higher Pro pricing and AI improvements were already partially priced in. Major Apple launches can also produce short-term sell-the-news reactions before the market reassesses the longer-term earnings impact. So I'm watching price confirmation rather than chasing the narrative. Bull case: breakout above channel resistance → volume confirmation → continuation toward the next resistance. Bear case: rejection at the upper boundary → loss of the rising channel → deeper pullback before another breakout attempt. The event delivered the narrative. Now AAPL needs to deliver the price confirmation. Would you buy the dip inside the channel, or wait for AAPL to break and hold above resistance first? $AAPLXUSDT #ByXIMPACT
The Gold is breaking below $4,300 and this selloff is becoming more than a normal pullback. XAU/USD fell to around $4,303 on Wednesday, its lowest level in more than three weeks, with gold now facing a fourth straight session of losses. The move comes as renewed U.S.-Iran tensions push oil higher, while the U.S. 10-year yield climbs toward 4.81% and markets price roughly a 70% chance of a Fed hike this month. The less-obvious part is the reaction to geopolitical risk. Normally, escalating conflict should strengthen gold's safe-haven bid. But this time, higher oil prices are creating another problem: inflation expectations are rising alongside yields, making the Fed more likely to stay restrictive. That is allowing the dollar and Treasury yields to overpower gold's traditional safe-haven demand. Technically, $4,300 is now the battleground. Gold is trading below its 200-day moving average, so buyers need to reclaim lost levels before the structure starts looking constructive again. Bearish: rejection around $4,350–$4,400 → targets $4,250, then $4,200. Bullish: reclaim $4,400 and hold → opens a recovery toward $4,480–$4,520. Invalidation: sustained acceptance above $4,520 would weaken the current bearish structure. The next major catalyst is U.S. labor data. A weak ADP/NFP sequence could reduce Fed-hike expectations and give gold the liquidity relief it needs. A strong labor report would reinforce the higher-yields narrative and potentially put $4,300 under much greater pressure. Gold isn't losing because safe-haven demand disappeared. It's losing because the market is currently treating inflation and higher rates as the bigger risk. $XAUTUSDT #ByXIMPACT
Nvidia is still growing at a rate most mega-cap companies can’t touch but the stock is starting to face a different test. Nvidia just reported $96.2B in quarterly revenue, up 106% YoY and 18% sequentially. Data Center revenue reached $89B, up 117% YoY. Even more important, management guided Q3 revenue to $108B ±2%. The less-obvious signal is the gap between fundamental growth and market expectations. Nvidia's Vera Rubin platform is already ramping into full production across major AI infrastructure partners, meaning the company isn't relying only on Blackwell to sustain the cycle. But macro has suddenly become a bigger problem. The U.S. 10-year yield has pushed toward 4.8%, while September Fed hike expectations have risen toward 67–68% as oil and inflation concerns intensify. That creates pressure on high-valuation technology stocks even when their underlying businesses remain strong. So the setup is becoming more interesting. Bullish: hold the $215–$220 area and reclaim $225–$230 → momentum can target $240, then $250. Bearish: lose $215 → watch $205, with $195 becoming the deeper support zone. Invalidation: sustained acceptance above $230 would weaken the short-term bearish thesis. The AI story hasn't broken. The question is whether NVDA can continue climbing while yields are telling investors to demand a higher return for owning growth. That's the divergence I'm watching now: record AI demand versus increasingly hostile macro conditions. $NVDAXUSDT #ByXIMPACT
Tesla and SpaceX are entering an important stretch where execution matters more than the Musk narrative. Tesla delivered 480,126 vehicles in Q2 and deployed 13.5 GWh of energy storage, but its China-made EV sales growth slowed sharply to 3.6% YoY in August. Meanwhile, Cybercab has moved into commercial deployment in Austin, but NHTSA has asked Tesla to answer questions by September 30 about its self-certification. SpaceX is facing a different test. Q2 revenue surged 91.9% YoY to $7.8B, with AI revenue jumping 247.5% to $2.6B and Starlink connectivity revenue reaching $4.3B. But the growth requires enormous investment: AI capex alone reached $15.8B in Q2. SpaceX is now targeting September 28 for Starship Flight 14, its first revenue-generating Starship mission, carrying 26 Starlink V3 satellites. The market is also giving investors a clear technical test. TSLA is around the $390 area, while SPCX closed at $148.36 on September 23 after falling 4.11%; the latest session has pushed it back toward the $146–$150 zone. SpaceX's upcoming lockup expiration is another near-term supply consideration, with roughly 328 million shares becoming eligible to trade. My setup: • $TSLA Bullish: reclaim $400 → $420, then $450. • $TSLA Bearish: lose $370 → $355, then $340. • $SPCX Bullish: reclaim $155–$160 → $175, then $190. • $SPCX Bearish: lose $145 → $135, then $125. The interesting question isn't which company has the bigger Musk-led narrative. It's whether Tesla can turn autonomy into a scalable business while SpaceX converts Starlink and AI growth into enough cash flow to support its massive capital spending without the market demanding a reset in valuation first. $TSLAXUSDT $SPCXXUSDT #ByXIMPACT
$HYPE: Institutional Money Is Arriving. The Next Test Is Supply. Hyperliquid is entering a different phase. The question is no longer just whether traders want an on-chain derivatives exchange. It’s whether traditional financial institutions can help turn Hyperliquid into infrastructure for a much broader market—and whether HYPE holders will benefit. Three developments stand out. 1. Wall Street is exploring Hyperliquid’s infrastructure. On October 29, ICE announced a partnership with Trade[XYZ] to develop regulated U.S. perpetual markets using Hyperliquid technology. The planned products could cover crypto, equities, commodities, and foreign exchange. A separate development on October 26 saw Hyperliquid identify Kraken parent Payward as its intended first CFTC-regulated HIP-3 deployer, subject to approvals. These moves suggest that Hyperliquid’s potential market extends beyond crypto-native traders. But neither announcement guarantees direct value accrual to HYPE holders. 2. Regulated investment products are creating another demand channel. Spot HYPE investment products offer traditional investors exposure without requiring them to manage tokens directly. By October 30, three products collectively held approximately $450 million in assets, according to ETF flow tracking data. That is an encouraging sign of investor interest—but assets under management are not the same as fresh daily inflows, and flows can reverse. 3. Supply pressure remains part of the equation. The next major scheduled core-contributor unlock is November 6, with approximately 9.92 million HYPE listed for release by current market trackers. Unlocking tokens does not automatically mean they will be sold, but it creates another supply event for the market to absorb. Meanwhile, Hyperliquid’s Assistance Fund continues buying HYPE using protocol-related revenue. One tracker estimated roughly $65.7 million in buybacks over the previous 30 days as of October 31. The important question is whether sustained demand can outweigh the new supply entering circulation. My take: Hyperliquid is building a credible case as financial-market infrastructure. Institutional partnerships, regulated investment products, and protocol-driven buybacks are meaningful developments—but the strongest long-term signal would be growing real usage alongside durable demand for HYPE. I’m watching three things: regulatory progress, actual ETF inflows, and how the market handles the November unlock. Is $HYPE becoming a long-term infrastructure asset—or is the market pricing in the institutional story too early? $HYPEUSDT #ByXIMPACT
El oro se mantiene en los $4,400 pero el IPC podría desencadenar el próximo gran movimiento $XAUT/USDT cotiza alrededor de los $4,400 después de caer por debajo de este nivel el lunes. El oro al contado alcanzó brevemente los $4,396 aproximadamente, extendiendo la presión tras el informe de empleo de EE. UU. del viernes, que fue más fuerte de lo esperado. Las nóminas de agosto aumentaron 162,000 frente a las 56,000 esperadas, mientras que el desempleo se mantuvo en el 4.1%, lo que llevó a los mercados a valorar en un 60% la posibilidad de una subida de tipos de la Fed en septiembre. Lo menos evidente es cuánta presión macro está absorbiendo el oro sin venirse abajo por completo. El aumento de los rendimientos de los bonos del Tesoro, la subida de los precios del petróleo y las renovadas expectativas de subidas de tipos de la Fed están actuando en contra del metal. Pero, al mismo tiempo, el riesgo geopolítico está respaldando la demanda de refugio seguro, mientras que al dólar le ha costado extender sus ganancias. Eso deja al oro atrapado entre dos fuerzas opuestas. También hay un desarrollo interesante específicamente para $XAUT. Tether está cerrando Alloy y aUSDT mientras redirige explícitamente recursos hacia productos con mayor demanda, liquidez más profunda y mejores oportunidades a largo plazo, incluido XAU₮. Los usuarios actuales de aUSDT tienen hasta el 17 de septiembre para devolver sus aUSDT y recuperar su colateral en XAU₮ a través de la plataforma. Técnicamente, los $4,400 son ahora el campo de batalla. Bajista: rechazo alrededor de los $4,450–$4,500 → perder los $4,400 → objetivos en $4,350, luego $4,300. Alcista: recuperar los $4,500 y romper los $4,540 → abre camino a $4,600, luego $4,700. Invalidación: una aceptación sostenida por debajo de los $4,300 debilitaría significativamente la estructura de recuperación actual. El próximo gran catalizador es la inflación en EE. UU. El IPP llega el jueves y el IPC el viernes. Una cifra de inflación más alta podría reforzar la narrativa de subida de tipos de la Fed, mantener los rendimientos elevados y poner a los $4,400 bajo una seria presión. Un IPC más suave podría revertir parte de esa repricing agresiva y darle al oro espacio para atacar nuevamente los $4,500. Pero aquí está la distinción importante: El oro no necesita repuntar todavía. Necesita demostrar que los $4,400 son una base real. No quiero perseguir el rebote. Quiero ver que los $4,500 pasen de resistencia a soporte. Hasta entonces, esta sigue siendo una zona de decisión, no una reversión confirmada. ¿El oro recuperará los $4,500 antes del IPC, o finalmente cederán los $4,400? $XAUTUSDT #ByXIMPACT
AAPL: El evento cumplió, pero el precio aún necesita confirmar Apple dio a los inversionistas mucho que digerir ayer: el iPhone Duo de $1,999, el iPhone 18 Pro y Pro Max, AirPods mejorados, el Apple Watch Series 12 y Ultra 4, además de un impulso más profundo hacia la IA a través de su más reciente experiencia de software. El iPhone plegable es claramente el titular, pero para los inversionistas, la pregunta más importante es si este ciclo de producto puede traducirse en un ciclo de actualización significativo. Lo que llamó mi atención es la reacción en AAPL mismo. A pesar de la magnitud de los anuncios, Apple terminó alrededor de $315.34, con una baja de aproximadamente 0.28%, y el precio sigue operando dentro de su canal ascendente más amplio en lugar de romper al alza. 📈 El gráfico sigue siendo constructivo, pero AAPL se acerca ahora a una zona de decisión clave. Se siguen formando mínimos más altos dentro del canal ascendente, mientras el precio continúa probando el límite superior. Eso hace que la ruptura técnica sea más importante que el titular del evento en sí. Si AAPL puede superar la resistencia del canal y mantenerse por encima con volumen, la estructura favorecería otro tramo alcista. Pero existe otra posibilidad. El mercado podría estar diciéndonos que el iPhone Duo, los precios más altos del Pro y las mejoras de IA ya estaban parcialmente descontados. Los grandes lanzamientos de Apple también pueden producir reacciones de corto plazo de "vender con la noticia" antes de que el mercado reevalúe el impacto en las ganancias a largo plazo. Así que estoy observando la confirmación del precio en lugar de perseguir la narrativa. Escenario alcista: ruptura por encima de la resistencia del canal → confirmación de volumen → continuación hacia la siguiente resistencia. Escenario bajista: rechazo en el límite superior → pérdida del canal ascendente → retroceso más profundo antes de otro intento de ruptura. El evento entregó la narrativa. Ahora AAPL necesita entregar la confirmación del precio. ¿Comprarías la caída dentro del canal, o esperarías primero a que AAPL rompa y se mantenga por encima de la resistencia? $AAPLXUSDT #ByXIMPACT
CRCL & TSLA: Two Growth Stories, Two Tests
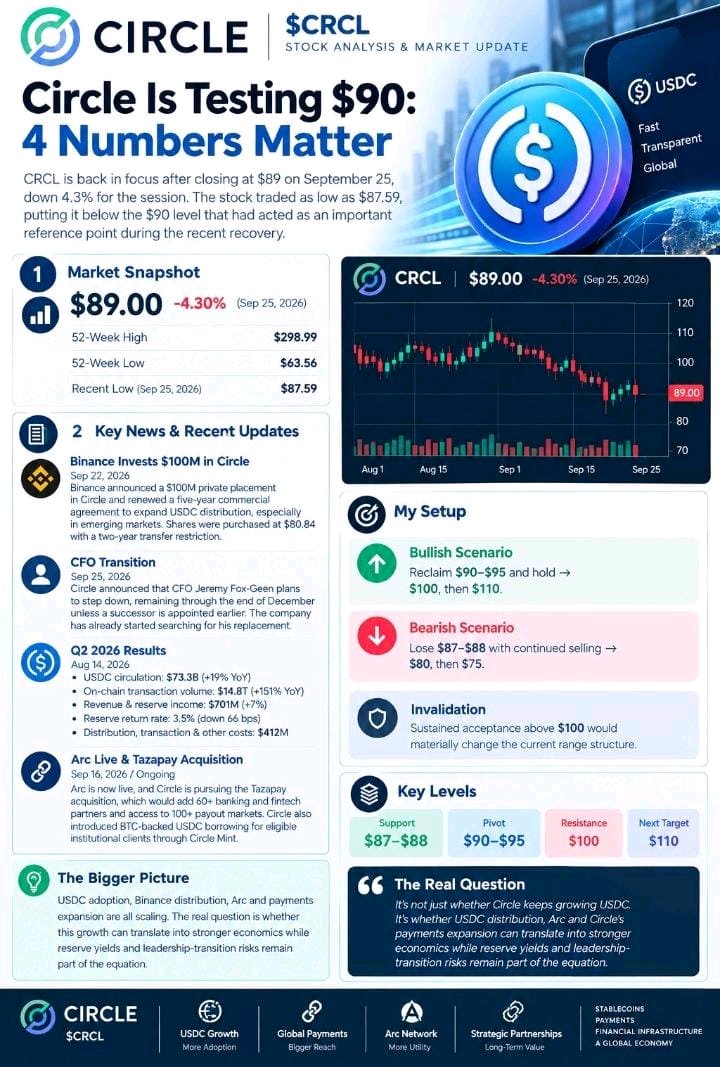
Circle and Tesla are telling very different growth stories, but both are approaching levels where execution matters more than the narrative. CRCL closed at $89 on September 25, down 4.3% for the session. The immediate pressure comes after a strong September rebound, but the fundamental backdrop remains active: Binance invested $100M in Circle at $80.84 per share and renewed a five-year USDC partnership. Circle also launched Arc mainnet with more than 100 institutional and ecosystem builders, while USDC circulation had surpassed $74B. The new risk is management transition. Circle announced CFO Jeremy Fox-Green will step down, with a transition planned through December unless a successor arrives sooner. That comes while the business is scaling: Q2 USDC circulation reached $73.3B (+19% YoY), on-chain volume hit $14.8T (+151%), and revenue plus reserve income reached $701M. TSLA closed at $372.11 on September 25, down 1.54%. Tesla now has several catalysts converging: Semi deliveries have begun from its Nevada facility, which is planned for 50,000 trucks annually, while the company recently received an order for 2,500 Semis from a group including Microsoft and PepsiCo. Czech regulators also provisionally approved Tesla's FSD system this week. But Tesla's autonomy story still faces a regulatory test. NHTSA is investigating the certification of up to 1,000 Cybercabs, and Tesla has been ordered to answer questions about the certification by September 30. That creates two very different setups. CRCL setup Bullish: reclaim $90–$95 → $100, then $110. Bearish: lose $87–$88 → $80, then $75. TSLA setup Bullish: reclaim $380–$385 → $400, then $420. Bearish: rejection below $380 and loss of $365 → $350, then $335. The interesting part isn't simply whether CRCL can grow USDC or Tesla can grow autonomy. It's whether Circle can convert stablecoin adoption into durable economics, while Tesla proves that its autonomy and new-product ambitions can scale without execution and regulatory issues becoming the bottleneck.. $TSLAXUSDT $CRCLXUSDT #ByXIMPACT
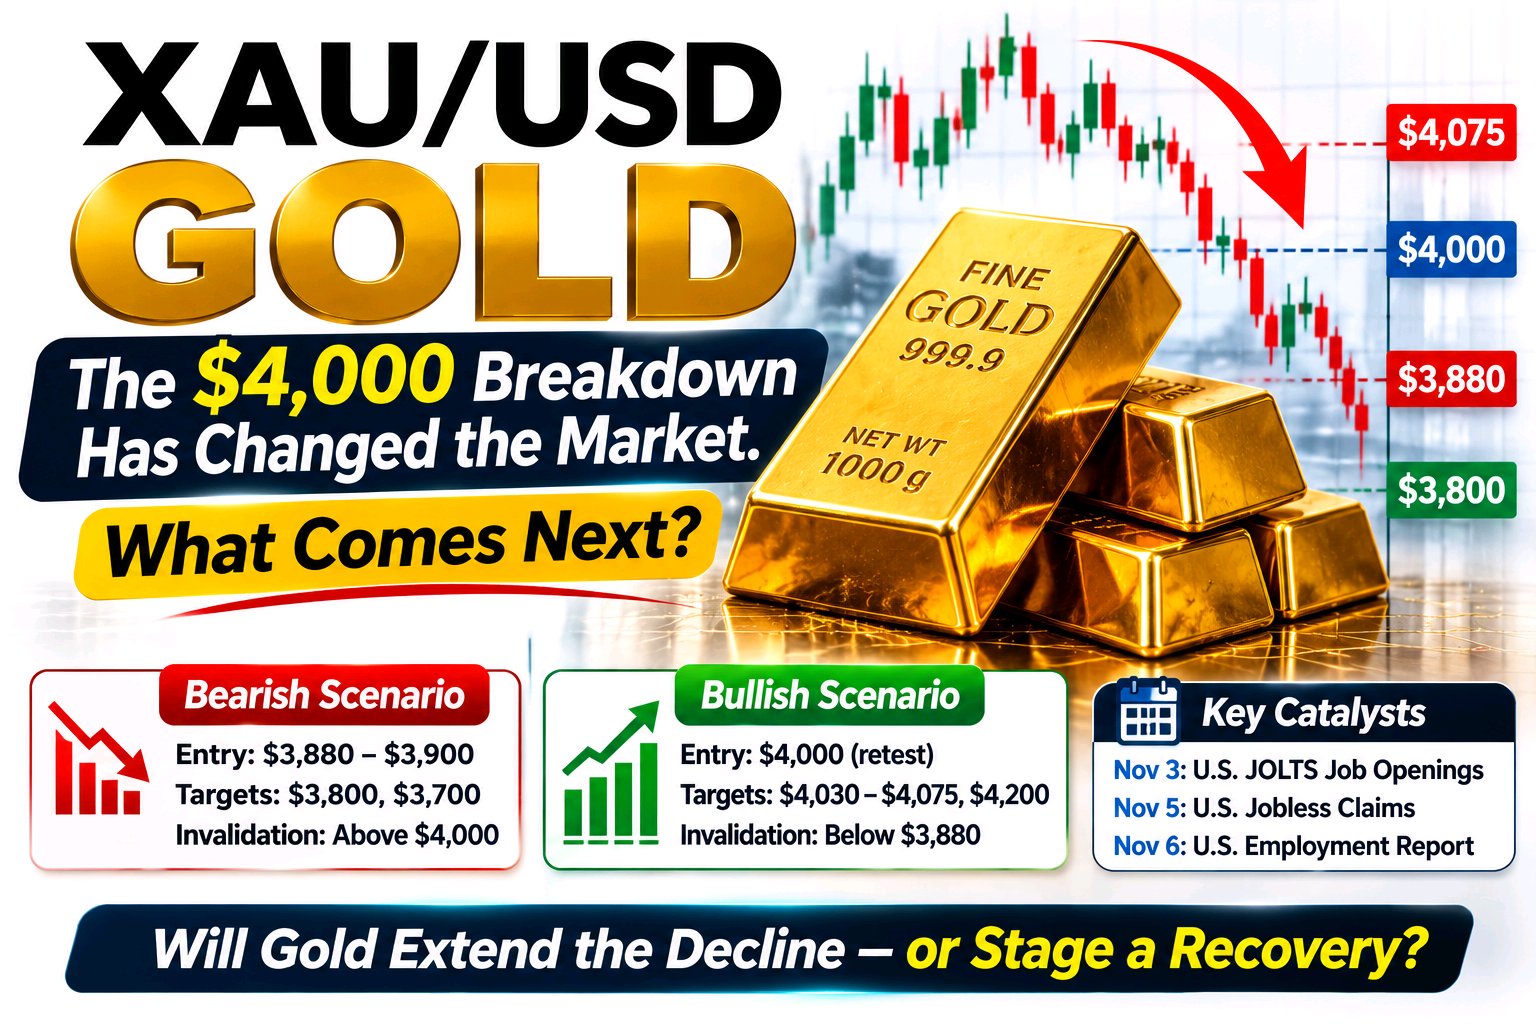
The Gold is breaking below $4,300 and this selloff is becoming more than a normal pullback. XAU/USD fell to around $4,303 on Wednesday, its lowest level in more than three weeks, with gold now facing a fourth straight session of losses. The move comes as renewed U.S.-Iran tensions push oil higher, while the U.S. 10-year yield climbs toward 4.81% and markets price roughly a 70% chance of a Fed hike this month. The less-obvious part is the reaction to geopolitical risk. Normally, escalating conflict should strengthen gold's safe-haven bid. But this time, higher oil prices are creating another problem: inflation expectations are rising alongside yields, making the Fed more likely to stay restrictive. That is allowing the dollar and Treasury yields to overpower gold's traditional safe-haven demand. Technically, $4,300 is now the battleground. Gold is trading below its 200-day moving average, so buyers need to reclaim lost levels before the structure starts looking constructive again. Bearish: rejection around $4,350–$4,400 → targets $4,250, then $4,200. Bullish: reclaim $4,400 and hold → opens a recovery toward $4,480–$4,520. Invalidation: sustained acceptance above $4,520 would weaken the current bearish structure. The next major catalyst is U.S. labor data. A weak ADP/NFP sequence could reduce Fed-hike expectations and give gold the liquidity relief it needs. A strong labor report would reinforce the higher-yields narrative and potentially put $4,300 under much greater pressure. Gold isn't losing because safe-haven demand disappeared. It's losing because the market is currently treating inflation and higher rates as the bigger risk. $XAUTUSDT #ByXIMPACT
Nvidia is still growing at a rate most mega-cap companies can’t touch but the stock is starting to face a different test. Nvidia just reported $96.2B in quarterly revenue, up 106% YoY and 18% sequentially. Data Center revenue reached $89B, up 117% YoY. Even more important, management guided Q3 revenue to $108B ±2%. The less-obvious signal is the gap between fundamental growth and market expectations. Nvidia's Vera Rubin platform is already ramping into full production across major AI infrastructure partners, meaning the company isn't relying only on Blackwell to sustain the cycle. But macro has suddenly become a bigger problem. The U.S. 10-year yield has pushed toward 4.8%, while September Fed hike expectations have risen toward 67–68% as oil and inflation concerns intensify. That creates pressure on high-valuation technology stocks even when their underlying businesses remain strong. So the setup is becoming more interesting. Bullish: hold the $215–$220 area and reclaim $225–$230 → momentum can target $240, then $250. Bearish: lose $215 → watch $205, with $195 becoming the deeper support zone. Invalidation: sustained acceptance above $230 would weaken the short-term bearish thesis. The AI story hasn't broken. The question is whether NVDA can continue climbing while yields are telling investors to demand a higher return for owning growth. That's the divergence I'm watching now: record AI demand versus increasingly hostile macro conditions. $NVDAXUSDT #ByXIMPACT
Tesla and SpaceX are entering an important stretch where execution matters more than the Musk narrative. Tesla delivered 480,126 vehicles in Q2 and deployed 13.5 GWh of energy storage, but its China-made EV sales growth slowed sharply to 3.6% YoY in August. Meanwhile, Cybercab has moved into commercial deployment in Austin, but NHTSA has asked Tesla to answer questions by September 30 about its self-certification. SpaceX is facing a different test. Q2 revenue surged 91.9% YoY to $7.8B, with AI revenue jumping 247.5% to $2.6B and Starlink connectivity revenue reaching $4.3B. But the growth requires enormous investment: AI capex alone reached $15.8B in Q2. SpaceX is now targeting September 28 for Starship Flight 14, its first revenue-generating Starship mission, carrying 26 Starlink V3 satellites. The market is also giving investors a clear technical test. TSLA is around the $390 area, while SPCX closed at $148.36 on September 23 after falling 4.11%; the latest session has pushed it back toward the $146–$150 zone. SpaceX's upcoming lockup expiration is another near-term supply consideration, with roughly 328 million shares becoming eligible to trade. My setup: • $TSLA Bullish: reclaim $400 → $420, then $450. • $TSLA Bearish: lose $370 → $355, then $340. • $SPCX Bullish: reclaim $155–$160 → $175, then $190. • $SPCX Bearish: lose $145 → $135, then $125. The interesting question isn't which company has the bigger Musk-led narrative. It's whether Tesla can turn autonomy into a scalable business while SpaceX converts Starlink and AI growth into enough cash flow to support its massive capital spending without the market demanding a reset in valuation first. $TSLAXUSDT $SPCXXUSDT #ByXIMPACT