Suhaif
10695Me gusta0Compartir en el chat222Aficionados20Seguir
dex hunter
dex hunter
IPC: La inflación sigue siendo un riesgo importante para el mercado.
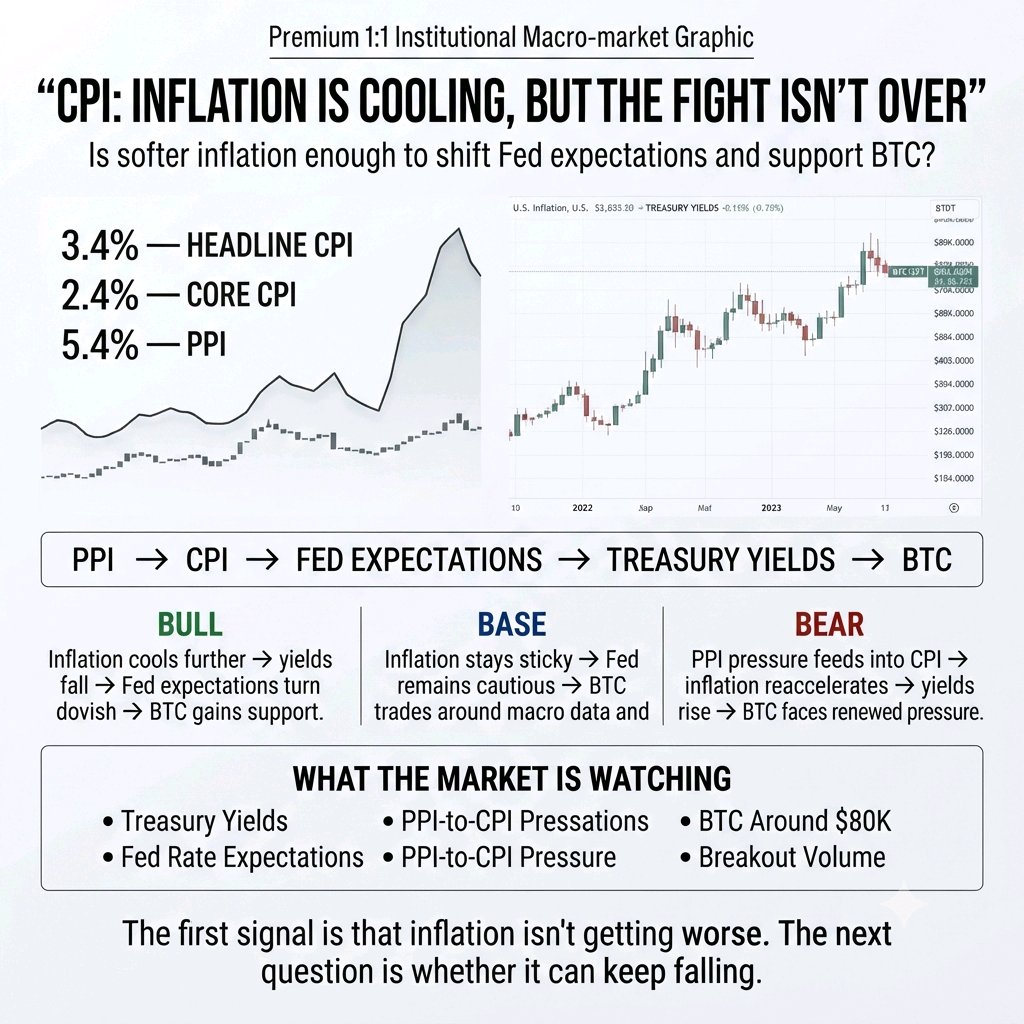
El último informe del IPC redujo los temores de otro shock inflacionario, pero no eliminó el problema. El IPC general se situó en un 3.4% interanual, mientras que el IPC subyacente se mantuvo en un 2.4%. Ninguno superó las expectativas, lo que dio un respiro a los activos de riesgo y ayudó a que BTC subiera. Pero la señal más importante podría venir del IPP. El IPP de ayer fue del 5.4% interanual, lo que demuestra que la presión de los precios a nivel productor sigue siendo elevada. Si esos costos siguen trasladándose a la economía, el IPC podría mantenerse pegajoso por más tiempo. Eso crea tres resultados posibles: Escenario alcista (Bull case): La inflación sigue enfriándose → los rendimientos de los bonos del Tesoro caen → las expectativas de la Fed se vuelven más moderadas (dovish) → BTC y los activos de riesgo obtienen apoyo. Escenario base: La inflación se mantiene persistente → la Fed sigue siendo cautelosa → los mercados continúan reaccionando a cada dato macroeconómico. Escenario bajista (Bear case): La presión del IPP se traslada al IPC → la inflación se acelera nuevamente → las expectativas de recorte de tasas se debilitan → los rendimientos suben → BTC enfrenta una nueva presión. Conclusión del mercado El IPC dio alivio al mercado, no certeza. Estoy vigilando: • Los rendimientos de los bonos del Tesoro • Las expectativas de tasas de la Fed • La presión del IPP al IPC • La reacción de BTC alrededor de los $80K • El volumen detrás de cualquier ruptura El verdadero riesgo no es un solo dato de IPC alto. Es que la inflación se mantenga lo suficientemente alta como para que la Fed siga siendo restrictiva por más tiempo. #ByXIMPACT $BTCUSDT $HYPEUSDT
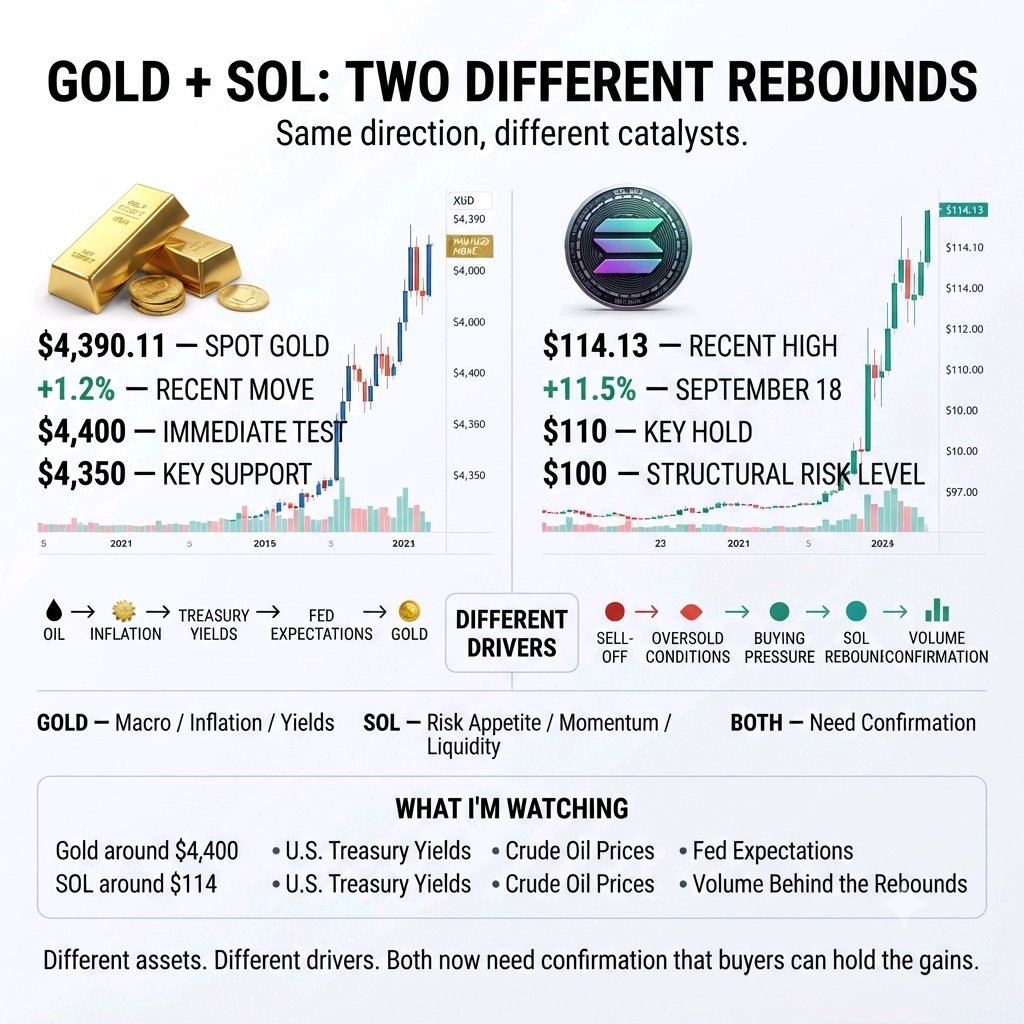
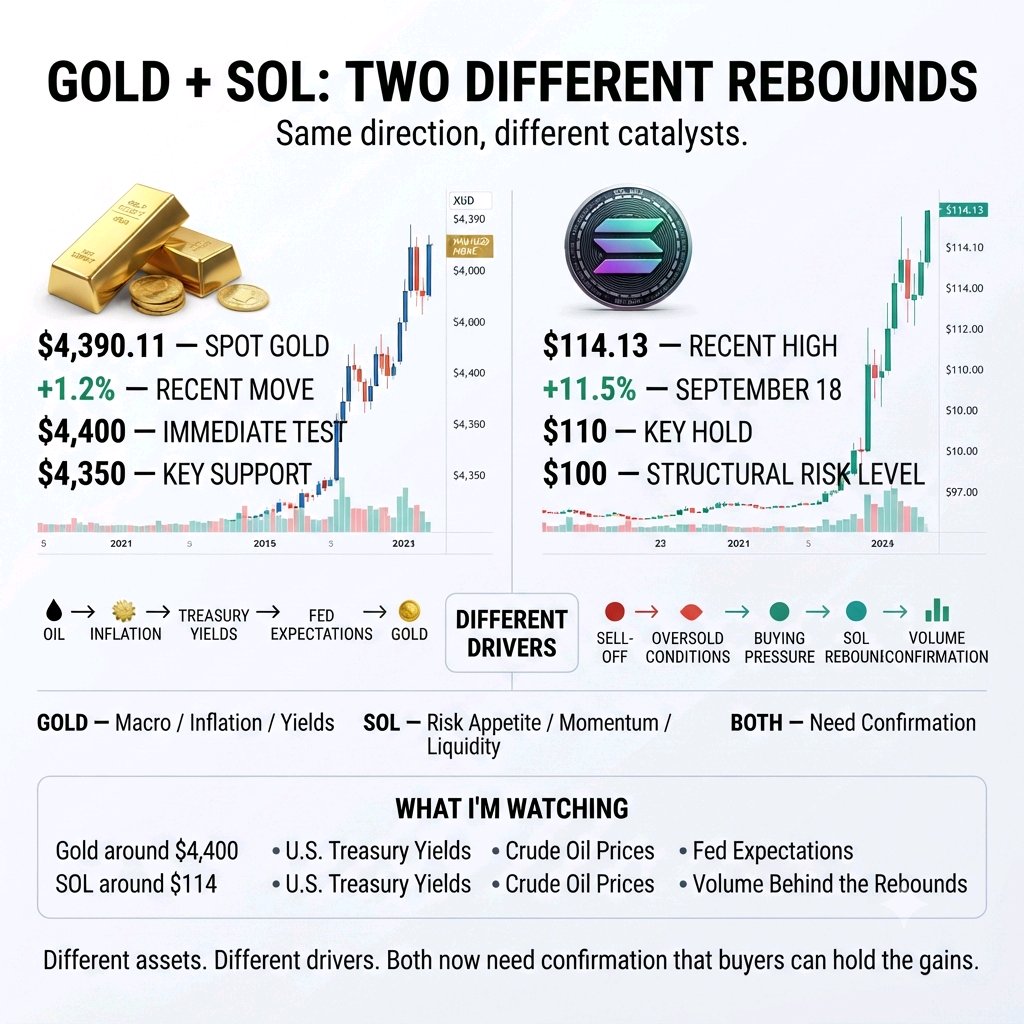
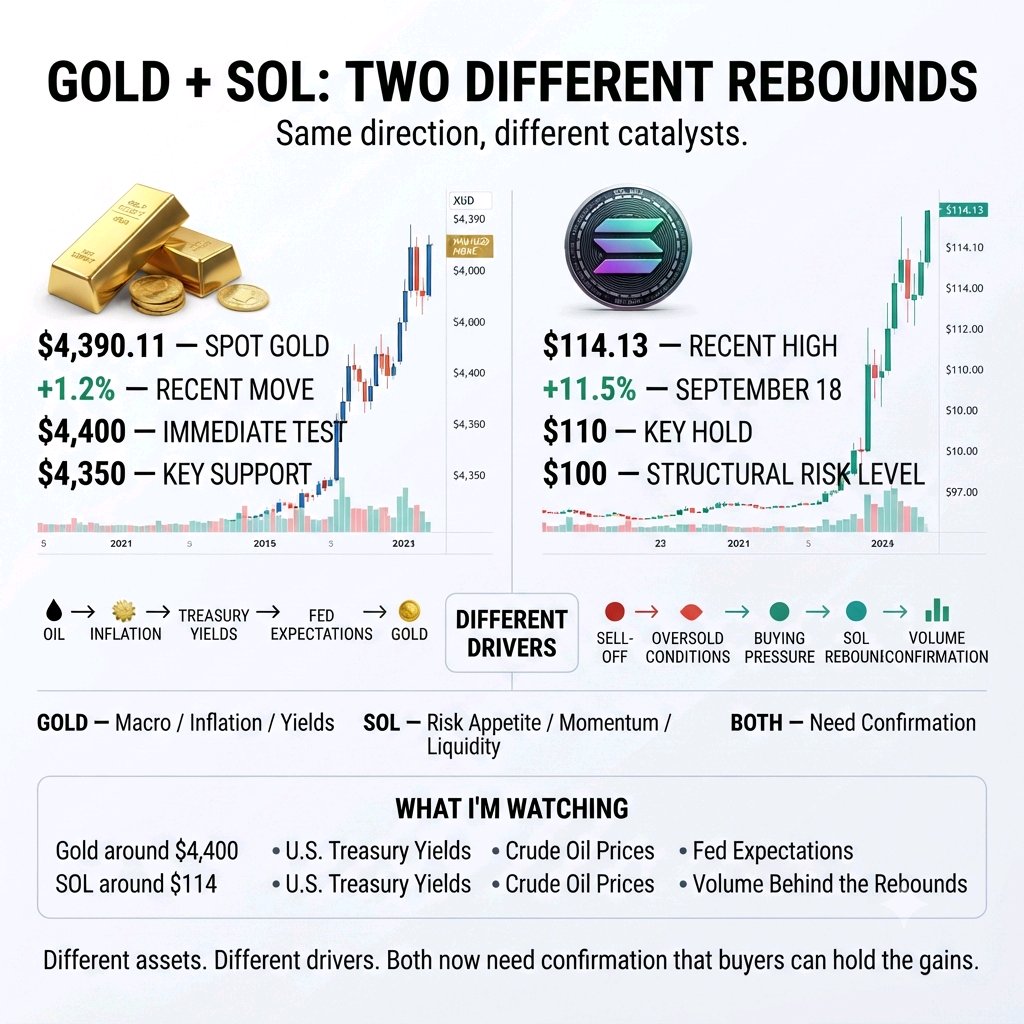
Gold and Solana are both pushing higher, but the reasons behind the moves are very different. Spot gold climbed 1.2% to $4,390.11 as easing oil prices reduced some inflation pressure. SOL, meanwhile, jumped 11.5% on September 18, reaching $114.13 before holding above $113. That difference matters. Gold is reacting mainly to macro conditions: oil, inflation expectations, Treasury yields and Fed expectations. SOL is reacting more like a high-beta risk asset, with its rebound coming after a sharp move down toward $97 earlier in the week. So I'm watching whether both moves can hold after the initial reaction. Gold: $4,400 is the immediate test. Holding above $4,350 would keep the recovery structure intact, while renewed pressure from yields or oil could change the setup. SOL: $114 is the immediate resistance area. Holding above $110 would keep the recent breakout attempt constructive, while losing $100 would weaken the recovery. The interesting part isn't that Gold and SOL are both rising. It's whether their respective catalysts can keep supporting the moves after the first wave of buying fades. I'm watching: • Gold around $4,400 • SOL around $114 • U.S. Treasury yields • Crude oil prices • Fed expectations • Volume behind the rebounds Different assets. Different drivers. But both now need confirmation that buyers can hold the gains. #ByXIMPACT $XAUTUSDT $SOLUSDT
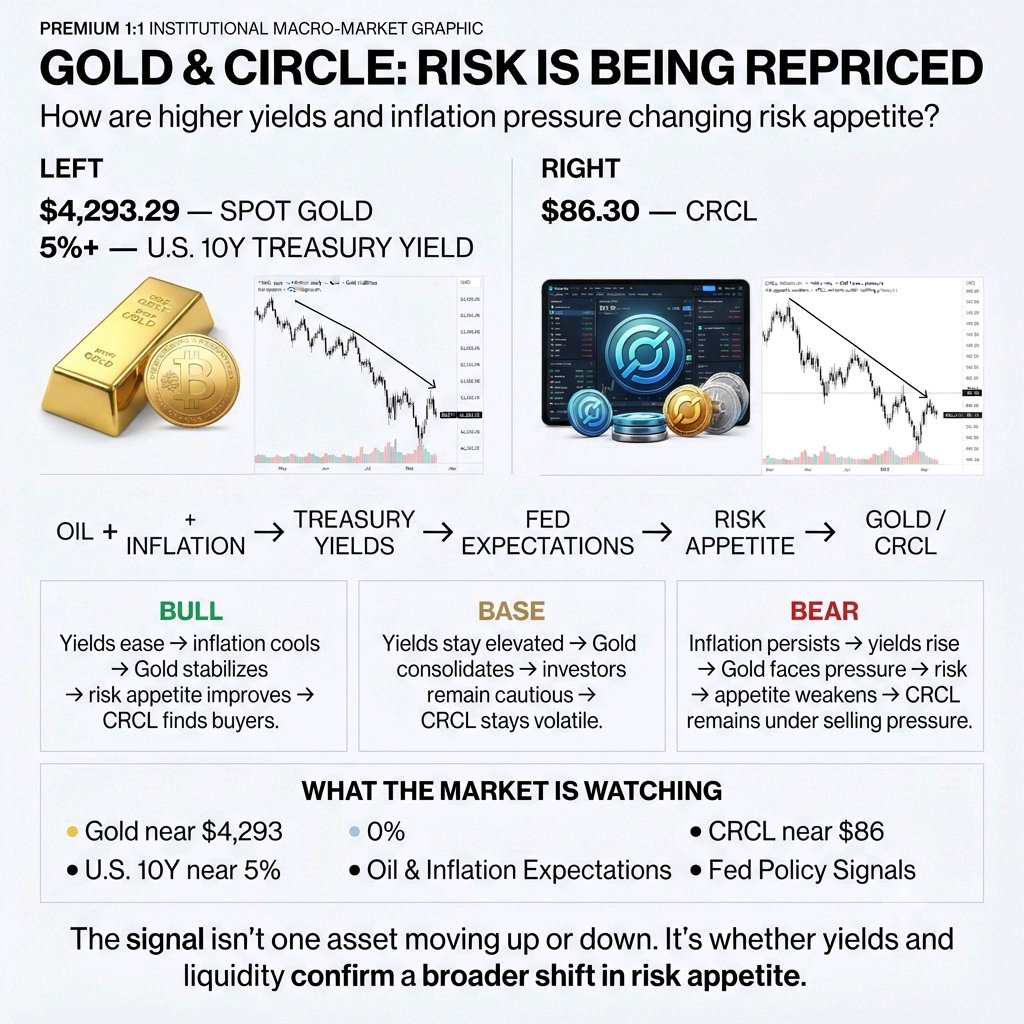
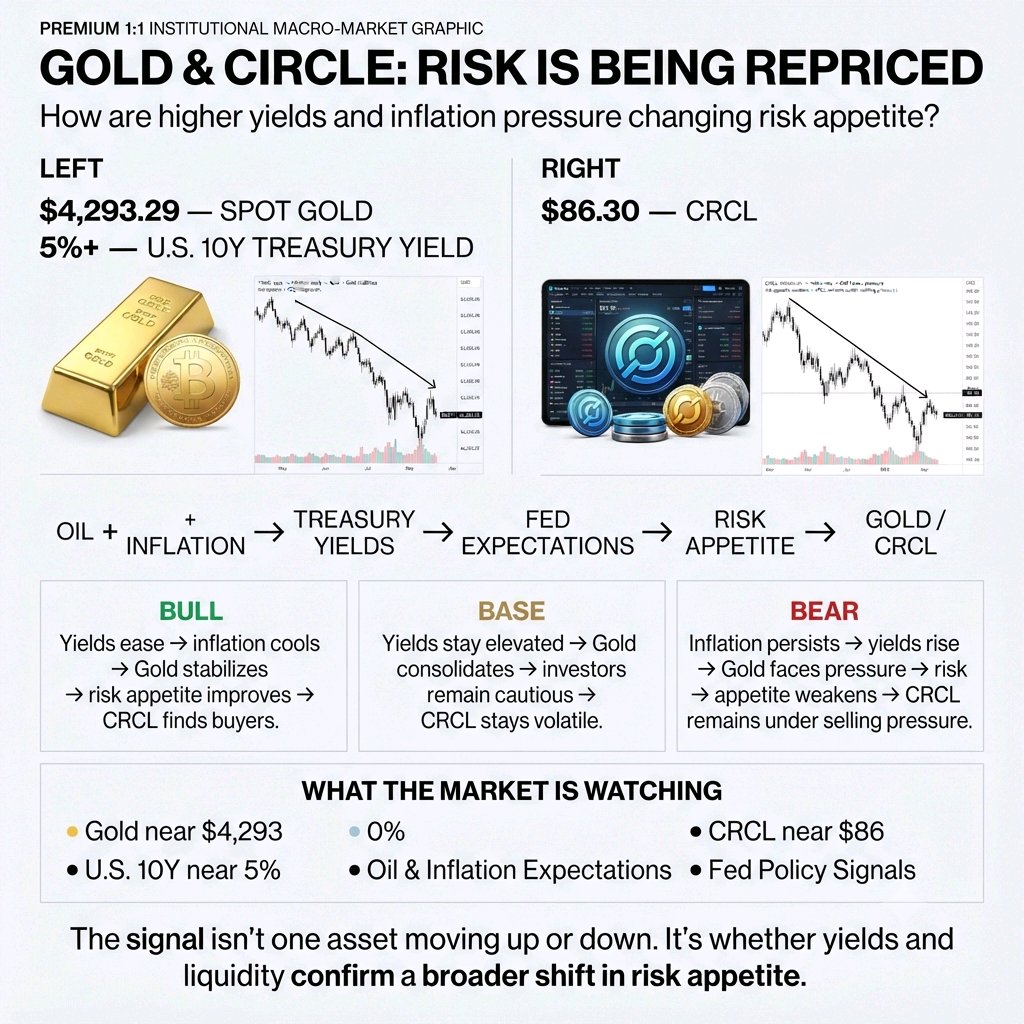
Gold & Circle: Risk Is Being Repriced
Gold has been under pressure as rising oil prices, inflation concerns and higher Treasury yields push rate-hike expectations higher. Spot gold recently fell to $4,293.29, while the 10-year Treasury yield moved above 5%. But the interesting part isn't the gold decline itself. It's how investors are repricing risk across different parts of the market. Circle ($CRCL) has also faced heavy selling pressure, with the stock recently trading around $86.30. Crypto-linked equities remain sensitive to changes in risk appetite, making CRCL another useful asset to watch alongside broader market conditions. That creates three possible outcomes: Bull case: Treasury yields ease → inflation pressure cools → Gold stabilizes → risk appetite improves → CRCL finds buyers. Base case: Yields remain elevated → Gold consolidates → investors stay cautious → CRCL remains volatile. Bear case: Inflation pressure persists → yields rise further → Gold faces more pressure → risk appetite weakens → CRCL remains under selling pressure. Market takeaway Gold is showing how macro pressure is being priced into defensive assets, while CRCL shows how the same risk-off environment can affect crypto-linked equities. I'm watching: • Gold around $4,293 • U.S. 10Y yield near 5% • Oil and inflation expectations • CRCL around $86 • Fed policy signals The key isn't whether one asset moves higher or lower. It's whether yields and liquidity start confirming a broader shift in risk appetite. #ByXIMPACT $XAUTUSDT $CRCLXUSDT
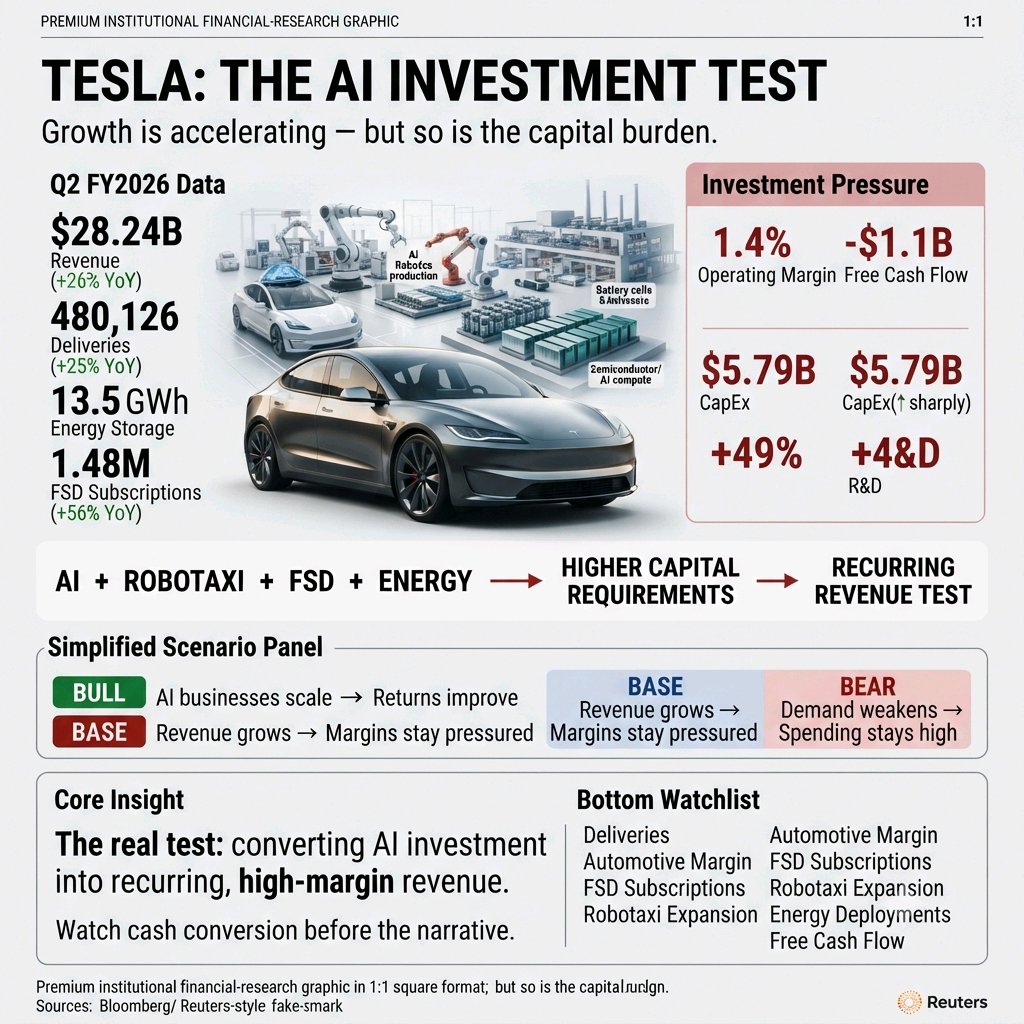
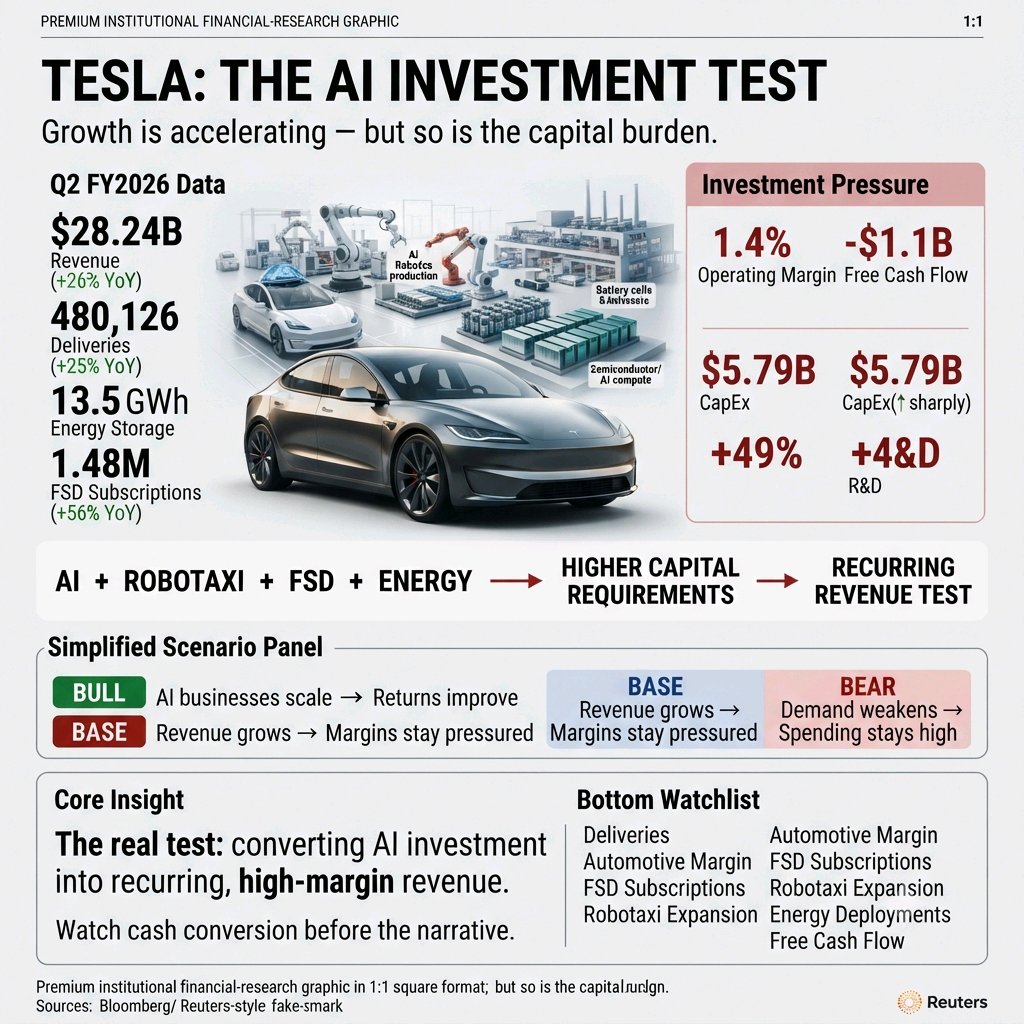
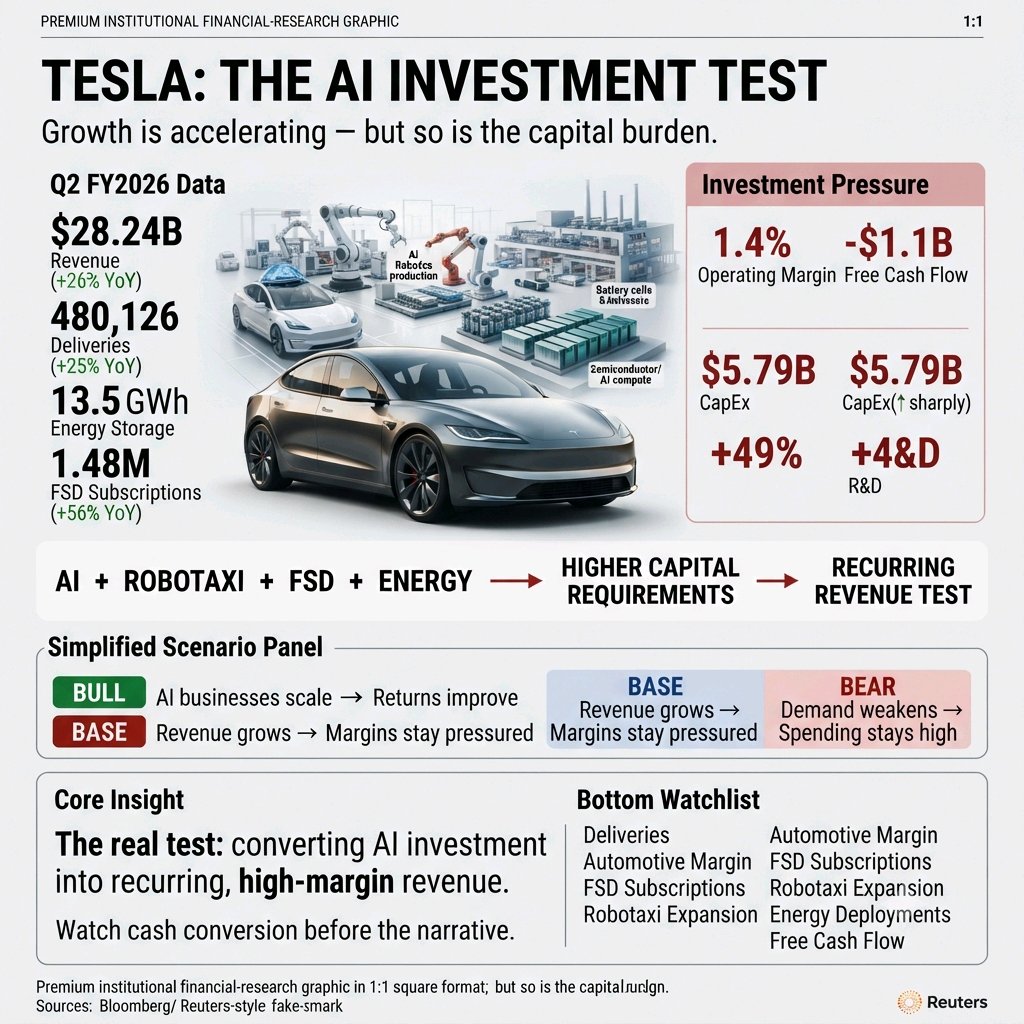
Tesla’s Q2 FY2026 results shifted the debate. Revenue reached $28.24B, +26% YoY, while vehicle deliveries hit a record 480,126, +25%. Energy storage deployments reached 13.5 GWh, while active FSD subscriptions climbed 56% YoY to 1.48M. The deeper signal is Tesla’s transition beyond vehicles. Robotaxi is expanding across U.S. metros, Cybercab has entered production, and Optimus production infrastructure is being built. At the same time, Tesla is investing heavily in AI compute, batteries, semiconductors and new manufacturing capacity. But there’s a critical risk: growth is becoming more capital-intensive before the newer AI businesses generate meaningful financial returns. Q2 operating margin fell to 1.4%, while free cash flow turned -$1.1B as capex surged to $5.79B. R&D also increased 49% YoY. My TSLA framework: Bullish if Robotaxi, FSD and energy scale faster than Tesla’s investment burden. Neutral if revenue keeps growing but margin compression and elevated capex absorb the upside. Bearish if automotive demand weakens while AI, robotics and autonomy require sustained spending without comparable revenue growth. The overlooked signal: Tesla’s biggest constraint may no longer be vehicle demand alone—it’s converting its AI infrastructure investment into recurring, high-margin revenue. The company says battery-pack capacity is currently limiting near-term vehicle production, while its AI and manufacturing expansion is pushing capital requirements higher. For BYX, I’d focus on deliveries, automotive margins, FSD subscriptions, Robotaxi expansion, energy deployments and free cash flow rather than chasing daily price moves. Watch the cash conversion before the narrative. DYOR. Not financial advice. $TSLAXUSDT #ByXIMPACT
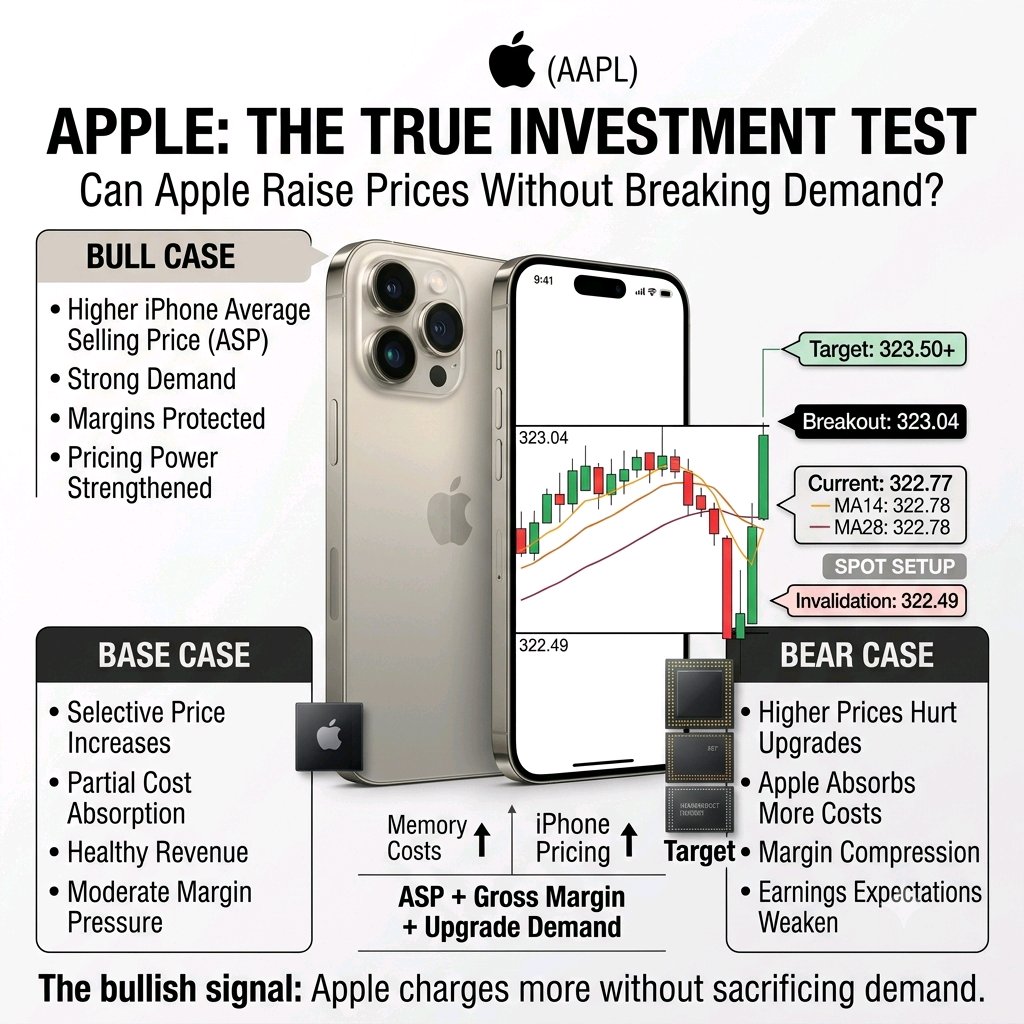
Apple: The Next Big Investment Test
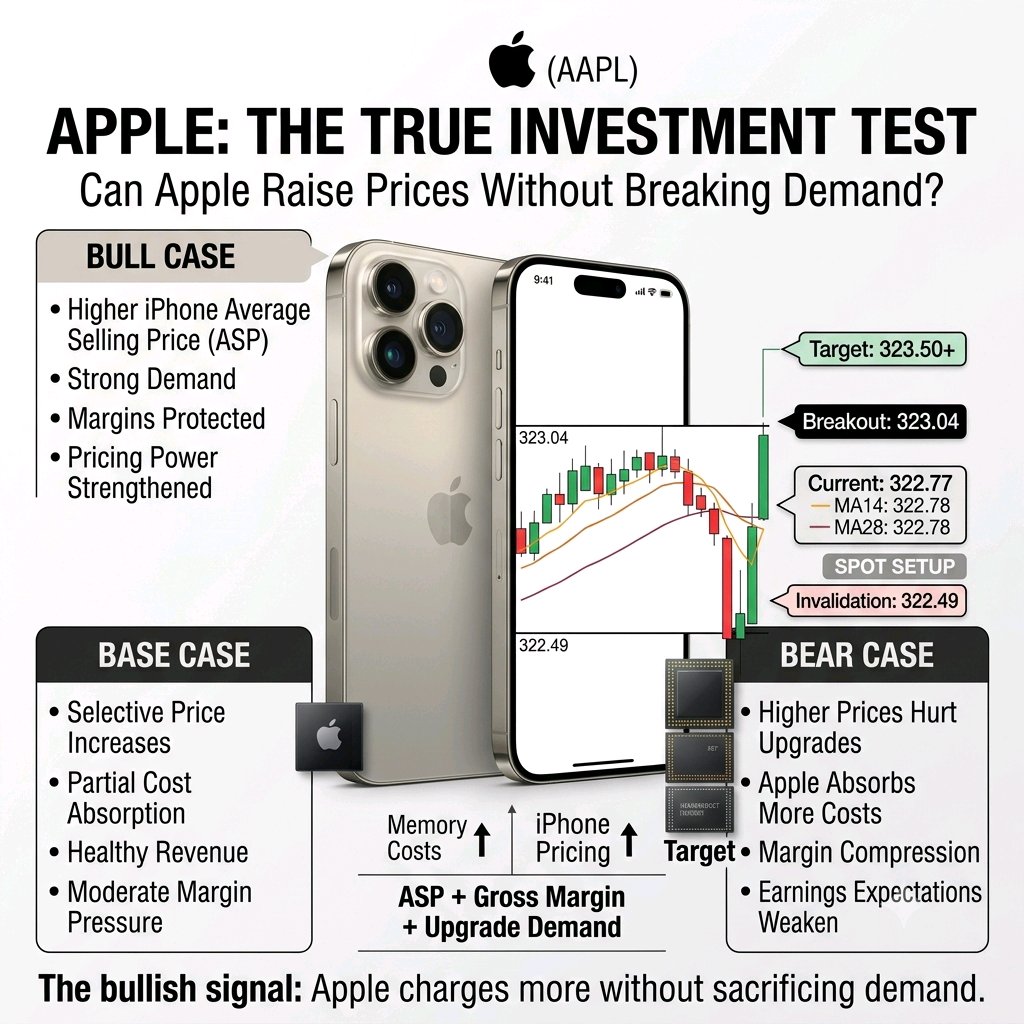
Apple is entering its next iPhone cycle from a position of strength. Revenue reached $109.4B, up 16% year over year, while iPhone demand remained strong. But investors should look beyond the headline growth. Memory costs are rising as AI infrastructure competes for semiconductor capacity. Apple has already raised prices on some Macs and iPads, while management expects memory costs to remain a pressure point in the September quarter. Now the iPhone becomes the bigger test. Reports suggest memory costs for the iPhone 18 Pro could be significantly higher, creating another challenge for Apple's hardware margins. The investment question is simple: Can Apple pass higher costs to consumers without damaging iPhone demand? If the answer is yes, Apple demonstrates something more valuable than short-term revenue growth: pricing power. That could allow Apple to protect margins and earnings even as hardware costs rise. But if Apple absorbs too much of the increase to keep prices attractive, revenue could continue growing while margins come under pressure. My Apple takeaway: Don't watch the iPhone launch only for unit sales. Watch: ASP + gross margin + consumer demand. If Apple raises prices and customers keep upgrading, that would strengthen the case that its ecosystem still gives it exceptional pricing power. If higher prices weaken demand or margins deteriorate, investors may need to rethink future earnings growth. The bullish signal isn't simply “Apple sells more iPhones.” It's: “Apple can charge more without breaking demand.” #ByXIMPACT $AAPLXUSDT
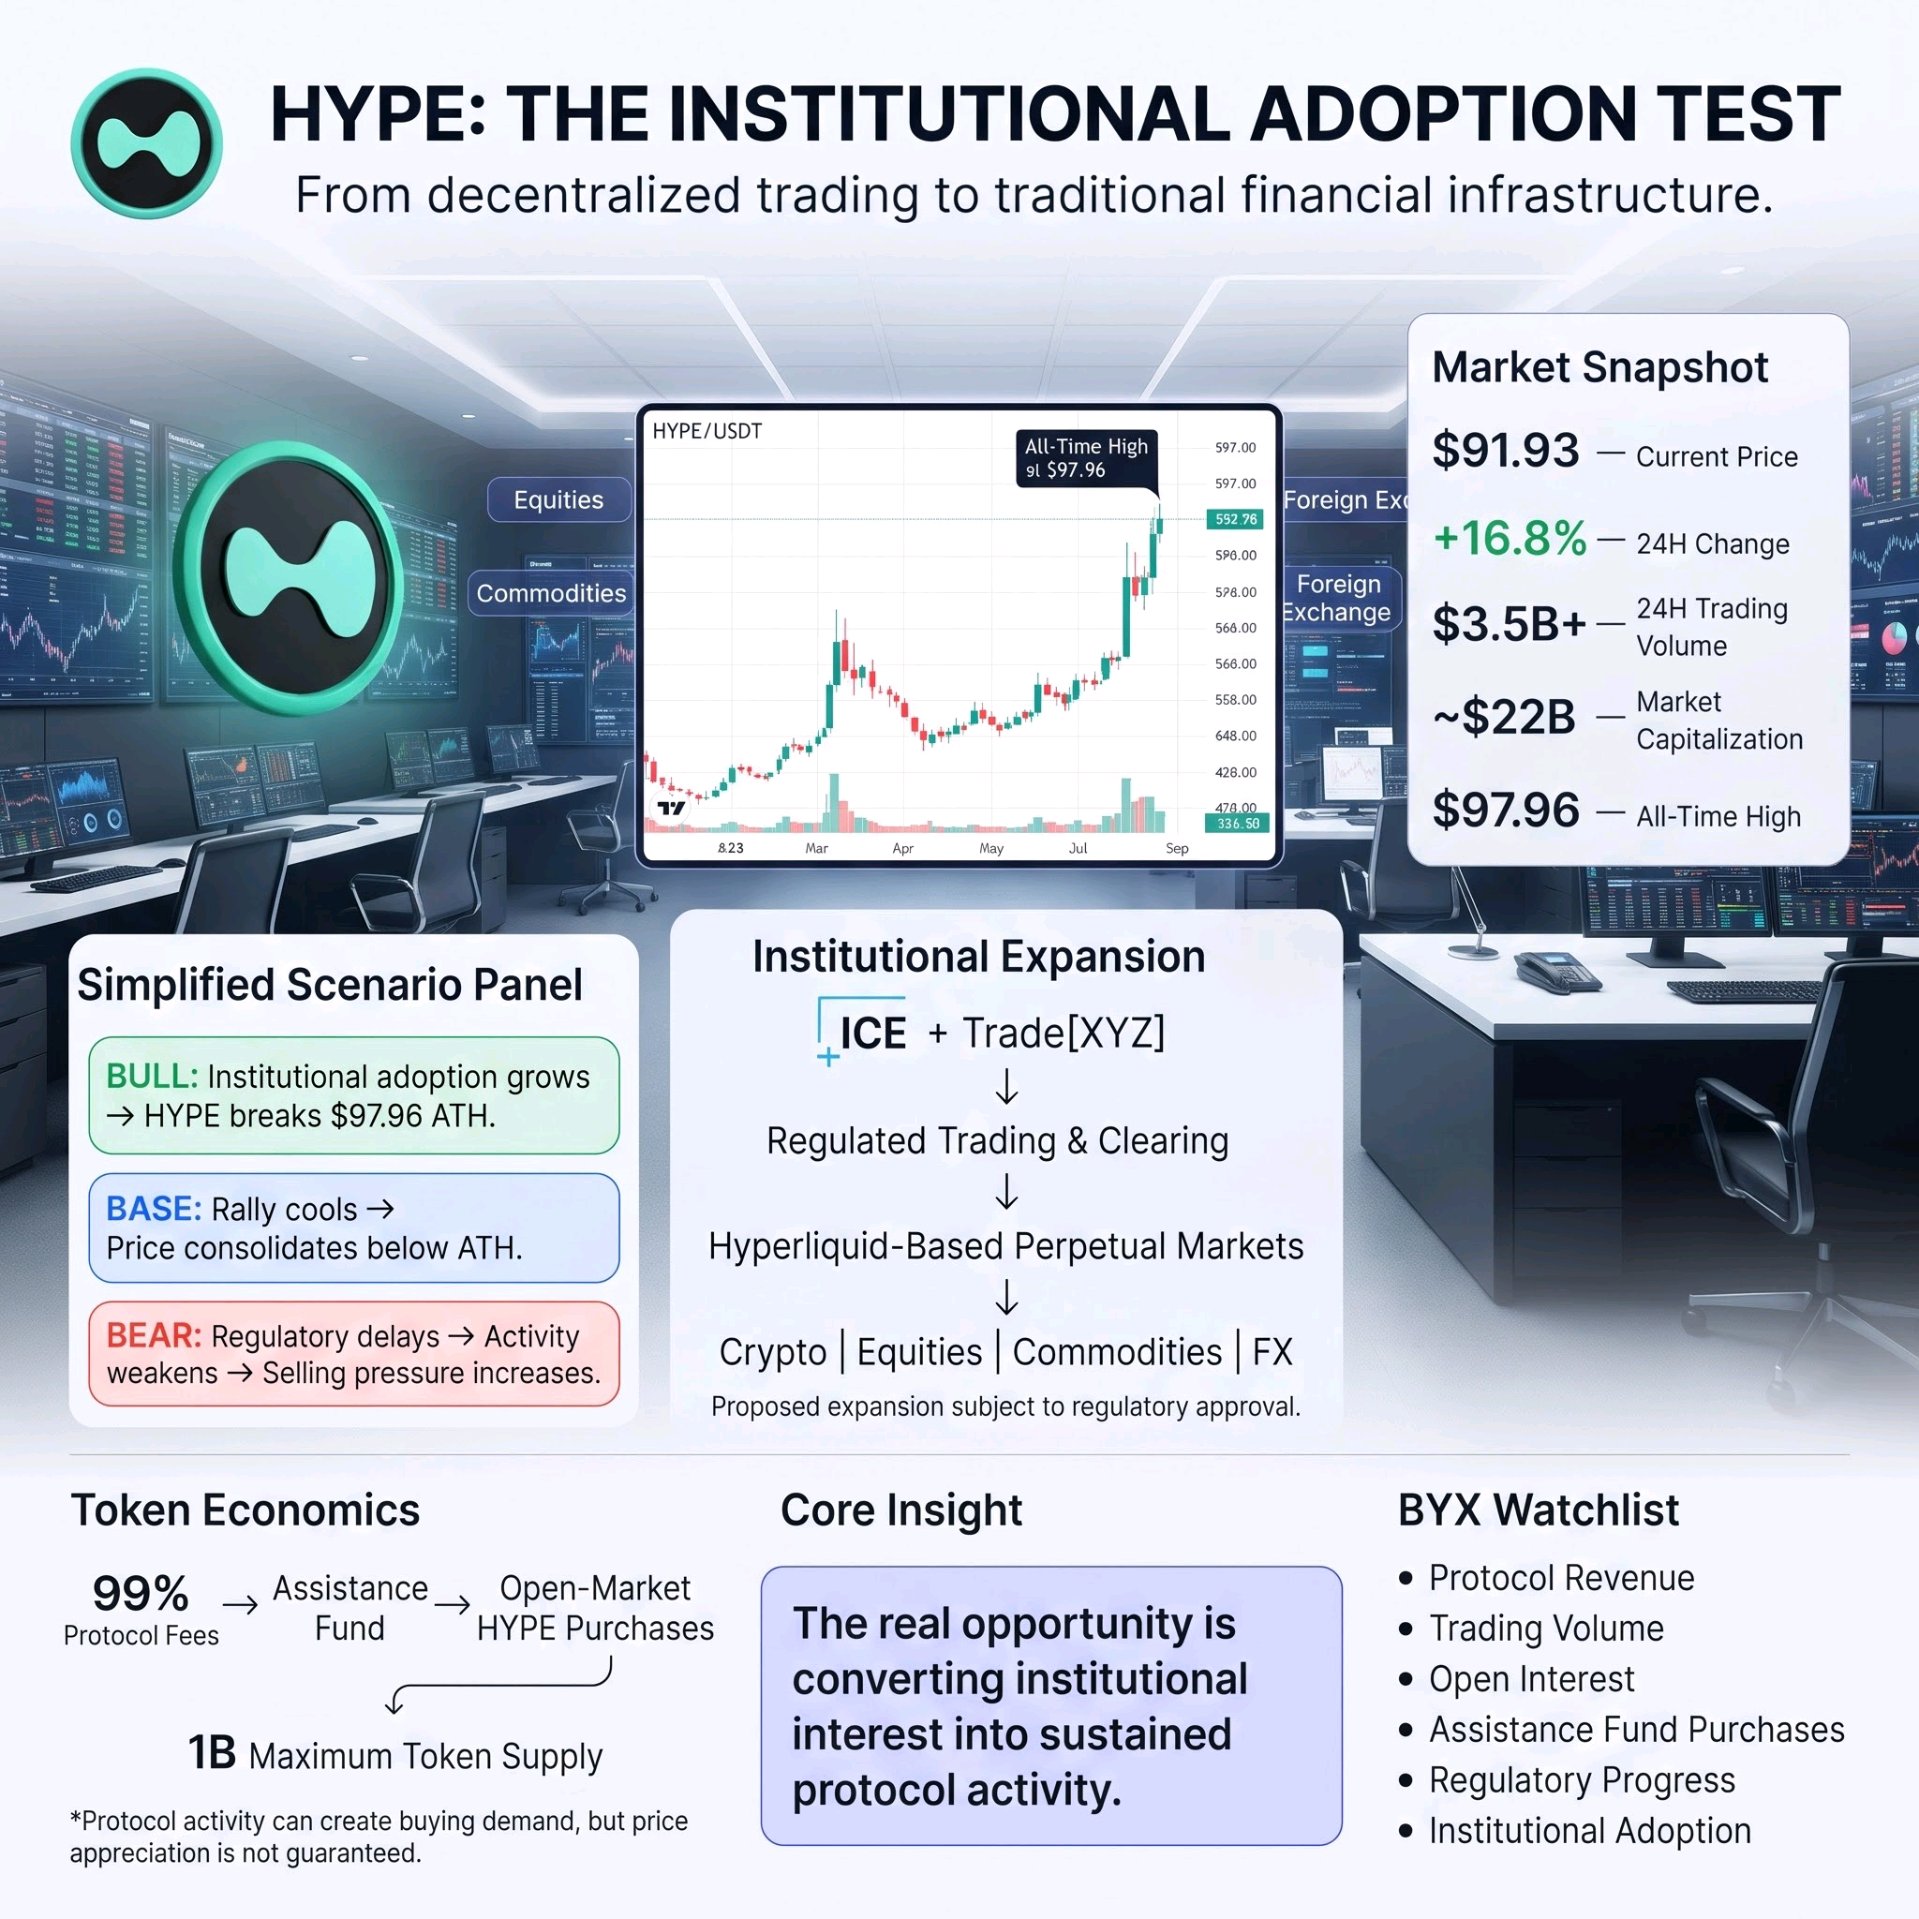
Hyperliquid’s $HYPE market performance shifted the debate. The token climbed to approximately $91.93, gaining 16.8% in 24 hours, while daily trading volume exceeded $3.5B and market capitalization reached roughly $22B. The rally followed an announcement involving Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange. The deeper signal is Hyperliquid’s transition beyond decentralized derivatives trading. Plans involving ICE and Trade[XYZ] could bring Hyperliquid-based perpetual futures into the U.S. through a regulated trading and clearing structure, covering crypto, equities, commodities and foreign exchange. This could position Hyperliquid as infrastructure connecting decentralized markets with traditional finance. But there’s a critical risk: market expectations are moving faster than actual adoption. The proposed partnership remains subject to regulatory approval, and ICE’s involvement does not represent a direct investment in HYPE. Meanwhile, future token supply expansion remains important, given its 1 billion maximum supply. My HYPE framework: Bullish if regulatory progress advances, institutional trading activity increases and HYPE breaks above its $97.96 all-time high. Neutral if the announcement-driven rally cools while price consolidates below previous highs as the market waits for real adoption. Bearish if regulatory delays weaken expectations, protocol activity declines and profit-taking creates sustained selling pressure. The overlooked signal: Hyperliquid's token economics connect protocol activity to potential market demand. Currently, 99% of protocol fees are allocated to the Assistance Fund, which purchases HYPE from the open market. This creates a mechanism through which increased protocol activity can generate additional buying demand, although it doesn't guarantee price appreciation. For BYX, I’d focus on protocol revenue, trading volume, open interest, Assistance Fund purchases, regulatory progress and institutional adoption rather than chasing announcement-driven price movements. Watch the adoption behind the partnership before the narrative. DYOR. Not financial advice. #ByXIMPACT $HYPEUSDT
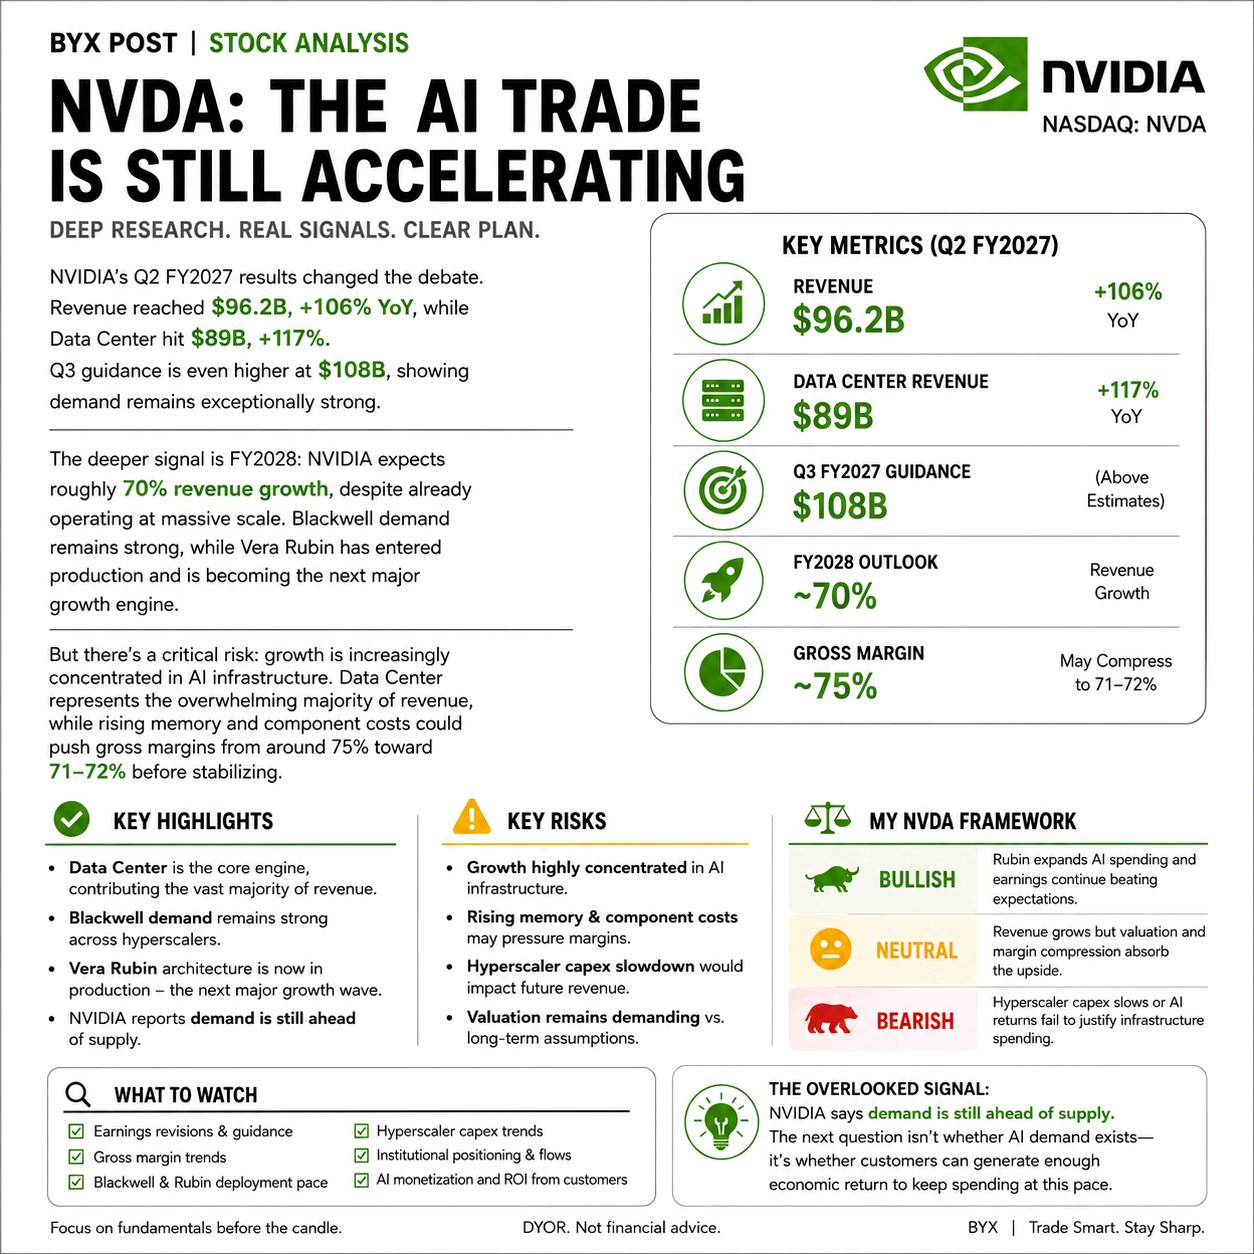
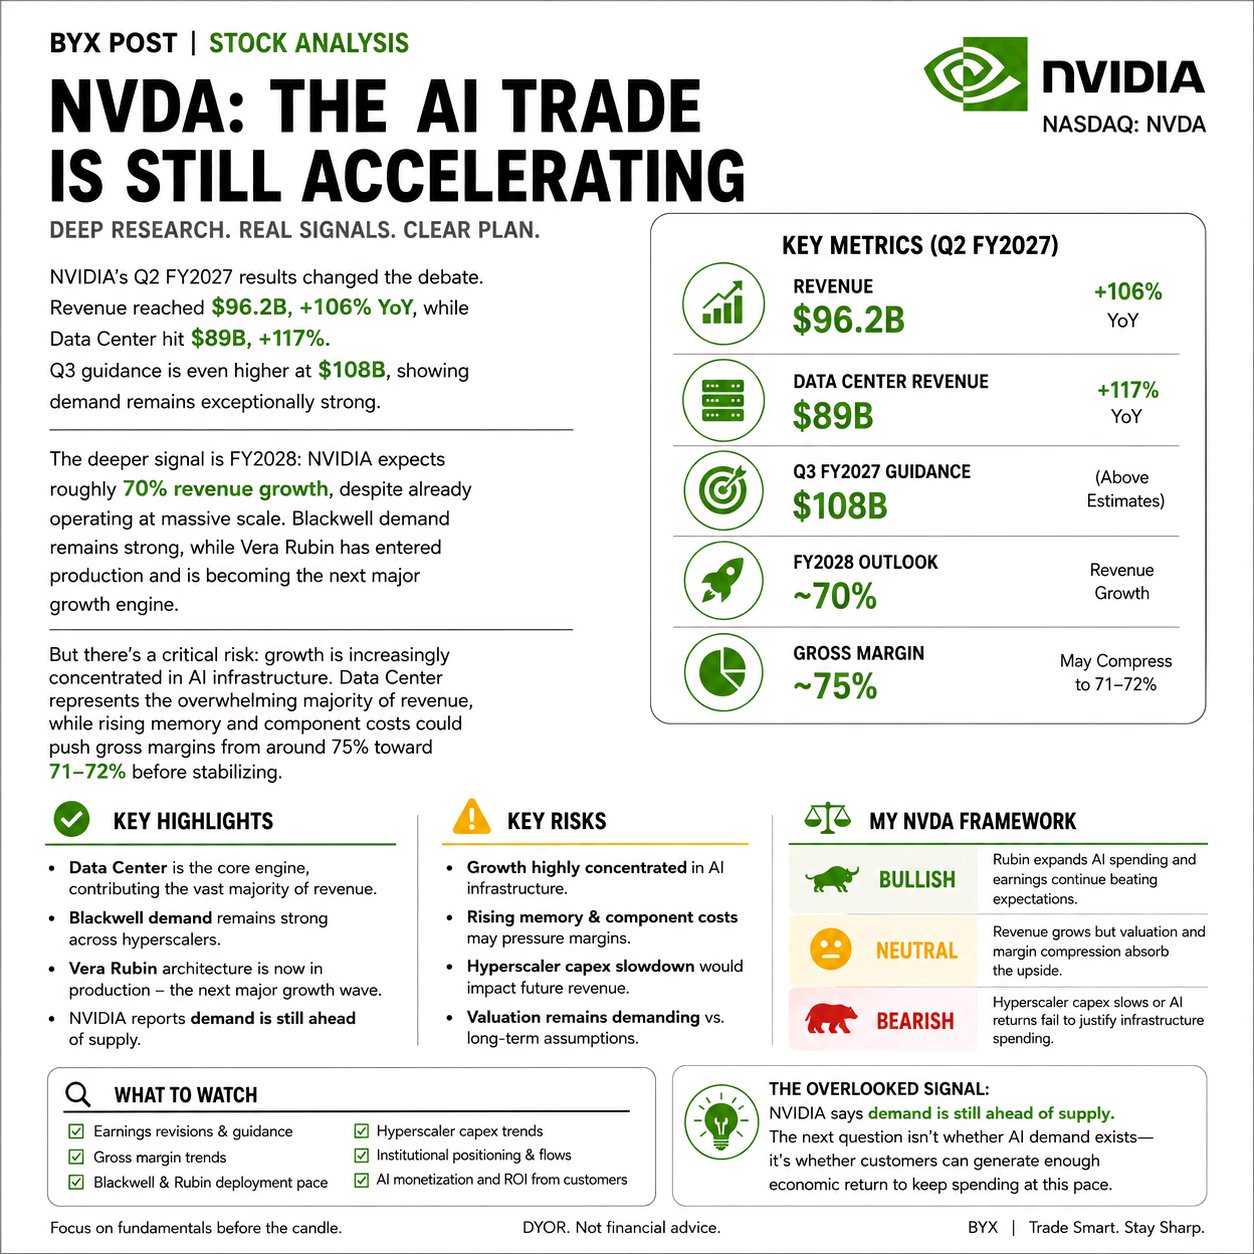
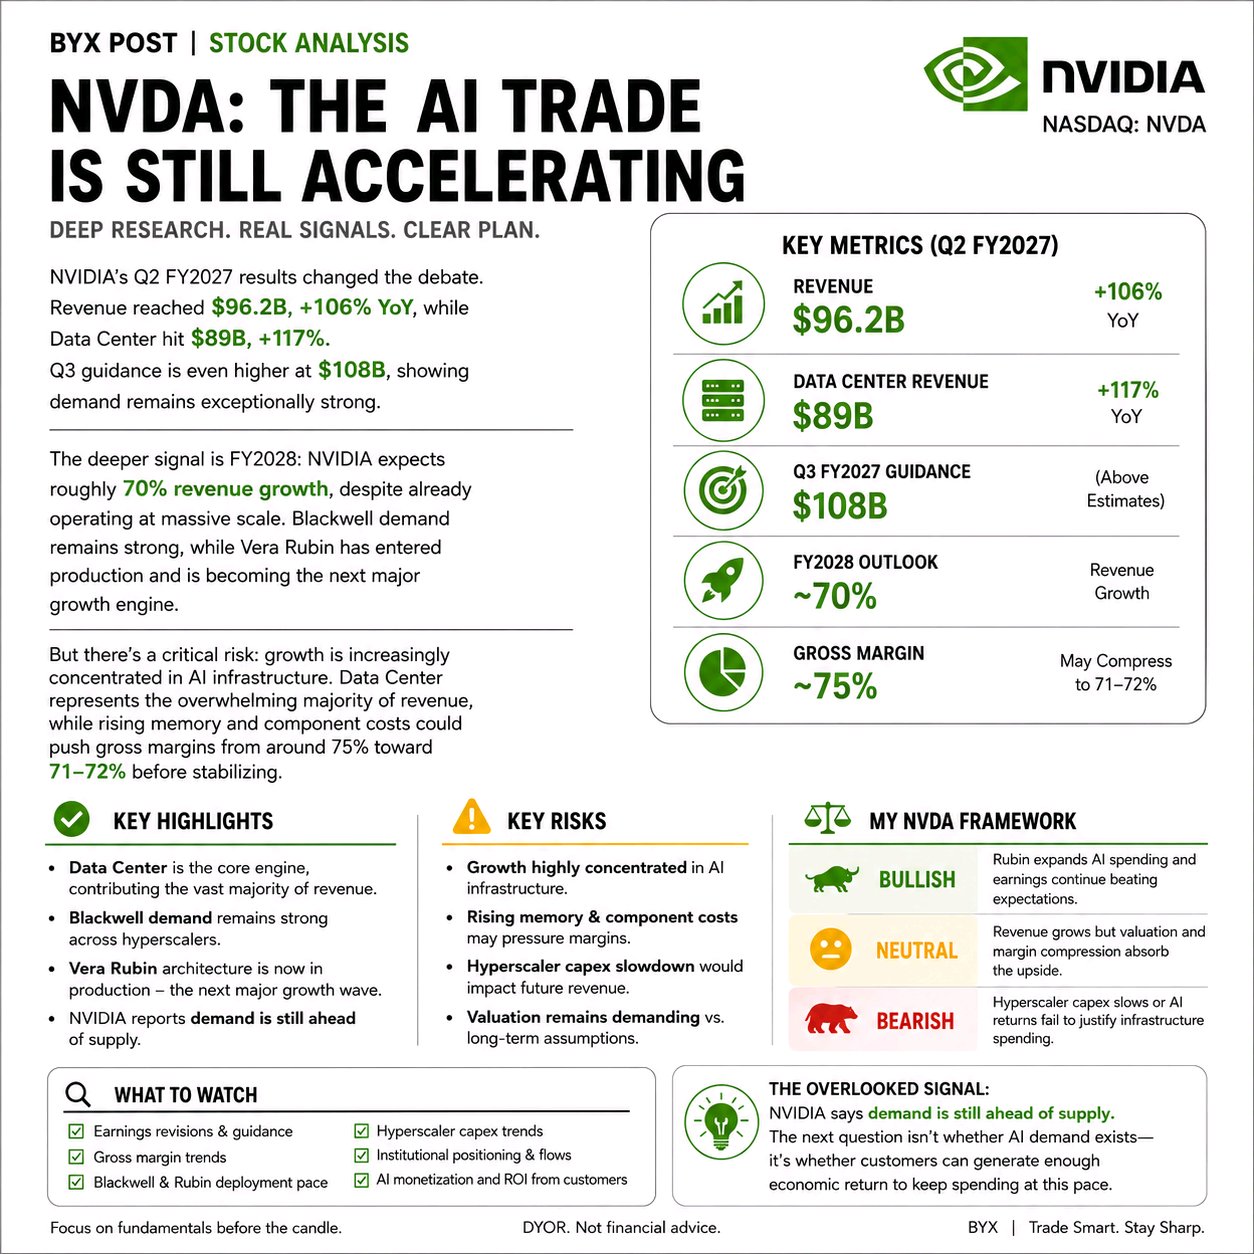
NVIDIA’s Q2 FY2027 results changed the debate. Revenue reached $96.2B, +106% YoY, while Data Center hit $89B, +117%. Q3 guidance is even higher at $108B, showing demand remains exceptionally strong. The deeper signal is FY2028: NVIDIA expects roughly 70% revenue growth, despite already operating at massive scale. Blackwell demand remains strong, while Vera Rubin has entered production and is becoming the next major growth engine. But there’s a critical risk: growth is increasingly concentrated in AI infrastructure. Data Center represents the overwhelming majority of revenue, while rising memory and component costs could push gross margins from around 75% toward 71–72% before stabilizing. My NVDA framework: Bullish if Rubin expands AI spending and earnings continue beating expectations. Neutral if revenue grows but valuation and margin compression absorb the upside. Bearish if hyperscaler capex slows or AI returns fail to justify infrastructure spending. The overlooked signal: NVIDIA says demand is still ahead of supply. The next question isn’t whether AI demand exists—it’s whether customers can generate enough economic return to keep spending at this pace. For BYX, I’d focus on earnings revisions, gross margins, Blackwell/Rubin deployment and institutional positioning rather than chasing daily price moves. Watch the fundamentals before the candle. DYOR. Not financial advice. $NVDAXUSDT #ByXIMPACT
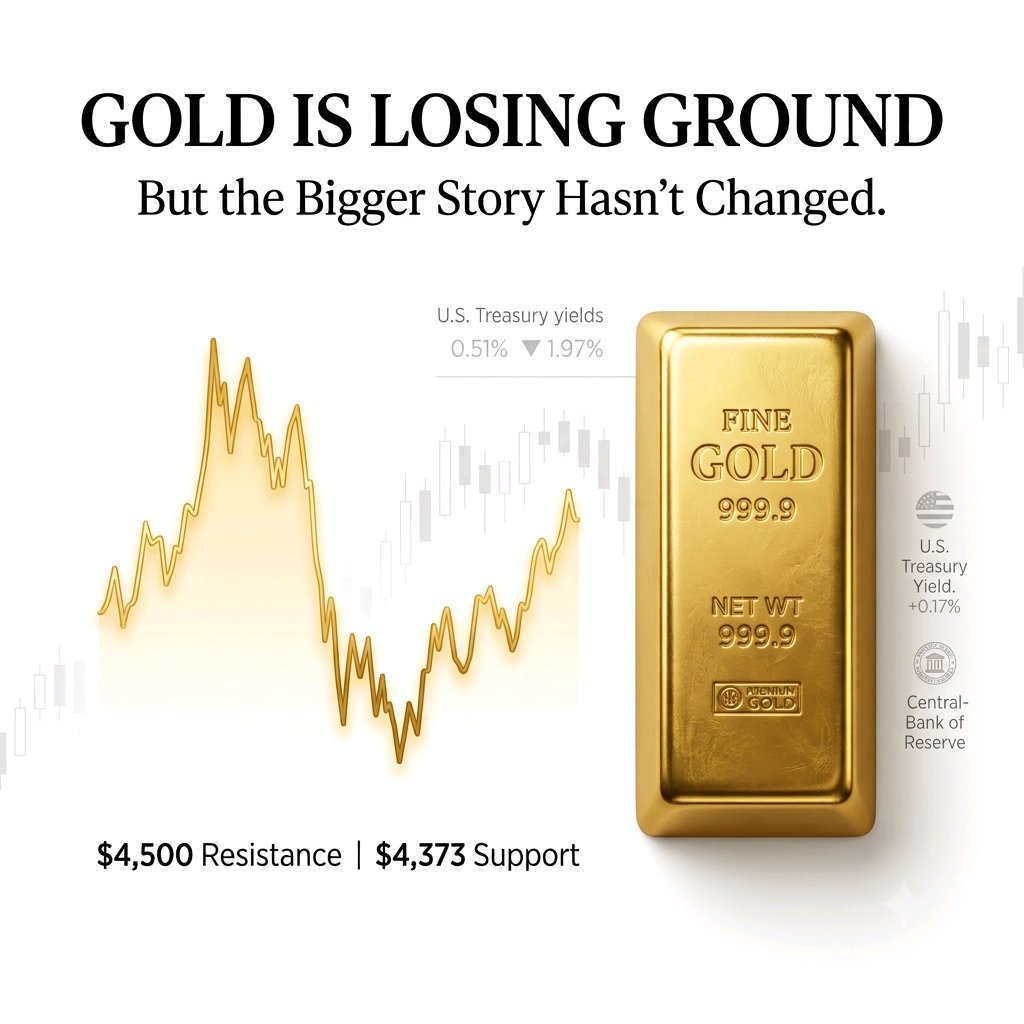
El oro está perdiendo terreno. Pero la historia más importante no ha cambiado. El oro retrocedió recientemente debido a que los datos económicos más sólidos de EE. UU. elevaron las expectativas de aumento de tasas, presionando a un activo sin rendimiento. Para $XAUTUSDT, la reacción importa. Un movimiento por debajo de $4,373 mostraría que los vendedores están ganando más control, mientras que recuperar los $4,500 pondría a los compradores en una posición más fuerte. Pero hay otro lado del mercado. Los bancos centrales continúan acumulando oro, y China ha extendido su racha de compras. Eso crea un conflicto entre la presión a corto plazo de la Reserva Federal y la demanda de reservas a largo plazo. Así que aún no estoy pendiente del objetivo de $5,000. Estoy observando si los compradores pueden absorber esta venta masiva sin perder la estructura de $4,373. Si la defienden, el retroceso podría convertirse en una oportunidad. Si la pierden, es posible que el mercado necesite ajustarse primero a la baja. $XAUTUSDT #ByXIMPACT
Apple: The Next Big Investment Test
Apple is entering its next iPhone cycle from a position of strength. Revenue reached $109.4B, up 16% year over year, while iPhone demand remained strong. But investors should look beyond the headline growth. Memory costs are rising as AI infrastructure competes for semiconductor capacity. Apple has already raised prices on some Macs and iPads, while management expects memory costs to remain a pressure point in the September quarter. Now the iPhone becomes the bigger test. Reports suggest memory costs for the iPhone 18 Pro could be significantly higher, creating another challenge for Apple's hardware margins. The investment question is simple: Can Apple pass higher costs to consumers without damaging iPhone demand? If the answer is yes, Apple demonstrates something more valuable than short-term revenue growth: pricing power. That could allow Apple to protect margins and earnings even as hardware costs rise. But if Apple absorbs too much of the increase to keep prices attractive, revenue could continue growing while margins come under pressure. My Apple takeaway: Don't watch the iPhone launch only for unit sales. Watch: ASP + gross margin + consumer demand. If Apple raises prices and customers keep upgrading, that would strengthen the case that its ecosystem still gives it exceptional pricing power. If higher prices weaken demand or margins deteriorate, investors may need to rethink future earnings growth. The bullish signal isn't simply “Apple sells more iPhones.” It's: “Apple can charge more without breaking demand.” $AAPLXUSDT #ByXIMPACT
Gold and Solana are both pushing higher, but the reasons behind the moves are very different. Spot gold climbed 1.2% to $4,390.11 as easing oil prices reduced some inflation pressure. SOL, meanwhile, jumped 11.5% on September 18, reaching $114.13 before holding above $113. That difference matters. Gold is reacting mainly to macro conditions: oil, inflation expectations, Treasury yields and Fed expectations. SOL is reacting more like a high-beta risk asset, with its rebound coming after a sharp move down toward $97 earlier in the week. So I'm watching whether both moves can hold after the initial reaction. Gold: $4,400 is the immediate test. Holding above $4,350 would keep the recovery structure intact, while renewed pressure from yields or oil could change the setup. SOL: $114 is the immediate resistance area. Holding above $110 would keep the recent breakout attempt constructive, while losing $100 would weaken the recovery. The interesting part isn't that Gold and SOL are both rising. It's whether their respective catalysts can keep supporting the moves after the first wave of buying fades. I'm watching: • Gold around $4,400 • SOL around $114 • U.S. Treasury yields • Crude oil prices • Fed expectations • Volume behind the rebounds Different assets. Different drivers. But both now need confirmation that buyers can hold the gains. $XAUTUSDT $SOLUSDT #ByXIMPACT
Tesla’s Q2 FY2026 results shifted the debate. Revenue reached $28.24B, +26% YoY, while vehicle deliveries hit a record 480,126, +25%. Energy storage deployments reached 13.5 GWh, while active FSD subscriptions climbed 56% YoY to 1.48M. The deeper signal is Tesla’s transition beyond vehicles. Robotaxi is expanding across U.S. metros, Cybercab has entered production, and Optimus production infrastructure is being built. At the same time, Tesla is investing heavily in AI compute, batteries, semiconductors and new manufacturing capacity. But there’s a critical risk: growth is becoming more capital-intensive before the newer AI businesses generate meaningful financial returns. Q2 operating margin fell to 1.4%, while free cash flow turned -$1.1B as capex surged to $5.79B. R&D also increased 49% YoY. My TSLA framework: Bullish if Robotaxi, FSD and energy scale faster than Tesla’s investment burden. Neutral if revenue keeps growing but margin compression and elevated capex absorb the upside. Bearish if automotive demand weakens while AI, robotics and autonomy require sustained spending without comparable revenue growth. The overlooked signal: Tesla’s biggest constraint may no longer be vehicle demand alone—it’s converting its AI infrastructure investment into recurring, high-margin revenue. The company says battery-pack capacity is currently limiting near-term vehicle production, while its AI and manufacturing expansion is pushing capital requirements higher. For BYX, I’d focus on deliveries, automotive margins, FSD subscriptions, Robotaxi expansion, energy deployments and free cash flow rather than chasing daily price moves. Watch the cash conversion before the narrative. DYOR. Not financial advice. $TSLAXUSDT #ByXIMPACT
Gold & Circle: Risk Is Being Repriced
Gold has been under pressure as rising oil prices, inflation concerns and higher Treasury yields push rate-hike expectations higher. Spot gold recently fell to $4,293.29, while the 10-year Treasury yield moved above 5%. But the interesting part isn't the gold decline itself. It's how investors are repricing risk across different parts of the market. Circle ($CRCL) has also faced heavy selling pressure, with the stock recently trading around $86.30. Crypto-linked equities remain sensitive to changes in risk appetite, making CRCL another useful asset to watch alongside broader market conditions. That creates three possible outcomes: Bull case: Treasury yields ease → inflation pressure cools → Gold stabilizes → risk appetite improves → CRCL finds buyers. Base case: Yields remain elevated → Gold consolidates → investors stay cautious → CRCL remains volatile. Bear case: Inflation pressure persists → yields rise further → Gold faces more pressure → risk appetite weakens → CRCL remains under selling pressure. Market takeaway Gold is showing how macro pressure is being priced into defensive assets, while CRCL shows how the same risk-off environment can affect crypto-linked equities. I'm watching: • Gold around $4,293 • U.S. 10Y yield near 5% • Oil and inflation expectations • CRCL around $86 • Fed policy signals The key isn't whether one asset moves higher or lower. It's whether yields and liquidity start confirming a broader shift in risk appetite. #ByXIMPACT $XAUTUSDT $CRCLXUSDT
NVIDIA’s Q2 FY2027 results changed the debate. Revenue reached $96.2B, +106% YoY, while Data Center hit $89B, +117%. Q3 guidance is even higher at $108B, showing demand remains exceptionally strong. The deeper signal is FY2028: NVIDIA expects roughly 70% revenue growth, despite already operating at massive scale. Blackwell demand remains strong, while Vera Rubin has entered production and is becoming the next major growth engine. But there’s a critical risk: growth is increasingly concentrated in AI infrastructure. Data Center represents the overwhelming majority of revenue, while rising memory and component costs could push gross margins from around 75% toward 71–72% before stabilizing. My NVDA framework: Bullish if Rubin expands AI spending and earnings continue beating expectations. Neutral if revenue grows but valuation and margin compression absorb the upside. Bearish if hyperscaler capex slows or AI returns fail to justify infrastructure spending. The overlooked signal: NVIDIA says demand is still ahead of supply. The next question isn’t whether AI demand exists—it’s whether customers can generate enough economic return to keep spending at this pace. For BYX, I’d focus on earnings revisions, gross margins, Blackwell/Rubin deployment and institutional positioning rather than chasing daily price moves. Watch the fundamentals before the candle. DYOR. Not financial advice. $NVDAXUSDT #ByXIMPACT
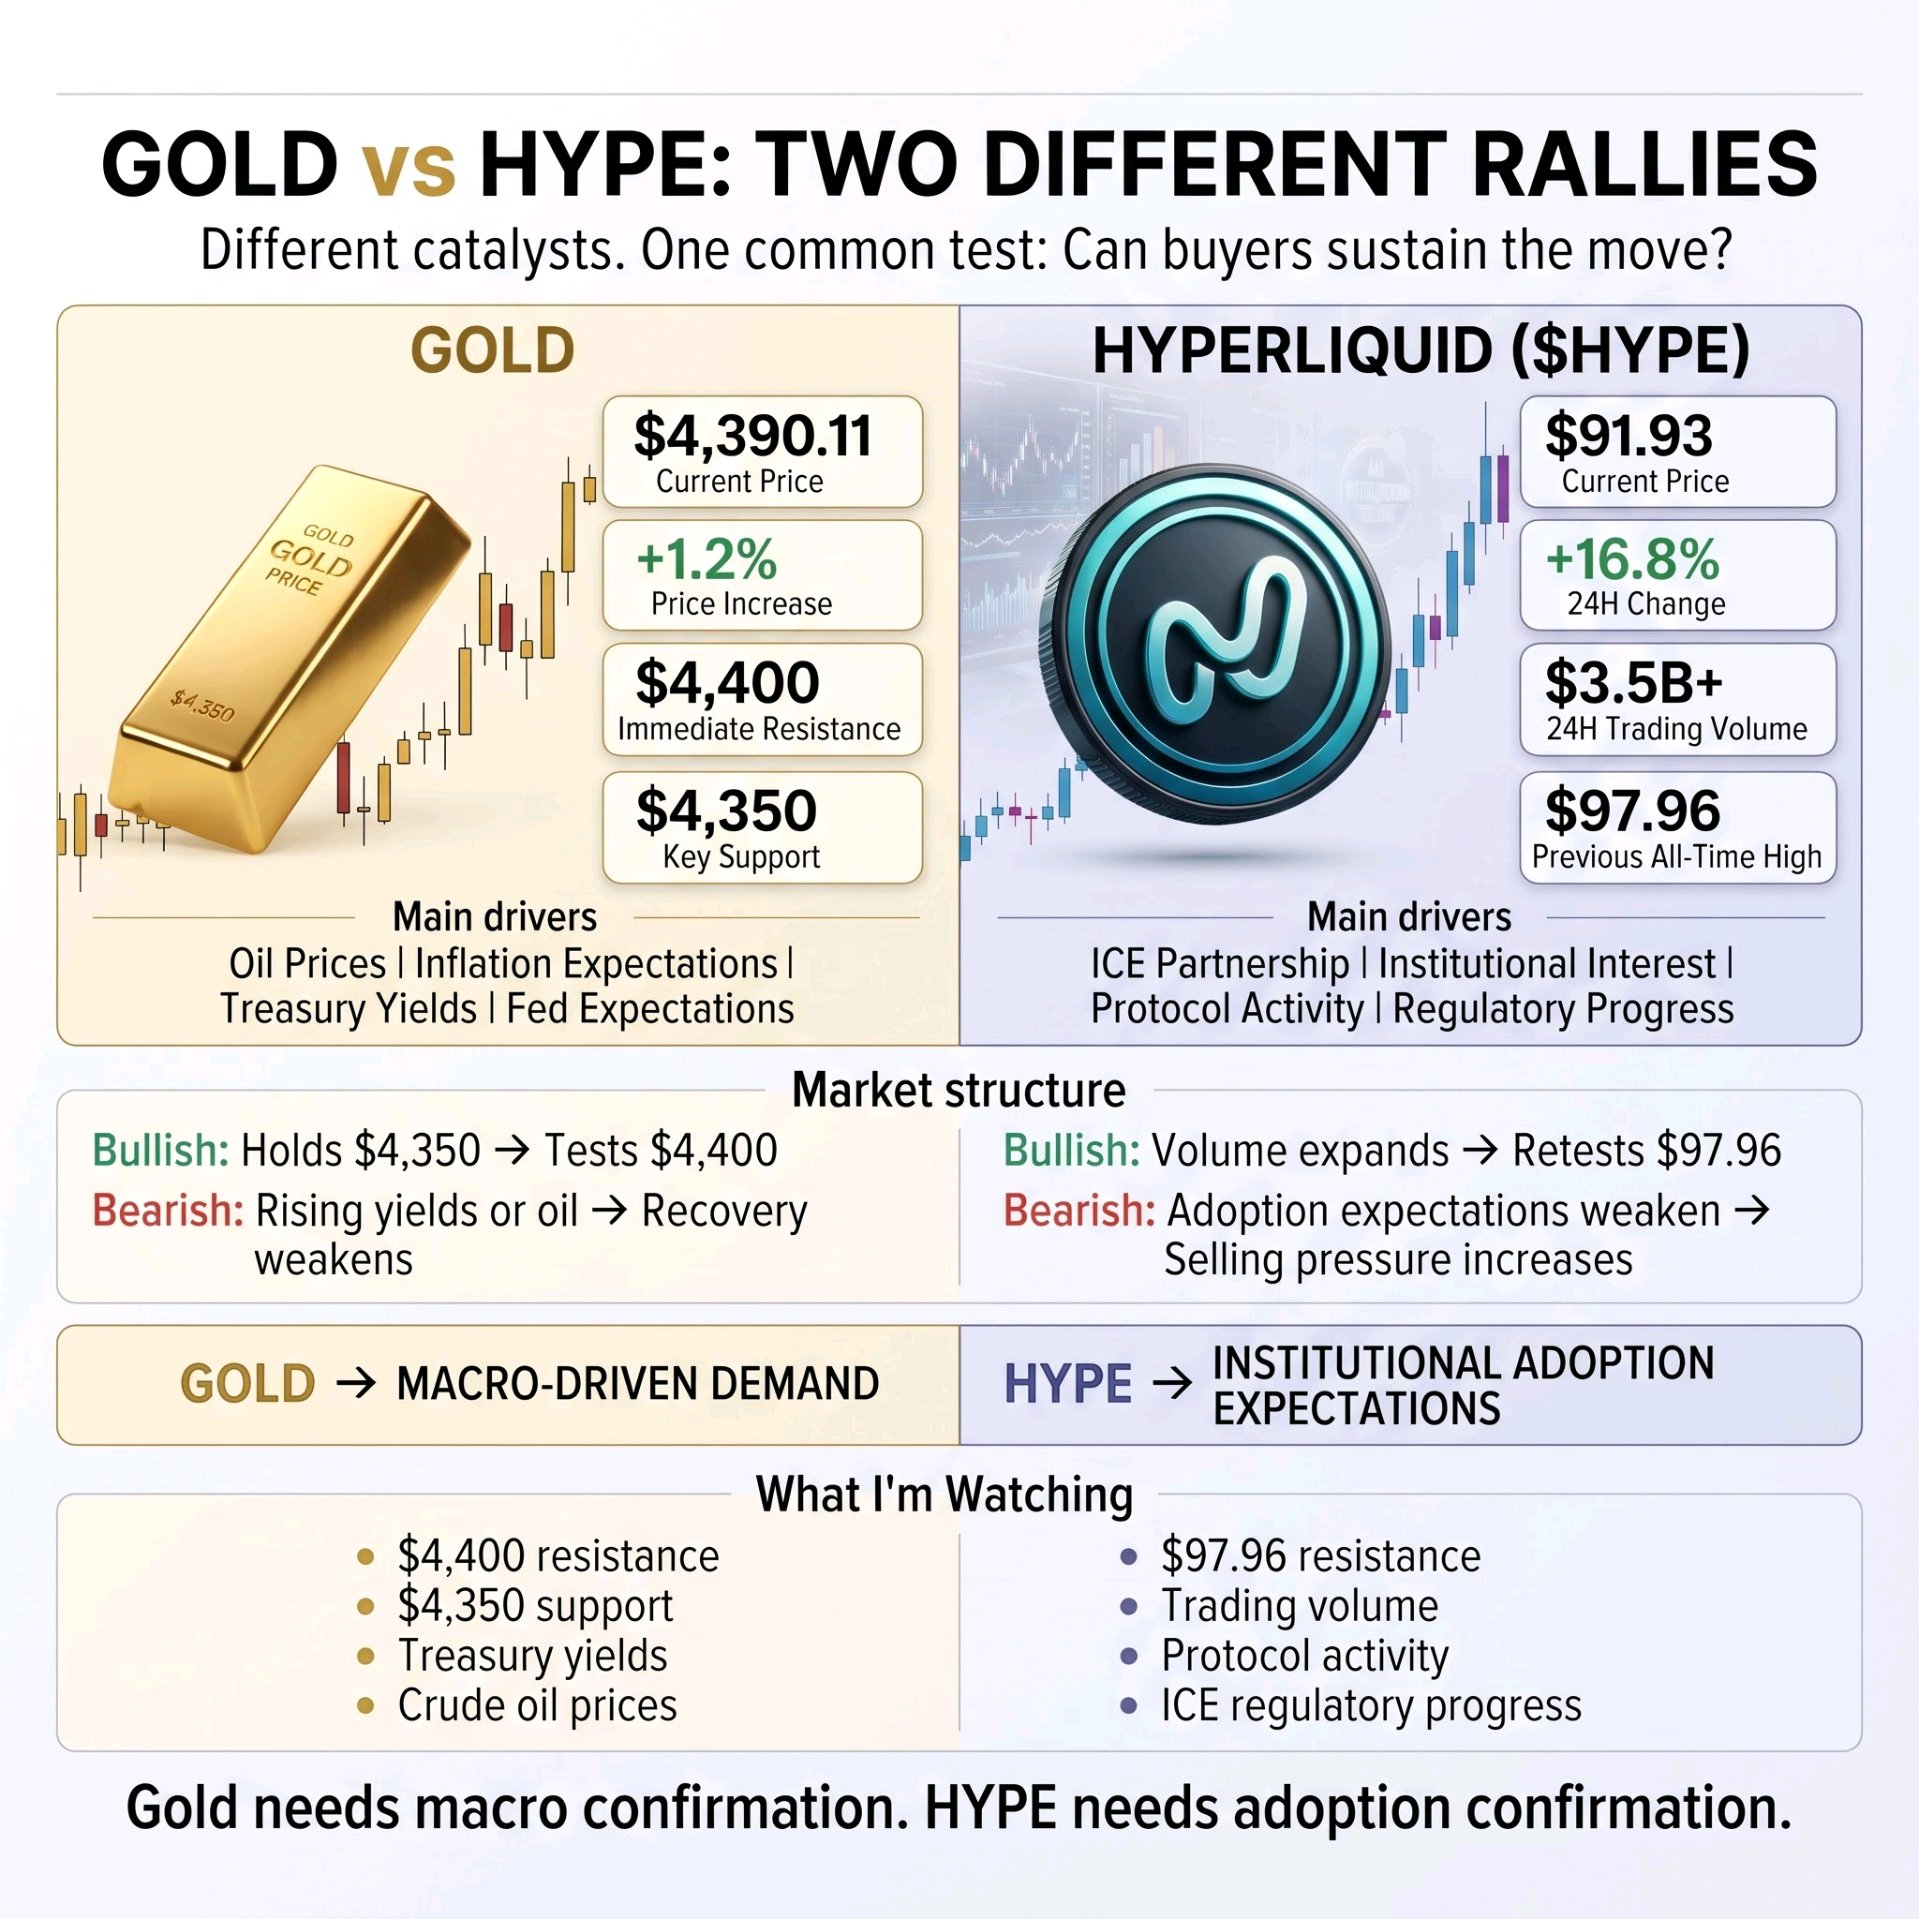
Gold and Hyperliquid's $HYPE are both attracting buyers, but the reasons behind their moves are very different. Spot gold climbed to $4,390.11, gaining 1.2% as easing oil prices reduced some inflation pressure. HYPE, meanwhile, jumped approximately 16.8% to $91.93, with daily trading volume exceeding $3.5B following the announcement involving ICE and Trade[XYZ]. That difference matters. Gold is reacting mainly to macro conditions: oil prices, inflation expectations, Treasury yields and Fed policy. HYPE is reacting to growing expectations around institutional adoption, following plans to introduce Hyperliquid-based perpetual futures through a regulated trading and clearing structure, subject to regulatory approval. So I'm watching whether both moves can hold after the initial reaction. Gold: $4,400 is the immediate test. Holding above $4,350 would keep the recovery structure intact, while renewed pressure from yields or oil could weaken the move. HYPE: $97.96 is the key resistance area and previous all-time high. Sustained buying volume could support another attempt, while regulatory delays or declining protocol activity could weaken the rally. The interesting part isn't that Gold and HYPE are both rising. It's whether their respective catalysts can continue supporting demand after the first wave of buying fades. I'm watching: • Gold around $4,400 • Gold support around $4,350 • HYPE around $97.96 • U.S. Treasury yields and crude oil • Regulatory progress around the ICE partnership • Volume and protocol activity behind HYPE Different assets. Different drivers. But both now need confirmation that buyers can sustain the move. $XAUTUSDT $HYPEUSDT #ByXIMPACT
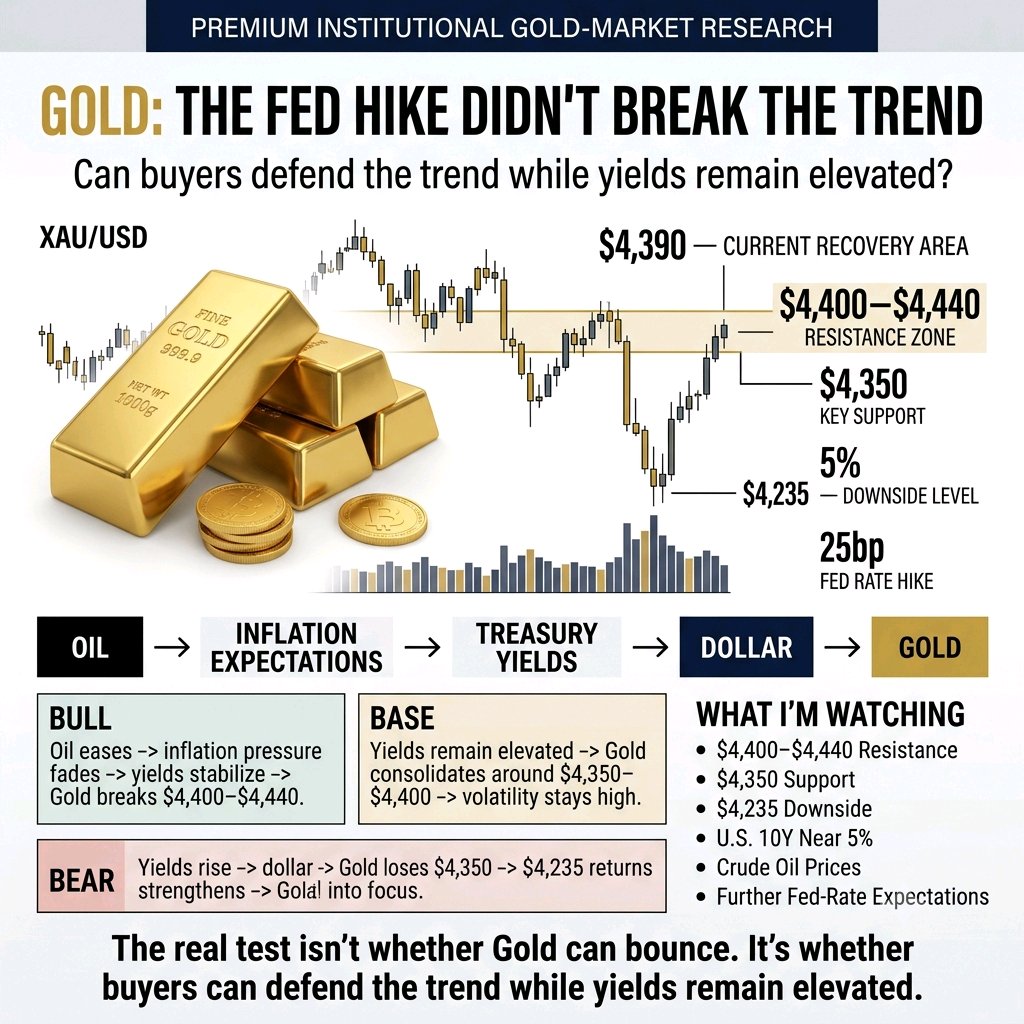
Oro: La subida de la Fed no logra romper la tendencia
El oro se ha recuperado notablemente tras la última subida de tipos de la Fed, y lo interesante no es el rebote en sí. Es lo que ocurrió detrás. El oro al contado volvió a empujar hacia los 4,400 dólares tras caer a cerca de 4,235 dólares después de la subida de 25 puntos básicos de la Fed. A medida que los precios del petróleo bajaron y los rendimientos de los bonos del Tesoro retrocedieron, parte de la presión sobre el oro comenzó a disiparse. Esa reacción es importante. Unos tipos más altos normalmente ejercen presión sobre el oro porque este activo no genera rendimiento. Pero esta vez, el mercado está demostrando que el petróleo, las expectativas de inflación, los rendimientos y el riesgo geopolítico están compitiendo por influir. Eso crea tres posibles caminos: Escenario alcista: El petróleo sigue enfriándose → los rendimientos del Tesoro disminuyen → la presión inflacionaria se desvanece → El oro se mantiene por encima de los 4,350 dólares y vuelve a probar los 4,400+ dólares. Escenario base: Los rendimientos se mantienen elevados → El oro se consolida alrededor de los 4,350–4,400 dólares → la volatilidad se mantiene alta mientras los mercados reevalúan el próximo movimiento de la Fed. Escenario bajista: El petróleo rebota → las expectativas de inflación aumentan → los rendimientos vuelven hacia el 5% → El oro pierde los 4,350 dólares y enfrenta una renovada presión vendedora. Conclusión del mercado La subida de la Fed no rompió la estructura del oro. La prueba más importante es si los precios más bajos del petróleo y la relajación de los rendimientos pueden seguir respaldando el rebote. Estoy observando: • Resistencia de 4,400 dólares • Zona de reacción de 4,350 dólares • Rendimiento del Tesoro estadounidense a 10 años • Precios del petróleo crudo • Expectativas de nuevas subidas de la Fed El oro ya no cotiza solo basándose en los tipos. El próximo movimiento podría depender de si la presión inflacionaria sigue disminuyendo o si regresa a través de los precios de la energía. #ByXIMPACT $XAUTUSDT
Gold and Solana are both pushing higher, but the reasons behind the moves are very different. Spot gold climbed 1.2% to $4,390.11 as easing oil prices reduced some inflation pressure. SOL, meanwhile, jumped 11.5% on September 18, reaching $114.13 before holding above $113. That difference matters. Gold is reacting mainly to macro conditions: oil, inflation expectations, Treasury yields and Fed expectations. SOL is reacting more like a high-beta risk asset, with its rebound coming after a sharp move down toward $97 earlier in the week. So I'm watching whether both moves can hold after the initial reaction. Gold: $4,400 is the immediate test. Holding above $4,350 would keep the recovery structure intact, while renewed pressure from yields or oil could change the setup. SOL: $114 is the immediate resistance area. Holding above $110 would keep the recent breakout attempt constructive, while losing $100 would weaken the recovery. The interesting part isn't that Gold and SOL are both rising. It's whether their respective catalysts can keep supporting the moves after the first wave of buying fades. I'm watching: • Gold around $4,400 • SOL around $114 • U.S. Treasury yields • Crude oil prices • Fed expectations • Volume behind the rebounds Different assets. Different drivers. But both now need confirmation that buyers can hold the gains. $XAUTUSDT #ByXIMPACT $SOLUSDT
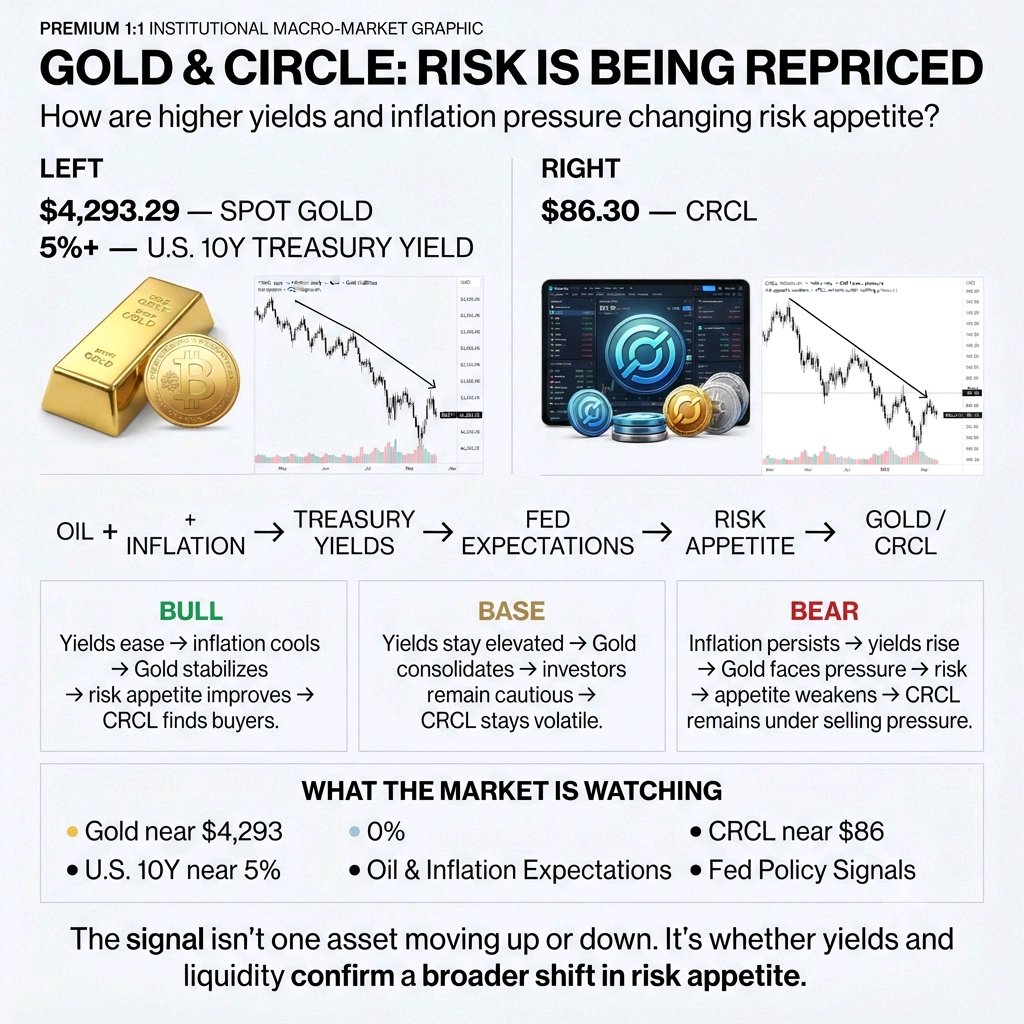
Gold & Circle: Risk Is Being Repriced
Gold has been under pressure as rising oil prices, inflation concerns and higher Treasury yields push rate-hike expectations higher. Spot gold recently fell to $4,293.29, while the 10-year Treasury yield moved above 5%. But the interesting part isn't the gold decline itself. It's how investors are repricing risk across different parts of the market. Circle ($CRCL) has also faced heavy selling pressure, with the stock recently trading around $86.30. Crypto-linked equities remain sensitive to changes in risk appetite, making CRCL another useful asset to watch alongside broader market conditions. That creates three possible outcomes: Bull case: Treasury yields ease → inflation pressure cools → Gold stabilizes → risk appetite improves → CRCL finds buyers. Base case: Yields remain elevated → Gold consolidates → investors stay cautious → CRCL remains volatile. Bear case: Inflation pressure persists → yields rise further → Gold faces more pressure → risk appetite weakens → CRCL remains under selling pressure. Market takeaway Gold is showing how macro pressure is being priced into defensive assets, while CRCL shows how the same risk-off environment can affect crypto-linked equities. I'm watching: • Gold around $4,293 • U.S. 10Y yield near 5% • Oil and inflation expectations • CRCL around $86 • Fed policy signals The key isn't whether one asset moves higher or lower. It's whether yields and liquidity start confirming a broader shift in risk appetite. #ByXIMPACT $XAUTUSDT $CRCLXUSDT
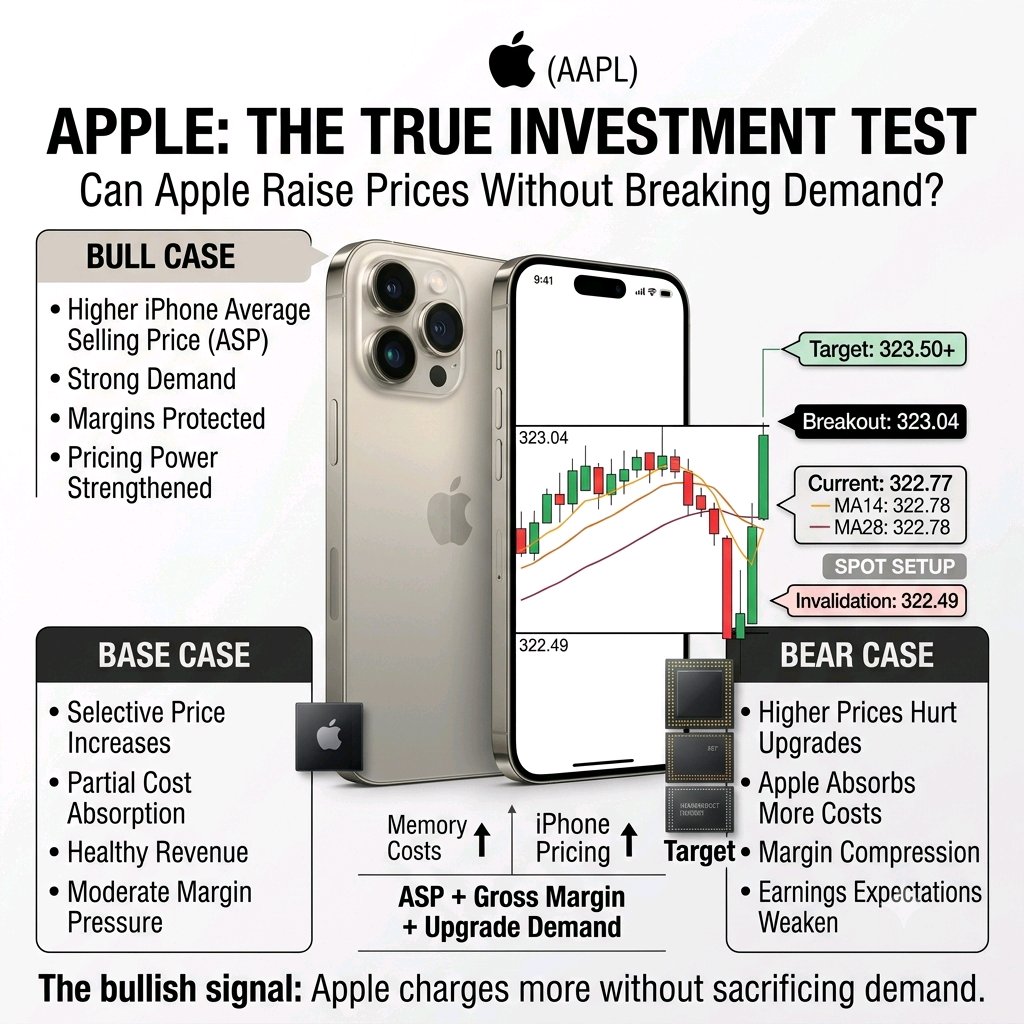
Apple: The Next Big Investment Test
Apple is entering its next iPhone cycle from a position of strength. Revenue reached $109.4B, up 16% year over year, while iPhone demand remained strong. But investors should look beyond the headline growth. Memory costs are rising as AI infrastructure competes for semiconductor capacity. Apple has already raised prices on some Macs and iPads, while management expects memory costs to remain a pressure point in the September quarter. Now the iPhone becomes the bigger test. Reports suggest memory costs for the iPhone 18 Pro could be significantly higher, creating another challenge for Apple's hardware margins. The investment question is simple: Can Apple pass higher costs to consumers without damaging iPhone demand? If the answer is yes, Apple demonstrates something more valuable than short-term revenue growth: pricing power. That could allow Apple to protect margins and earnings even as hardware costs rise. But if Apple absorbs too much of the increase to keep prices attractive, revenue could continue growing while margins come under pressure. My Apple takeaway: Don't watch the iPhone launch only for unit sales. Watch: ASP + gross margin + consumer demand. If Apple raises prices and customers keep upgrading, that would strengthen the case that its ecosystem still gives it exceptional pricing power. If higher prices weaken demand or margins deteriorate, investors may need to rethink future earnings growth. The bullish signal isn't simply “Apple sells more iPhones.” It's: “Apple can charge more without breaking demand.” $AAPLXUSDT #ByXIMPACT
NVIDIA’s Q2 FY2027 results changed the debate. Revenue reached $96.2B, +106% YoY, while Data Center hit $89B, +117%. Q3 guidance is even higher at $108B, showing demand remains exceptionally strong. The deeper signal is FY2028: NVIDIA expects roughly 70% revenue growth, despite already operating at massive scale. Blackwell demand remains strong, while Vera Rubin has entered production and is becoming the next major growth engine. But there’s a critical risk: growth is increasingly concentrated in AI infrastructure. Data Center represents the overwhelming majority of revenue, while rising memory and component costs could push gross margins from around 75% toward 71–72% before stabilizing. My NVDA framework: Bullish if Rubin expands AI spending and earnings continue beating expectations. Neutral if revenue grows but valuation and margin compression absorb the upside. Bearish if hyperscaler capex slows or AI returns fail to justify infrastructure spending. The overlooked signal: NVIDIA says demand is still ahead of supply. The next question isn’t whether AI demand exists—it’s whether customers can generate enough economic return to keep spending at this pace. For BYX, I’d focus on earnings revisions, gross margins, Blackwell/Rubin deployment and institutional positioning rather than chasing daily price moves. Watch the fundamentals before the candle. DYOR. Not financial advice. #ByXIMPACT $NVDAXUSDT
Los resultados del segundo trimestre del año fiscal 2026 de Tesla cambiaron el debate. Los ingresos alcanzaron los 28.24 mil millones de dólares, un aumento interanual del 26%, mientras que las entregas de vehículos alcanzaron un récord de 480,126 unidades, un +25%. El almacenamiento de energía alcanzó los 13.5 GWh, mientras que las suscripciones activas de FSD subieron un 56% interanual hasta los 1.48 millones. La señal más profunda es la transición de Tesla más allá de los vehículos. Robotaxi se está expandiendo por las áreas metropolitanas de EE. UU., Cybercab ha entrado en producción y se está construyendo la infraestructura de producción de Optimus. Al mismo tiempo, Tesla está invirtiendo fuertemente en cómputo de IA, baterías, semiconductores y nueva capacidad de fabricación. Pero hay un riesgo crítico: el crecimiento se está volviendo más intensivo en capital antes de que los nuevos negocios de IA generen retornos financieros significativos. El margen operativo del segundo trimestre cayó al 1.4%, mientras que el flujo de caja libre pasó a -1.1 mil millones de dólares, ya que el gasto de capital (capex) aumentó a 5.79 mil millones. La I+D también aumentó un 49% interanual. Mi marco de trabajo para TSLA: Alcista si Robotaxi, FSD y la energía escalan más rápido que la carga de inversión de Tesla. Neutral si los ingresos siguen creciendo, pero la compresión de márgenes y el elevado capex absorben el alza. Bajista si la demanda automotriz se debilita mientras que la IA, la robótica y la autonomía requieren un gasto sostenido sin un crecimiento comparable de los ingresos. La señal pasada por alto: la mayor limitación de Tesla puede que ya no sea solo la demanda de vehículos, sino convertir su inversión en infraestructura de IA en ingresos recurrentes y de alto margen. La empresa dice que la capacidad de los paquetes de baterías está limitando actualmente la producción de vehículos a corto plazo, mientras que su expansión de IA y fabricación está elevando los requisitos de capital. Para BYX, me centraría en las entregas, los márgenes automotrices, las suscripciones de FSD, la expansión de Robotaxi, los despliegues de energía y el flujo de caja libre en lugar de perseguir los movimientos diarios de los precios. Observa la conversión de efectivo antes que la narrativa. DYOR (haz tu propia investigación). No es un consejo financiero. #ByXIMPACT $TSLAXUSDT