K
KobeissiLetter
699点赞0分享5粉丝0关注
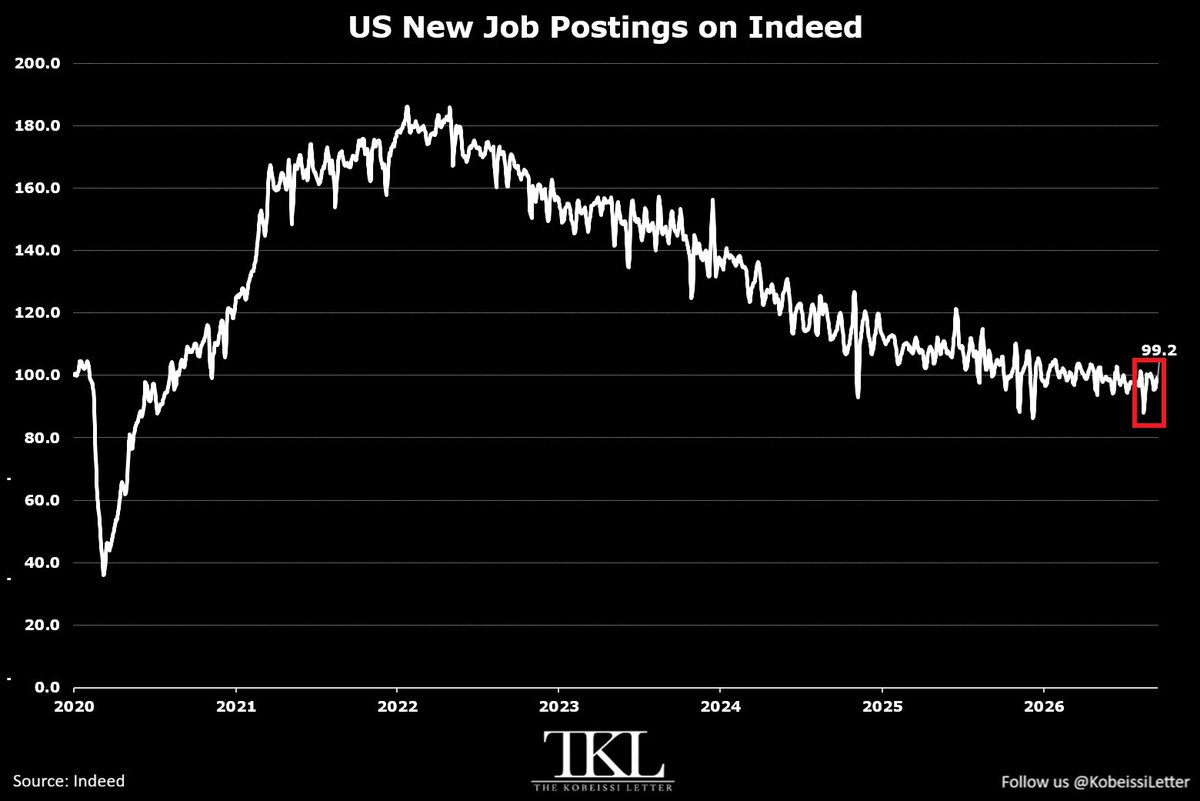
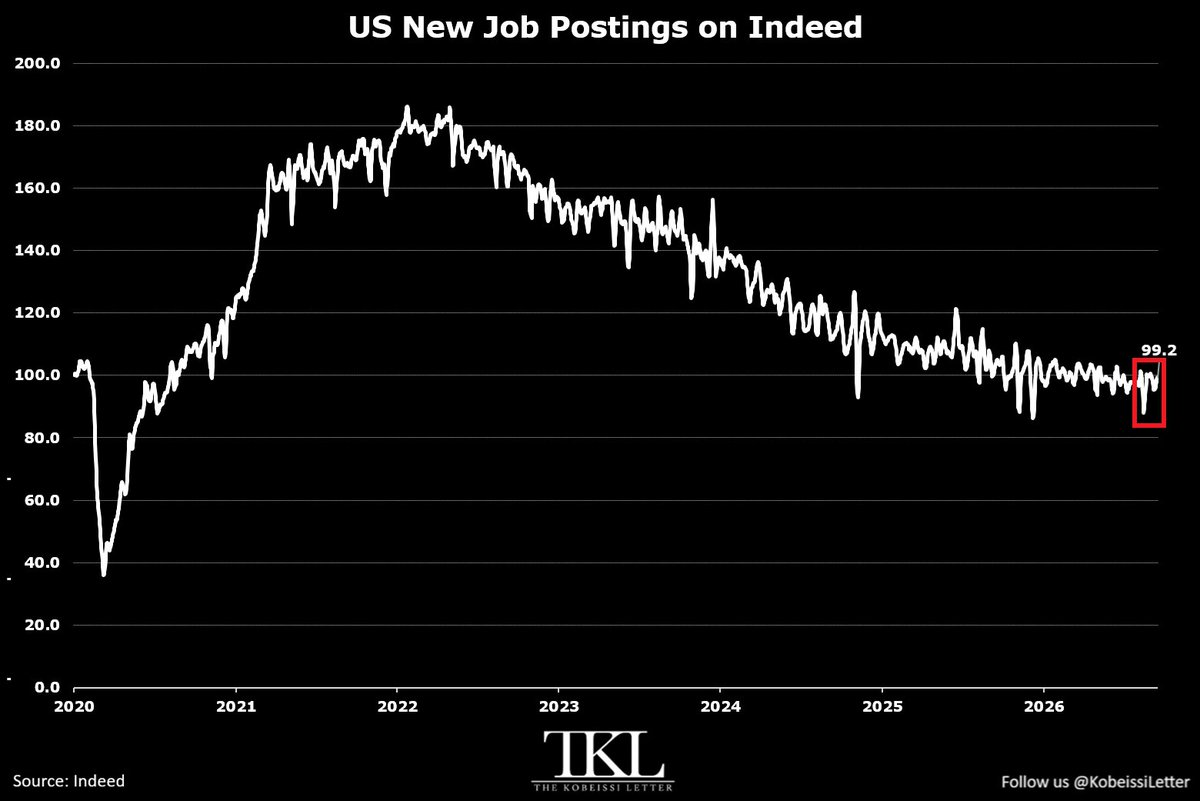
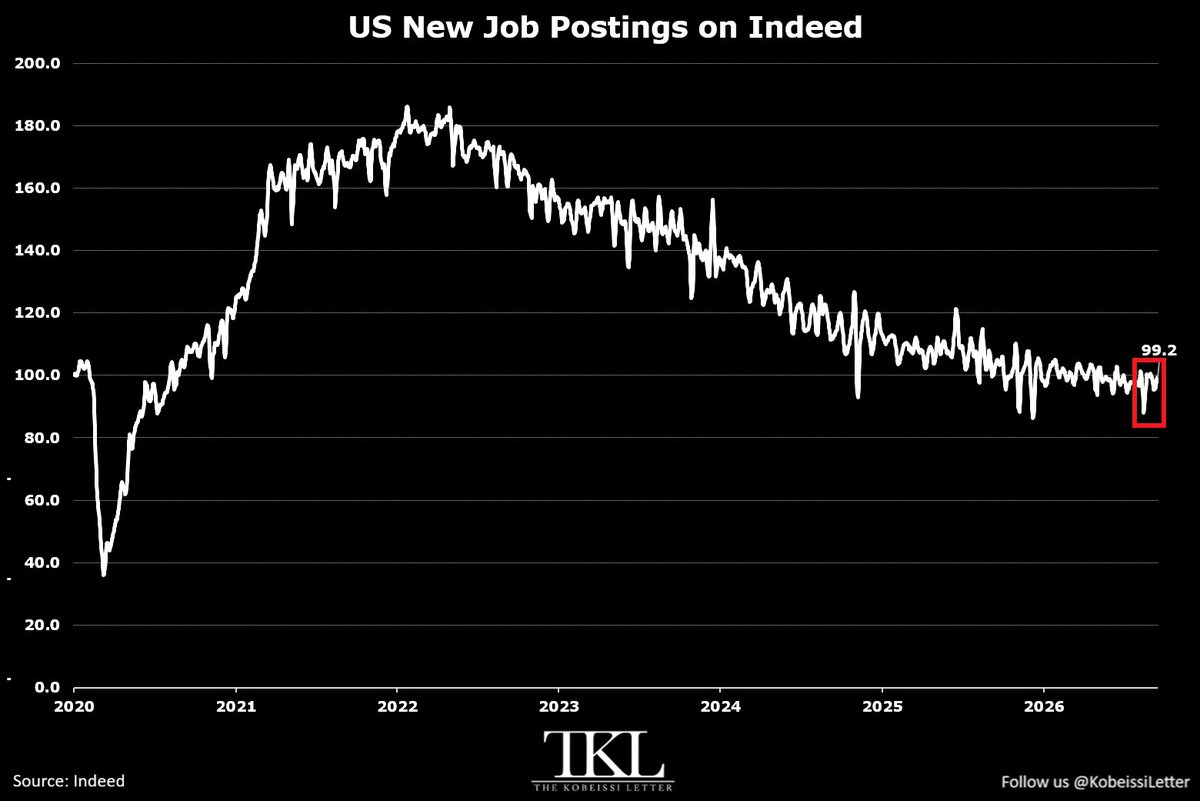
美国的招聘市场仍未出现真正的复苏迹象。 截至10月16日的一周,Indeed平台上的新发布职位数同比下降了4.8%。 自2022年4月以来,职位发布总量已累计下滑46.7%。 这一跌幅已导致新招聘岗位数量降至疫情前(2020年2月)水平的0.8%以下。 虽然近几个月下滑速度有所放缓,但并未出现回升——招聘势头依然处于停滞状态。 这也预示着美国劳工统计局(BLS)的官方职位空缺数据在短期内难有明显改善,因为这些数据通常会比招聘平台的数据滞后几周。 总而言之:撇开宏观数字不谈,美国劳动力市场依然疲软。
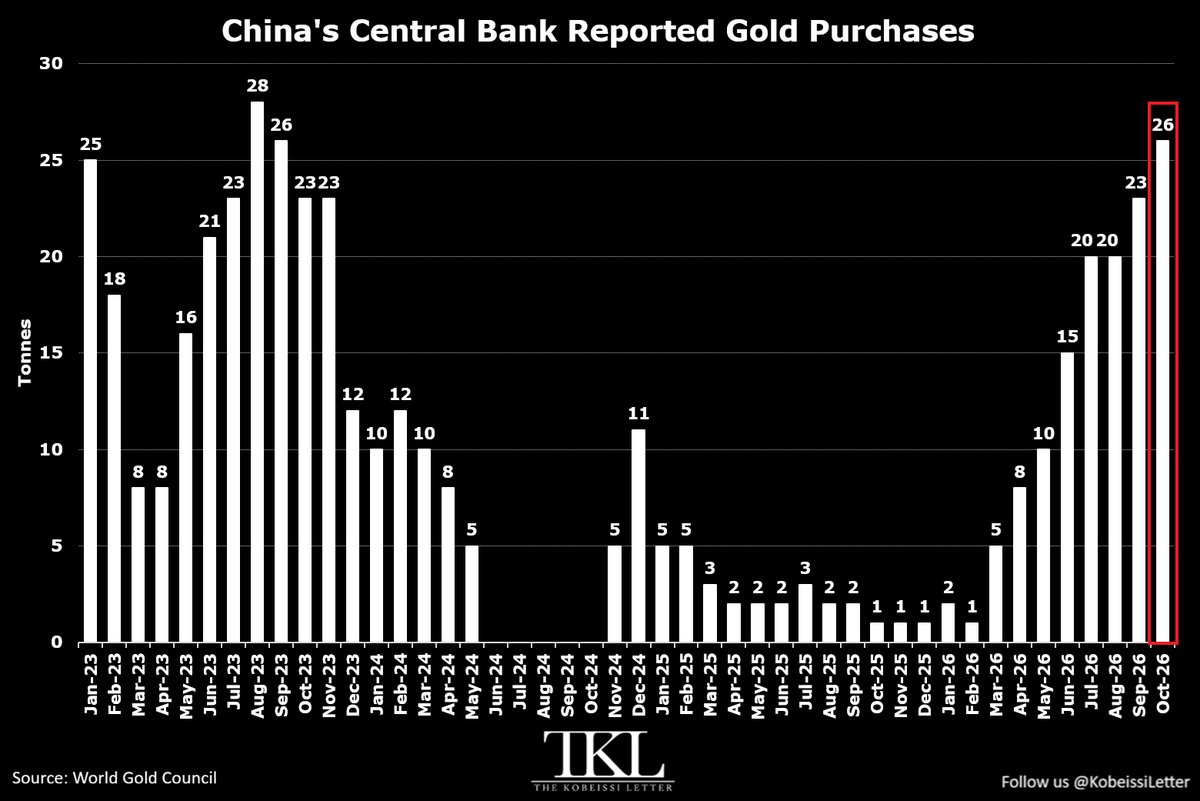
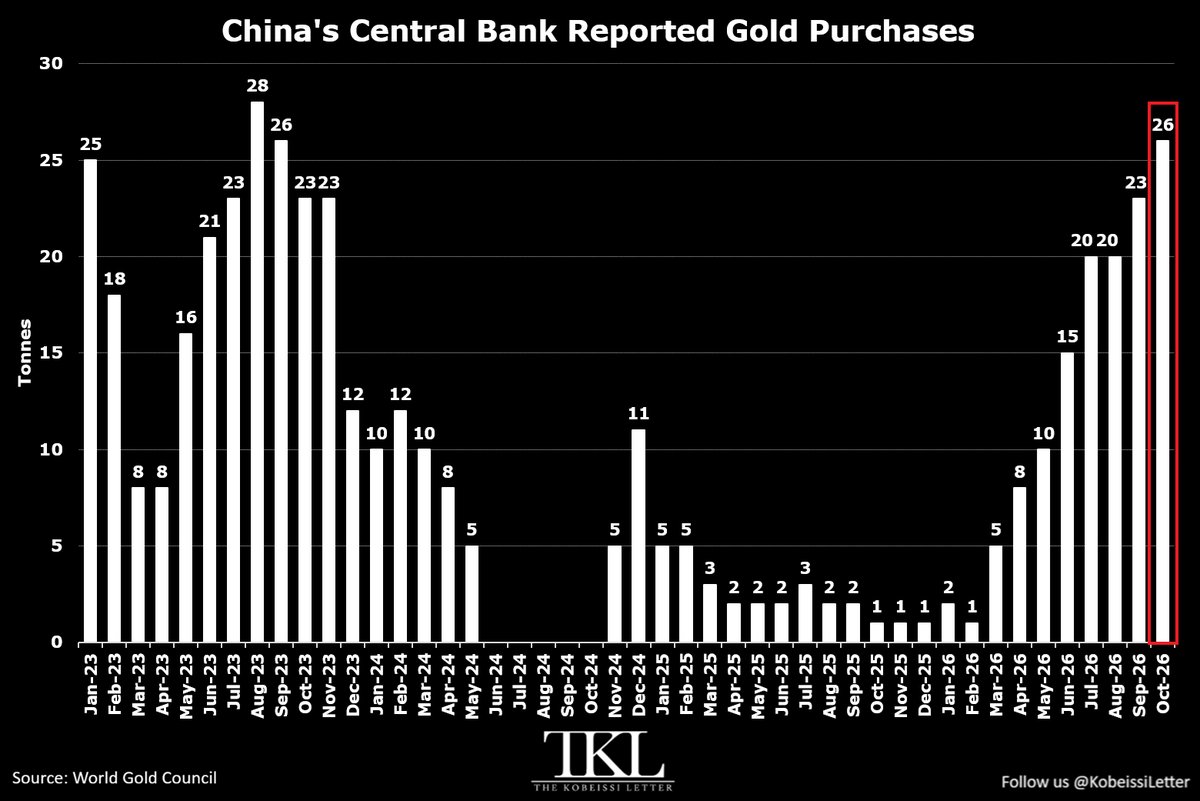
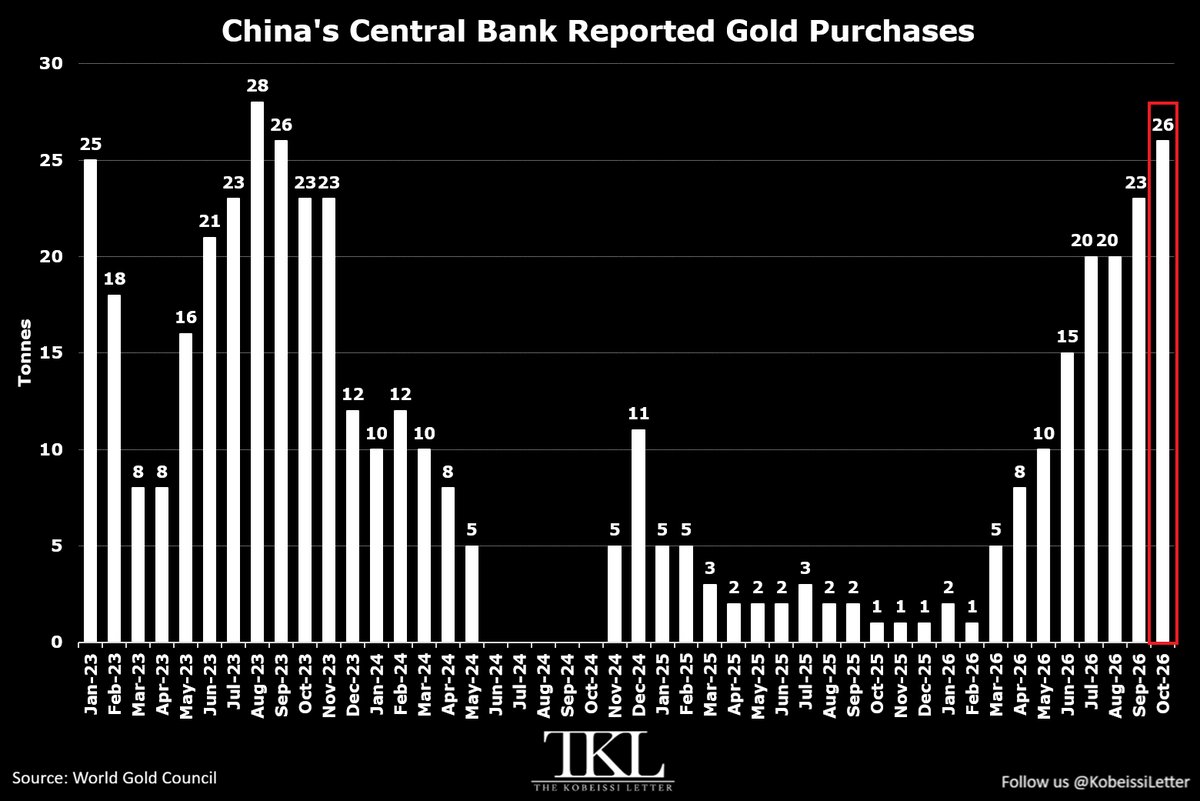
突发:中国央行在10月份增持了超过26吨黄金——这是自2023年8月以来的最大单月增持量。 在此之前,9月份也增持了超过23吨,这使得中国央行连续净买入黄金的时间延长至24个月。 作为对比:在整个2025年期间,中国单月的增持量从未超过5吨。 今年迄今为止,官方累计购买量已达129吨以上,将储备推升至2,435吨的新高。 这使得中国距离全球第四大黄金持有国法国仅差2吨。 而且,中国对黄金的需求似乎远未降温。
美国的招聘情况仍未显示出任何真正好转的迹象。 截至 10 月 16 日当周,Indeed 上的新招聘启事同比下降了 4.8%。 自 2022 年 4 月以来,招聘启事总量已累计下降了 46.7%。 这使得新空缺职位的流速比 2020 年 2 月疫情前的水平还低了约 0.8%。 虽然下滑趋势在近几个月有所放缓,但并未出现反弹——招聘动力依然缺失。 这也预示着美国劳工统计局(BLS)的官方职位空缺数据几乎没有上涨空间,因为该数据通常比招聘启事数据滞后几周。 总结:劳动力市场看起来比头条数据所显示的还要疲软。
BREAKING: China’s central bank reported buying 26+ tonnes of gold in October — its biggest monthly addition since August 2023. That comes after 23+ tonnes in September, extending its streak to 24 straight months of net gold purchases. To put that in context: throughout 2025, China didn’t top 5+ tonnes in any single month. So far this year, official purchases total 129+ tonnes, pushing China’s gold reserves to a new record of 2,435 tonnes. That leaves China just 2 tonnes behind France, currently the world’s 4th-largest official gold holder. And judging by the pace, China’s appetite for gold isn’t cooling off.
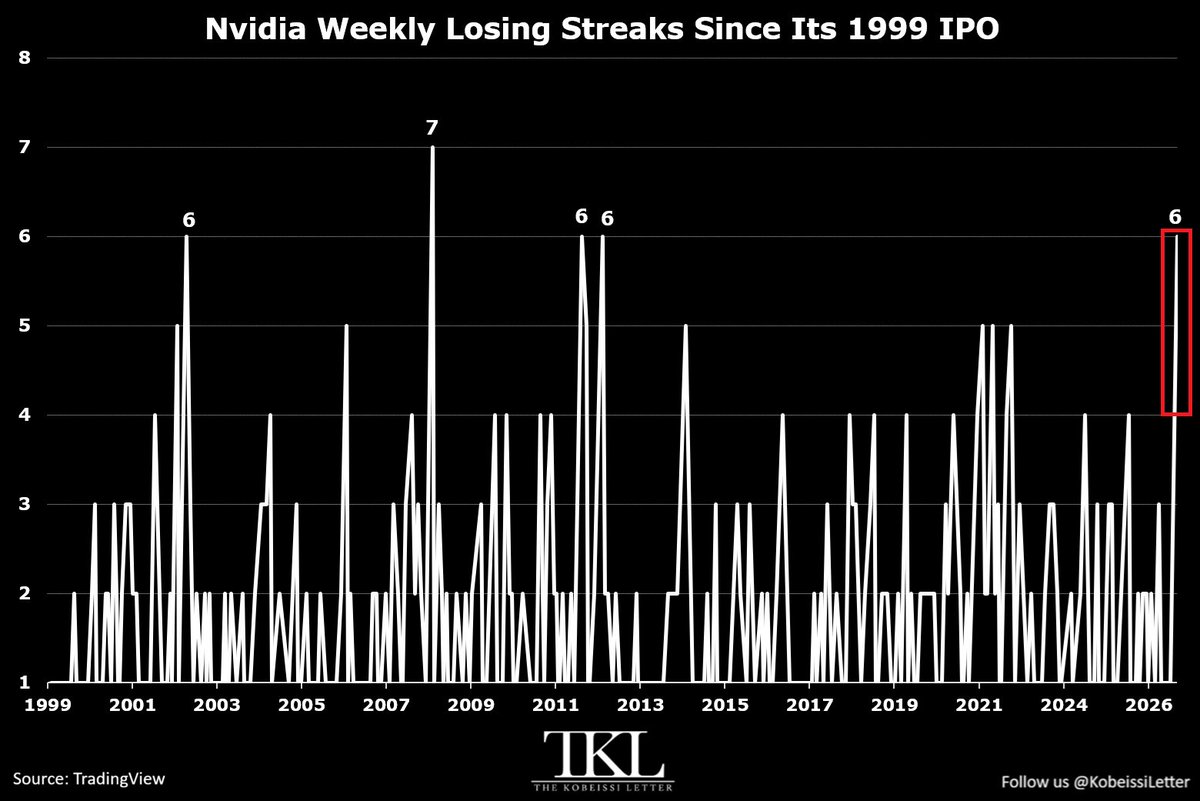
Nvidia is in the middle of a rare slide. Shares of $NVDA have now fallen for six straight weeks—tying the company’s second-longest weekly losing streak on record. Over that stretch, the stock is down 31%, hitting its lowest level since July 2025. Six-week skids like this have been uncommon: they showed up twice in 2012 and once in 2002, in the wake of the post–Dot-Com bust period. The only longer run was seven consecutive weekly declines during the 2008 financial crisis, when Nvidia sank 53%. The damage since the October high has been massive. Nvidia has shed about $1.9 trillion in market value, leaving it around $3.9 trillion. For the year so far, the stock is down 12%, lagging well behind the S&P 500 and Nasdaq 100, both up roughly 10% and 11%. All told, this is close to a once-in-a-generation drawdown for Nvidia.
US hiring still isn’t showing any real signs of coming back. New job postings on Indeed were down 4.8% YoY in the week ending October 16. Since April 2022, postings are now off 46.7% in total. That leaves new available vacancies about 0.8% below where they were pre-pandemic (February 2020). The slide has eased a bit in recent months, but that’s not the same as a rebound—hiring hasn’t turned higher. If anything, it points to little meaningful improvement in the official BLS job openings figures, which typically trail postings by a few weeks. Bottom line: the US labor market looks softer than the headline numbers suggest.
BREAKING: China’s central bank added +26 tonnes of gold in October — its largest monthly purchase since August 2023. That comes after +23 tonnes in September, extending China’s gold-buying streak to 24 straight months. For context, throughout 2025, China didn’t buy more than +5 tonnes in any single month. So far this year, official purchases total +129 tonnes, pushing reserves to a new record of 2,435 tonnes. That leaves China just 2 tonnes behind France, the world’s 4th-largest gold holder. And the pace of China’s gold demand still doesn’t look like it’s easing.
A lot of US car owners are upside down on their vehicles — they owe more than the cars are worth. In Q3 2026, 29% of trade-ins tied to new-vehicle purchases came with negative equity, close to the highest share since Q1 2021. At the same time, the average shortfall on these underwater cars climbed to $7,107, the 3rd-highest level on record. That’s $2,960 higher than the low in Q4 2021 and $1,850 above pre-pandemic levels. And it’s not just trade-ins: buyers who rolled unpaid car debt into new loans ended up with an average loan balance of $57,235 — up 44% from 2019. Their average APR was 8.1%, which pushes total lifetime interest costs to about $16,610, up 83% from $9,093 in 2019. Bottom line: the US is dealing with a real car affordability crunch.
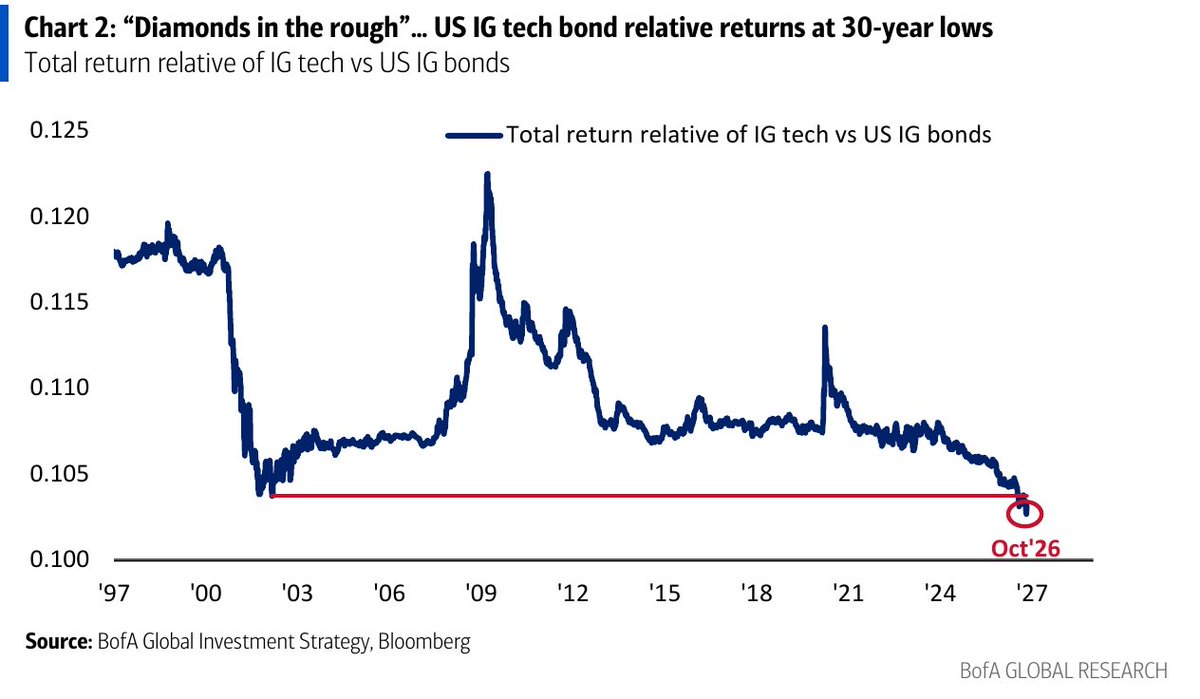
Investors are starting to ask for a bigger payoff to own US tech debt. US investment-grade (IG) technology bonds have lagged the broader IG corporate bond market by about 9% year-to-date, pushing their relative total return to the weakest level in at least three decades. Spreads are telling the same story. The gap between IG tech spreads over Treasuries and the broader IG corporate spread has widened to roughly +15 bps — the largest in at least 14 years. For most of the 2012–2025 period, that gap was actually below zero. Put simply: investors now want an extra yield premium to hold tech bonds versus the rest of the IG market. This shift comes as Big Tech issuance has exploded — a record $182 billion so far in 2026, up from just $17 billion in 2024 (+971%) — with AI now the biggest sector in the IG bond universe. The bottom line: funding the AI boom is getting pricier.
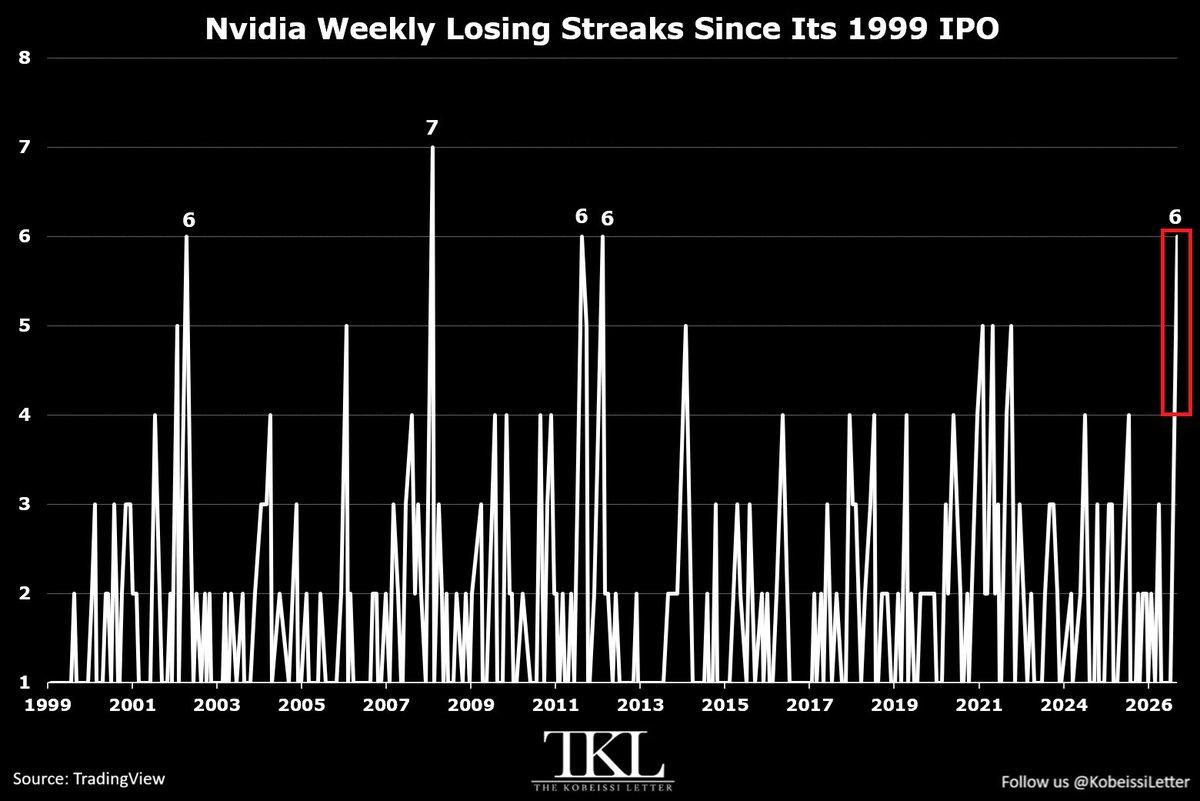
Nvidia is in the middle of a brutal, record‑level slide. $NVDA has now fallen for six straight weeks, tying its second‑longest weekly losing streak ever. Over that stretch, the stock is down 31%, hitting its lowest level since July 2025. The last time Nvidia saw comparable six‑week skids was back in 2012 (twice) and in 2002—periods that came in the aftermath of the Dot‑Com bust. For context, its longest weekly losing streak was seven weeks during the 2008 Financial Crisis, when $NVDA sank 53%. Since the October high, Nvidia has erased about $1.9 trillion in market cap, dropping to roughly $3.9 trillion. So far this year, the stock is down 12%, badly lagging the S&P 500 and Nasdaq 100, which are up about 10% and 11%. This is about as close to an unprecedented drawdown as Nvidia gets.
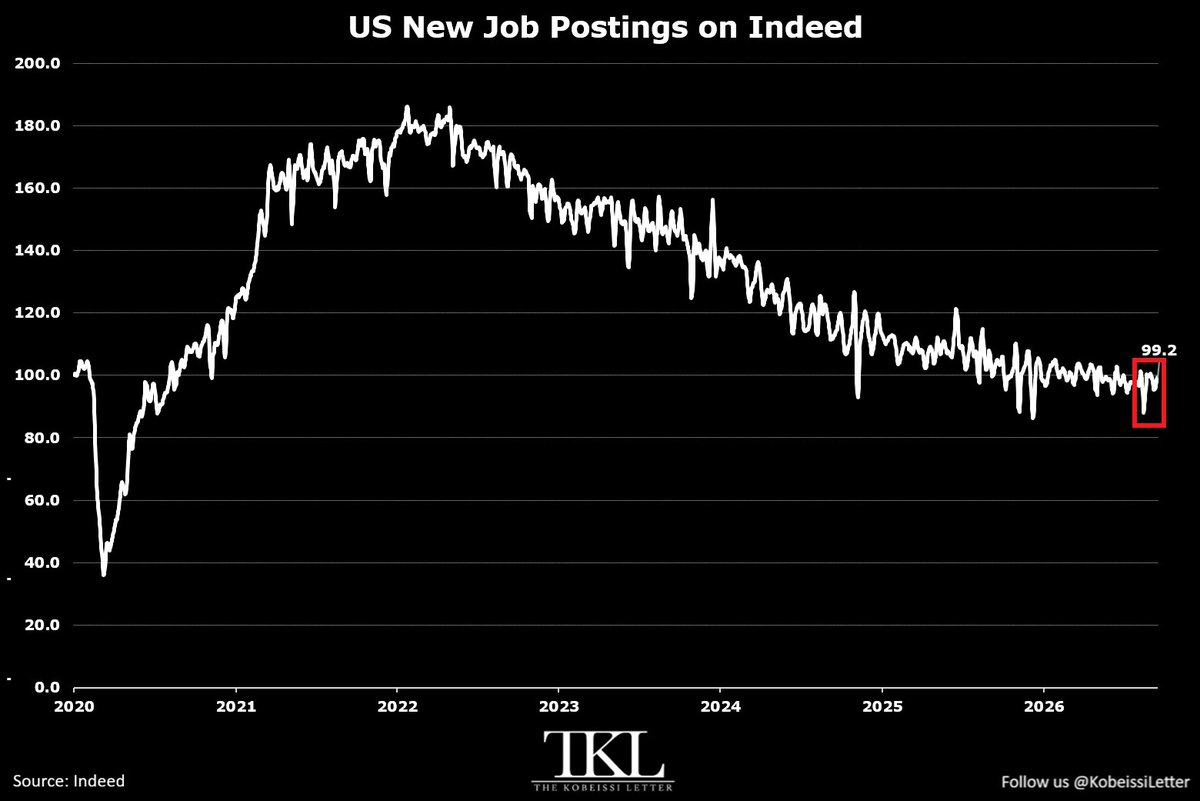
US hiring still isn’t turning the corner. Indeed data show job postings were down about 5% from a year ago in mid-October, and they’re off nearly half compared with early 2022. That leaves new vacancies slightly below where they stood before the pandemic. The slide has become less steep lately, but it hasn’t flipped into a rebound. If anything, this points to little near-term improvement in the official BLS job openings figures, which typically trail postings by a few weeks. Bottom line: the labor market looks softer than the headline narrative suggests.
BREAKING: US Treasury Secretary Bessent says Nvidia, $NVDA, needs a “major overhaul” in the wake of the Jensen Huang scandal. Bessent says the conversation shouldn’t center on Huang’s personal “missteps,” but on the legal and national-security implications. “I keep coming back to Nvidia’s internal culture—were they pushing what look like improper sales to pump up revenue and earnings?” Bessent said. He added that he expects the board to provide answers “within the next 10 days.”
BREAKING: US Treasury Secretary Bessent says Nvidia, $NVDA, needs a “major overhaul” in the wake of the Jensen Huang scandal. Bessent says he wants to move the conversation away from Huang’s personal “missteps” and toward the legal and national-security implications. “I keep coming back to Nvidia’s internal culture—were they pushing what look like improper sales to juice revenue and earnings?” Bessent said. He added that he expects the board to provide answers “within the next 10 days.”
快讯:据英国《金融时报》(FT)报道,继英伟达($NVDA)争议事件后,美国立法者正寻求对人工智能芯片实施更严格的出口管制。 关键点: 1. 多项法案将限制向美国境外买家销售敏感芯片。 2. 这些提案还将允许国会审查并可能阻止此前在特朗普政府时期已获批的交易。 3. 这项举措得到了民主党和共和党双方的支持。 监管力度加大看起来越来越有可能。
Key Events This Week: 1. Fed Chair Warsh speaks — Monday 2. October Retail Sales data — Tuesday 3. Nvidia ($NVDA) earnings — Tuesday 4. October Pending Home Sales data — Wednesday 5. Fed meeting minutes — Wednesday 6. November Philly Fed Manufacturing data — Thursday 7. November MI Consumer Sentiment data — Friday 8. November MI Inflation Expectations data — Friday 9. 15 total Fed speaker appearances throughout the week Another packed week ahead—plenty on the calendar to watch.
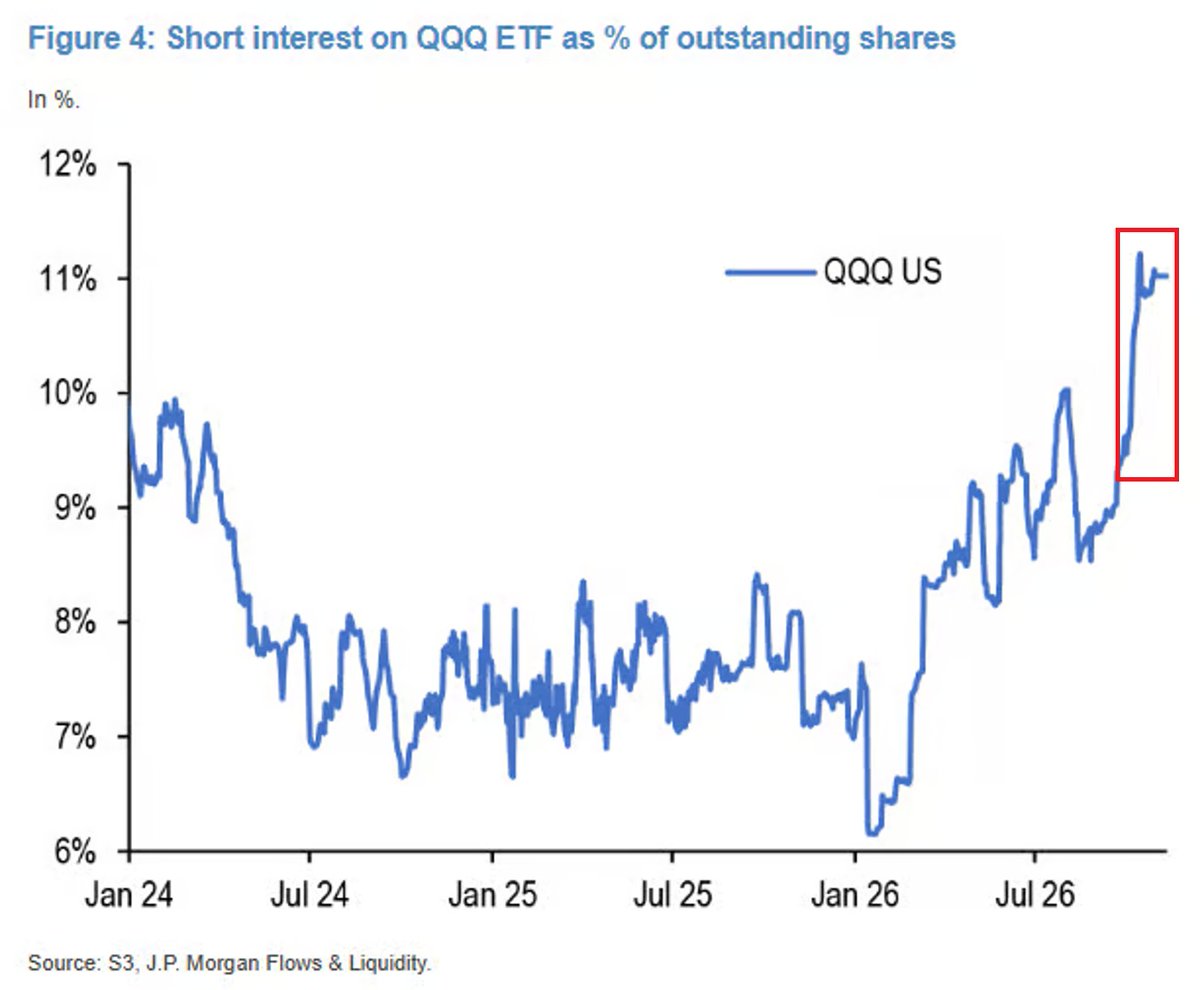
BREAKING: Short interest in the Nasdaq 100 ETF, $QQQ, has climbed to 11% of shares outstanding — the highest level since 2023. That’s a jump of about 5 percentage points since January. For context, during the 2022 bear market, it topped out around 14%. At the same time, Goldman Sachs says hedge funds’ US tech long-to-short ratio has slipped to 1.5 — the lowest reading since the series began in 2016. That ratio is down roughly 0.6 points since June. Is this the kind of setup that can spark a tech short squeeze?
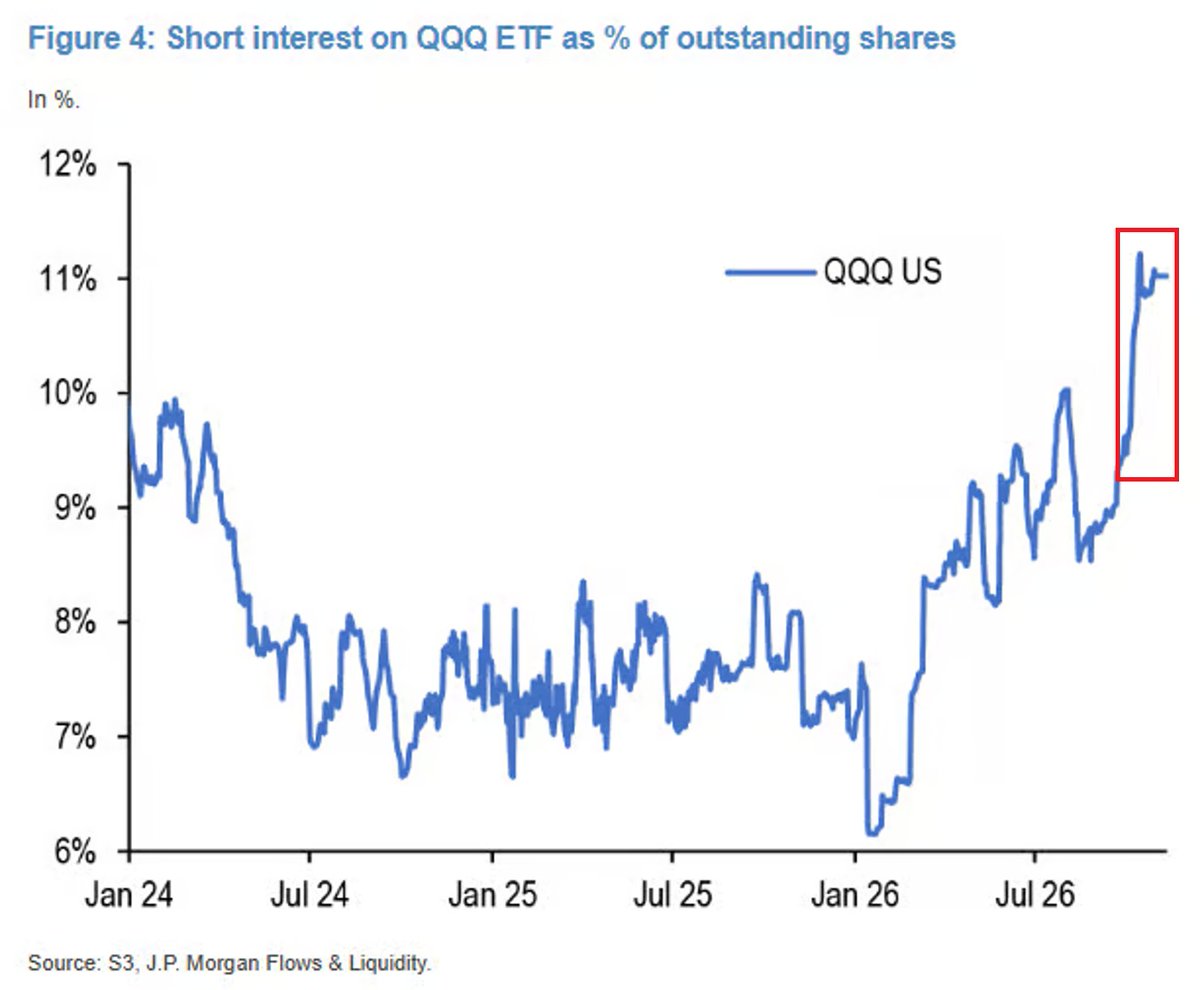
BREAKING: Short interest in the Nasdaq 100 ETF, $QQQ, has climbed to 11% of shares outstanding — the highest level since 2023. That’s a +5 percentage point jump since January. For context, in the 2022 bear market, it topped out around ~14%. At the same time, Goldman Sachs says hedge funds’ US tech long-to-short ratio has slid to 1.5, the lowest reading since the series began in 2016. That ratio is down about -0.6 since June. Is tech starting to look like a setup for a short squeeze?
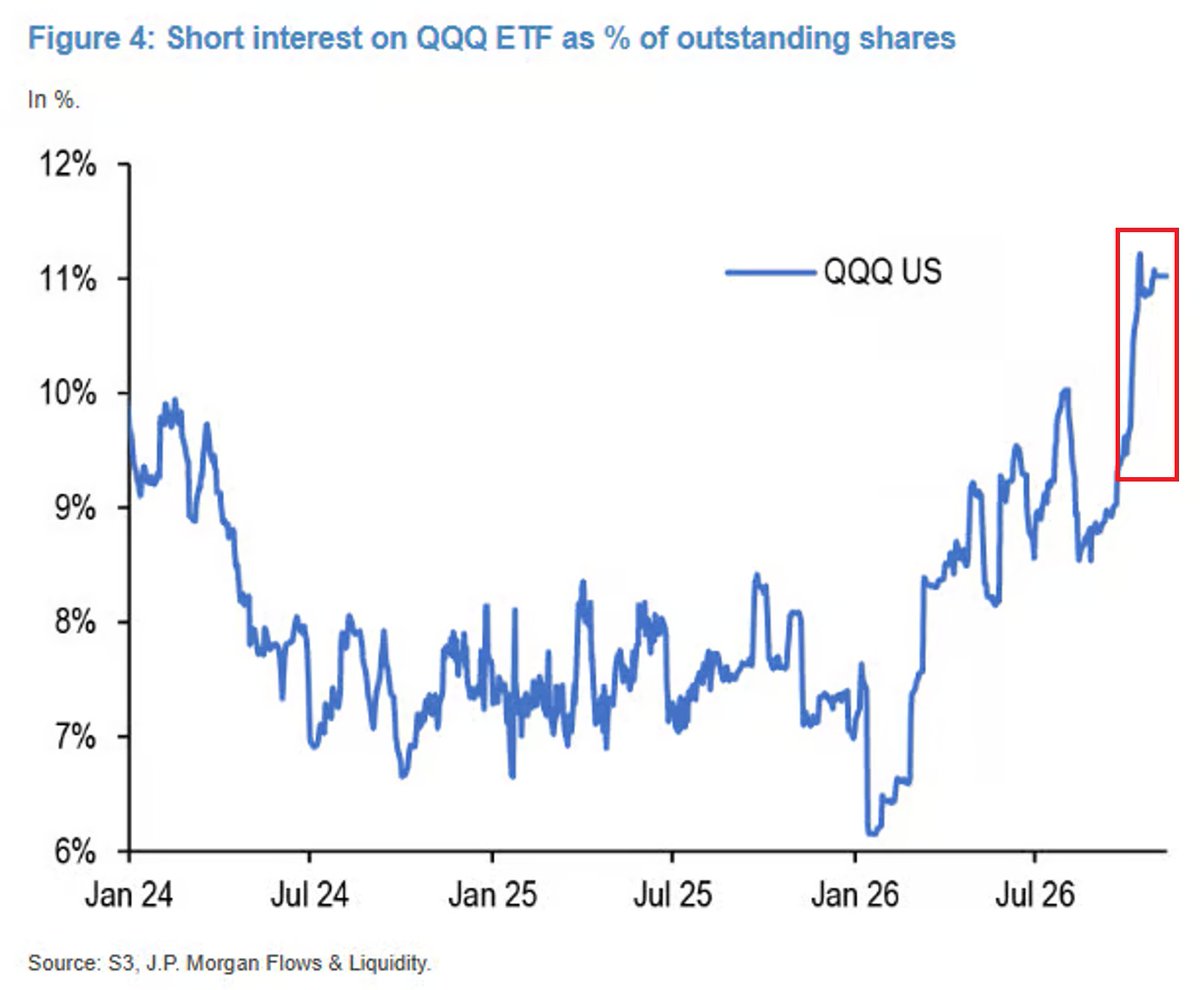
BREAKING: The US Social Security Trust Fund’s deficit widened by $39B YoY in Fiscal Year 2026, hitting a new record at -$221B. The fund covers retirement benefits and payments to eligible survivors of deceased workers. Spending—driven mainly by benefit checks to retirees and survivors—jumped $83B YoY to $1.5T, the highest level on record. Revenue also increased, with income largely from payroll contributions rising $44B YoY to a record $1.3T, but it still wasn’t enough to close the gap. Since FY2022, the deficit has ballooned by $188B (+585%). That shortfall is now showing up in the reserves: trust fund assets fell $221B YoY in FY2026 to $2.18T, the lowest since 2007, and $640B below the 2017 peak. Bottom line: Social Security’s finances are weakening fast.
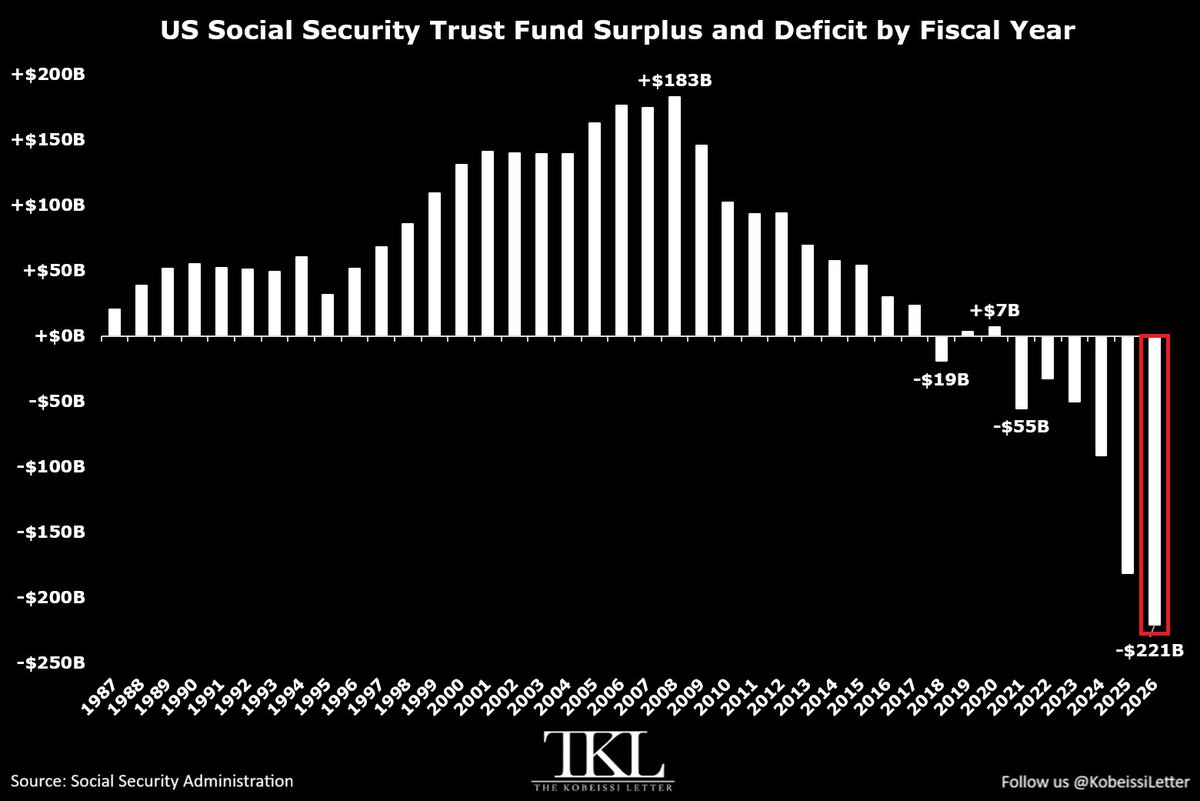
BREAKING: Short interest in the Nasdaq 100 ETF, $QQQ, has climbed to 11% of shares outstanding—its highest level since 2023. That’s a jump of about 5 percentage points since January. For context, during the 2022 bear market, short interest topped out around 14%. At the same time, Goldman Sachs says hedge funds’ US tech long-to-short ratio has slipped to 1.5—the lowest reading since the data series began in 2016. That ratio is down roughly 0.6 points since June. Is the setup building for a tech short squeeze?