Ayzal Noor
1533Like0Shares21Fans2Follow
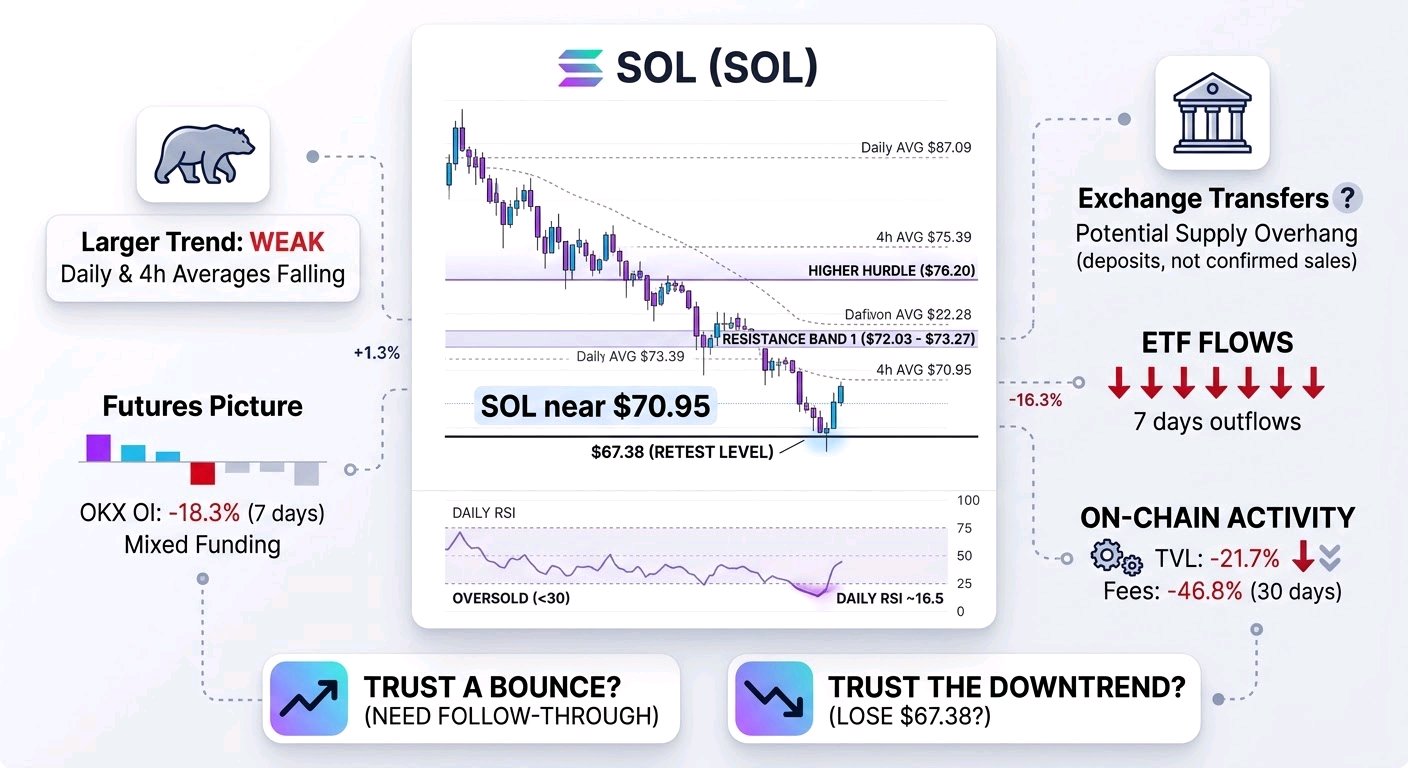
$SOLUSDT is near $70.95 after losing 20.3% in 7 days. It touched $67.38, its lowest since late June, before rebounding. That low is the clearest nearby test: hold it, and a short-term base remains possible; lose it, and the bounce has failed to stop the sequence of lower prices. Neither outcome is confirmed yet. The larger trend remains plainly weak. SOL is below its falling 4-hour averages around $75.39 and $80.85 and its daily averages near $87.09 and $95.48. Daily RSI is about 16.5, an unusually stretched reading. That makes a relief rally plausible, but it does not tell us that selling is finished. On the 1-hour chart, SOL has struggled to hold above $72.03–$73.27, the first resistance band formed by recent highs. A move through that zone followed by a held retest would be more convincing than a brief spike. $76.20 is a higher hurdle; reclaiming it would improve the short-term structure, though not erase the broader downtrend. What would make me trust a bounce? Follow-through, not just an oversold reading. The latest candles show a rebound from $67.38, but price has not established itself above nearby resistance. The data available here do not include reliable 15-minute charts, MACD, volume broken down by candle, order-book depth or liquidation heatmaps. So we cannot verify whether the bounce had strong spot buying behind it, identify precise liquidation clusters, or claim that a particular level will trigger forced buying or selling. Futures give a mixed picture. Funding is slightly negative across major venues, so shorts are paying longs; OKX open interest is down 18.3% over 7 days. That suggests some leverage has come out of the market and leaves room for short-covering if price rises. But positioning is not one-sided: OKX accounts lean long, while top-trader positions lean short. Falling open interest can reflect deleveraging, not necessarily accumulation or an imminent squeeze. Spot activity is large—about $5.45 billion over 24 hours across 63 venues—but the total alone cannot tell us whether buyers absorbed supply or sellers dominated the trading. The reported exchange transfers deserve attention, but not a dramatic conclusion. News reports describe large SOL deposits, including movements linked to Forward Industries; the company disputed ownership attribution for one reported transfer. The on-chain movements may be real, but a deposit does not prove a sale. That makes this a potential supply overhang, not confirmed selling. The broader market is also under pressure: total crypto market capitalization fell 5.2% in 24 hours, and fear is at 10, an extreme reading. Is SOL’s weakness mainly its own supply and activity, or is it being amplified by a market-wide risk-off move? Both may be true. There are longer-term positives, but they do not settle the short-term trade. DTCC’s tokenization plans include Solana, and the network is hosting its Breakpoint conference. Those developments may matter over time; they have not yet produced a visible price reversal. Meanwhile, the more immediate figures are soft: ETF flows show 7 consecutive days of outflows, totaling $32 million over 5 days and $120 million over 20 days. Over 30 days, value locked fell 21.7%, stablecoin supply 7.1%, and fees 46.8%. These are verified signs of weaker flows and activity, but we cannot assume they predict the next few sessions. My read is deliberately conditional. Above $67.38, a relief bounce remains credible, especially if price reclaims $72.03–$73.27 on sustained participation. Below that swing low, the bearish interpretation gains weight. What would change the balance? Spot demand holding a retest, open interest rebuilding as price rises, and ETF outflows easing would make the bounce more substantial. Another rejection at resistance, continued outflows, or a breakdown would argue that oversold conditions have not stopped the downtrend. For now, neither side has the confirmation it needs.#IMPACTbyTrade
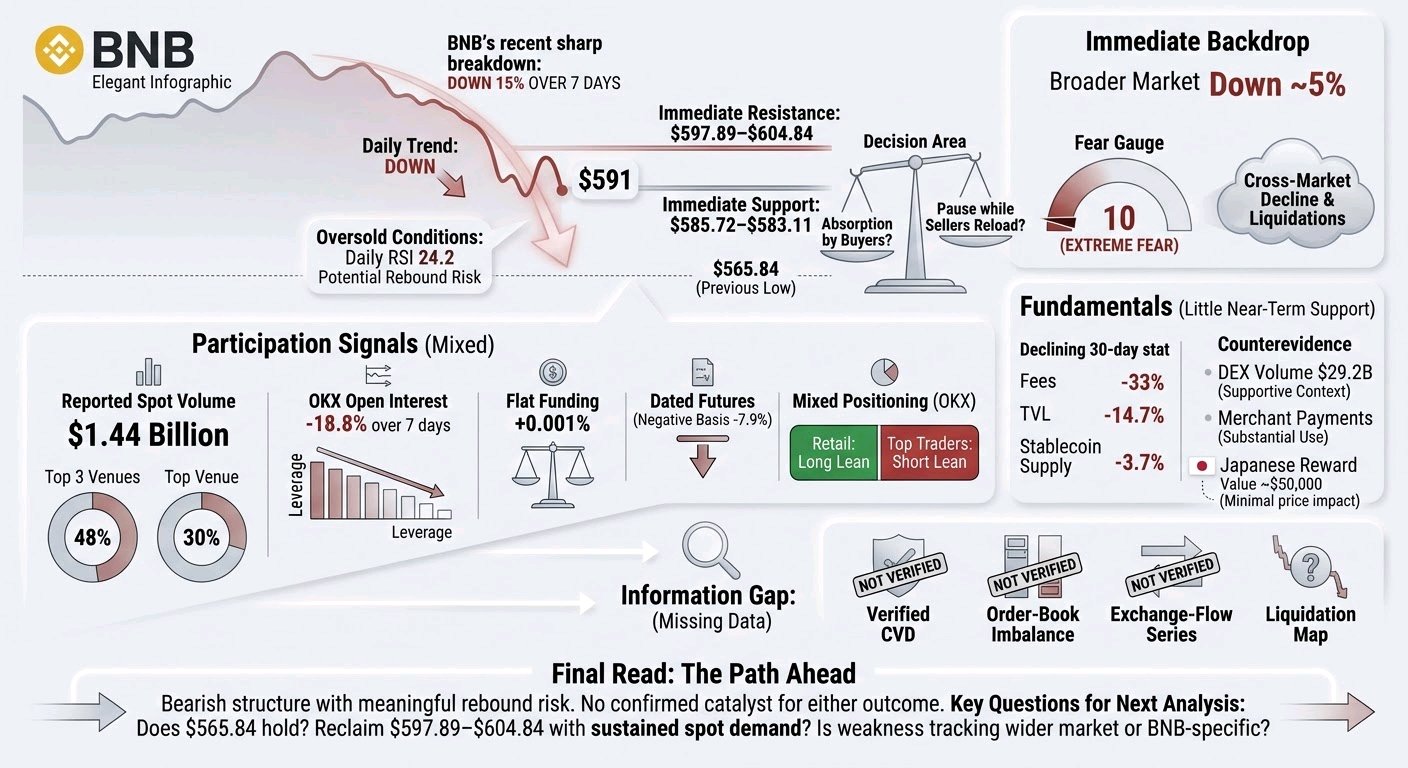
$BNBUSDT is trying to stabilize after a sharp breakdown, but I don’t yet see evidence that the market has changed character. The key distinction is whether buyers are absorbing supply—or merely taking a pause while sellers reload. Verified: BNB is near $591, down 15% over 7 days. It fell to $565.84 and rebounded as high as $599.63, but recent hourly closes failed to hold above $597.89. The 1-hour, 4-hour and daily trends remain down. Daily RSI is 24.2, which signals oversold conditions, not a confirmed bottom. Price remains below the 1-hour EMA50 at $604.84, the 4-hour EMA20 at $615.86, and the daily EMA20 at $674.78. That leaves a nearby decision area. $585.72–$583.11 is short-term support; below it, the market would be testing $565.84 again. If that low breaks and price cannot quickly reclaim it, sellers retain control. On the other hand, a sustained move above $597.89–$604.84, followed by a successful retest, would be more meaningful than a brief intraday spike. The next substantial resistance is around $620.60–$620.85. Could BNB reclaim those levels while the broader market remains weak? That would be stronger evidence of demand than oversold readings alone. Participation signals are mixed. Reported spot volume is $1.44 billion across 62 venues, but the top 3 account for 48%, with one venue representing 30%. That makes the headline volume less persuasive as proof of broad-based buying. Perpetual open interest is $563 million across 4 tracked venues; OKX open interest is down 18.8% over 7 days. That suggests leverage has been coming out there, but it does not establish the direction of aggregate market-wide positioning. Funding is nearly flat at +0.001% per 8 hours, while dated futures trade at a negative 7.9% annualized basis. On OKX, retail accounts lean long, while top traders’ positioning leans short. Those crosscurrents do not point to an obvious, crowded short that must be squeezed. The important gap is what we cannot establish from these figures: there is no verified CVD, order-book imbalance, exchange-flow series, or liquidation map here. So we cannot confidently say whether spot buyers absorbed the selloff, where forced liquidations clustered, or whether the rebound was driven mainly by short covering. A liquidation level, if identified, would be a possible volatility point—not a guaranteed turning point. The immediate backdrop also matters. The broader crypto market is down about 5% in the latest snapshot, with fear at 10, down from 28 a week ago. News on Nov. 13 described a sharp cross-market decline and forced liquidations as Bitcoin and other major assets fell. That supports the interpretation that BNB’s slide was amplified by general risk aversion, rather than being solely a BNB-specific event. But it raises a useful question: if the broader market stabilizes, does BNB recover with it—or continue to lag? Fundamentals give little near-term support for a bullish reversal. Over 30 days, BNB Chain fees fell 33%, TVL fell 14.7%, and stablecoin supply fell 3.7%; these figures reinforce a weaker activity backdrop, though they do not prove what caused this week’s price move. There is counterevidence: reported 30-day DEX volume is $29.2 billion, and a recent merchant-payments report described substantial use of BNB Chain. Those are supportive context, not evidence of new buying pressure. A Japanese company’s announced BNB shareholder reward is worth watching, but its reported value is only about $50,000 and the reference date is Dec. 31. It does not look large enough to explain this selloff or reverse it by itself. My read: bearish structure, meaningful rebound risk, and no confirmed catalyst for either outcome. The next analysis should answer three questions: does $565.84 hold on a retest; can BNB reclaim $597.89–$604.84 with sustained spot demand; and is the weakness still tracking the wider market, or becoming BNB-specific?#IMPACTbyTrade
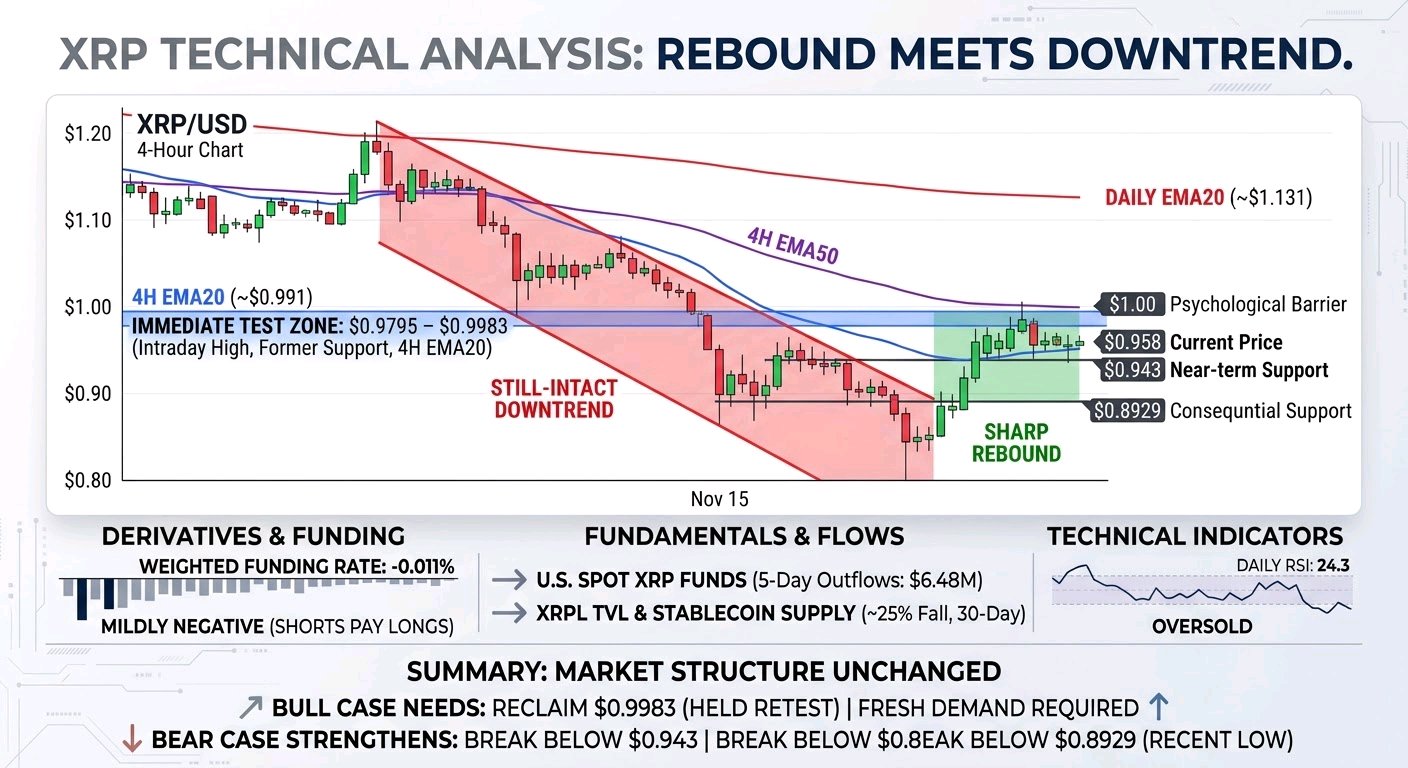
$XRPUSDT is caught between a sharp rebound from a two-year low and a still-intact downtrend. At about $0.958 on November 15, it is up 4.78% from the prior daily close, after trading as low as $0.8993. That bounce matters, but it has not yet changed the market structure: XRP remains below $1, below its 4-hour EMA20 near $0.991, and well below its daily EMA20 near $1.131. The market is asking whether buyers have found real demand—or whether they are simply responding to an oversold flush. The immediate test is $0.9795–$0.9983. That zone combines the recent intraday high, the former $1 support area, and the 4-hour EMA20. A brief move above it would not be enough by itself. I would want to see XRP hold above the zone on a retest, with meaningful spot buying and open interest rebuilding. Otherwise, a rally could be short covering or position adjustment rather than fresh demand. A break below $0.943 would weaken the near-term bounce; $0.8929, the recent low, is the more consequential support. If that level gives way, the market has not yet shown a strong nearby base. The broader technical picture is unambiguous, though not a timing signal. XRP is down 17.2% over 7 days and 28.0% over 30 days. The daily RSI is 24.3, an oversold reading, but oversold markets can remain weak. On the 1-hour chart, price is near the EMA20 and below the EMA50 around $0.976; on the 4-hour chart it remains below both the EMA20 and EMA50. These facts favor caution on the bounce, but a successful reclaim of $0.9983 would make the bearish interpretation less secure. The derivatives picture is mixed. Funding is mildly negative across the tracked venues, with the weighted rate at -0.011% per 8 hours; shorts pay longs, which can make short positions costly and leave room for a squeeze. Yet this is not evidence that a squeeze is underway. OKX open interest is down 9.4% over 7 days, but that is one venue, and dollar-denominated open interest can fall simply because the token price falls. Long/short data also conflicts: accounts are net long, while top traders’ positions lean short. Reported recent liquidations hit longs hardest, but the available figures do not establish precise liquidation clusters or prove broad market-wide deleveraging. We still need to ask: if price rises, does open interest grow with it, or do shorts merely close into thin demand? There are real fundamental headwinds, but their timing is less clear. U.S. spot XRP funds saw $6.48M in net outflows over 5 days and $1.18M over 20 days, though the latest reported session was positive. XRPL stablecoin supply and value locked each fell about 25% over 30 days. Those are signs of weaker marginal demand and network capital, not proof that they caused this week’s selloff. A reported 240M XRP transfer did not reach an exchange, and exchange-balance readings are disputed because newly tracked wallets changed the totals. Neither establishes a wave of sell-side deposits. No verified new announcement or token unlock in the retrieved recent news clearly explains the move; 36.5% of maximum supply remains outside circulation, a longer-term supply consideration, not evidence of an immediate release. My read is that broad crypto weakness, extreme fear, ETF outflows, and long liquidations explain the pressure better than any single XRP-specific event. But we lack spot CVD, order-book imbalance, and reliable whale-flow evidence, so claims of accumulation or distribution would be premature. The bull case needs a held reclaim of $0.9983, supported by spot demand; the bear case strengthens if $0.943 fails and especially if $0.8929 breaks. Which side is actually taking initiative—spot buyers or leveraged traders—and will the next move in open interest confirm it?#IMPACTbyTrade
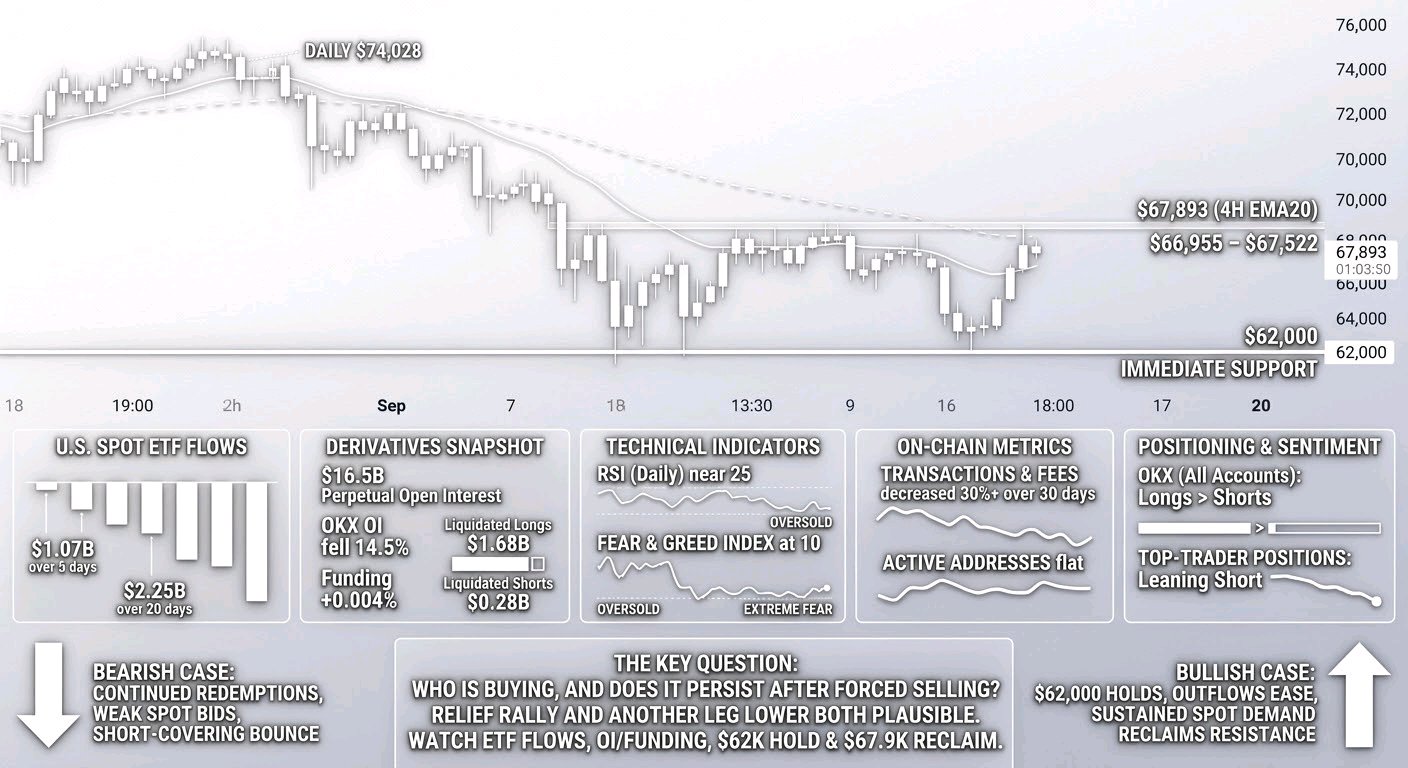
$BTCUSDT rebound from $62,000 to around $65,600 is worth watching, but I would not yet call it a turn. The sell-off came with a clear demand headwind: U.S. spot Bitcoin funds recorded 7 consecutive outflow days, including $1.07B over 5 days and $2.25B over 20 days. Those are meaningful flows, though they do not tell us by themselves whether broader spot buyers stepped in at the lows. The derivatives picture is mixed. Open interest across tracked perpetual markets is $16.5B, and OKX open interest fell 14.5% over the week. That points to positions being reduced during the decline, consistent with deleveraging. News reports put crypto liquidations near $1.96B in 24 hours, with roughly $1.68B from longs. The sharp rejection of $62,000 followed by a bounce fits a possible liquidation-driven flush. But it does not prove forced selling is finished. Funding is still slightly positive overall at +0.004% per 8 hours, while venue readings differ. Long exposure may therefore remain, even as some positions have been cleared. Positioning data also disagree: OKX shows more long than short accounts, while top-trader positions lean short. These ratios describe selected accounts, not the whole market, so I would not treat either as a reliable forecast. What matters next is whether open interest rebuilds alongside sustained spot demand—or rises with positive funding and leaves the market vulnerable to another long squeeze. CVD and order-book imbalance would help answer that, but we do not have them here. On the chart, $62,000 is the immediate line that matters. It is the recent low and the lower edge of the current rebound; losing it would weaken the capitulation-and-recovery interpretation and put the earlier $57,809 swing low back in focus. Above price, $66,955–$67,522 is the first resistance area. A clean break, followed by a successful retest, would be more convincing than a brief intraday push. The 4-hour EMA20 near $67,893 is another hurdle. Until BTC can reclaim that level, the larger trend remains down: price is well below the daily EMA20 near $74,028, and the weekly trend is also down. There is a bullish argument, but it needs confirmation. Daily RSI near 25 is deeply depressed, and extreme fear at 10 can accompany forced selling and sharp rebounds. Bitcoin’s capped supply and institutional access remain longer-term supports. Yet neither oversold momentum nor scarcity creates a short-term floor. Transactions and fees have fallen over 30 days, while active addresses are flat. That suggests weaker settlement activity, but does not establish that holders are broadly exiting. Likewise, the ETF outflows are evidence of weaker marginal demand, not proof of a permanent institutional retreat. The bearish case is that redemptions continue, spot bids fail to absorb supply, and the bounce is mostly short-covering after the liquidation wave. The bullish case is that $62,000 holds, outflows ease, and BTC reclaims resistance on sustained spot participation. The key question is not simply whether price can bounce; it is who is buying, and whether that demand persists after forced sellers are gone. I would watch ETF flows, spot-versus-futures participation, open interest and funding together, plus whether $62,000 holds and $67,900 is reclaimed. Until then, both a relief rally and another leg lower remain plausible.#IMPACTbyTrade
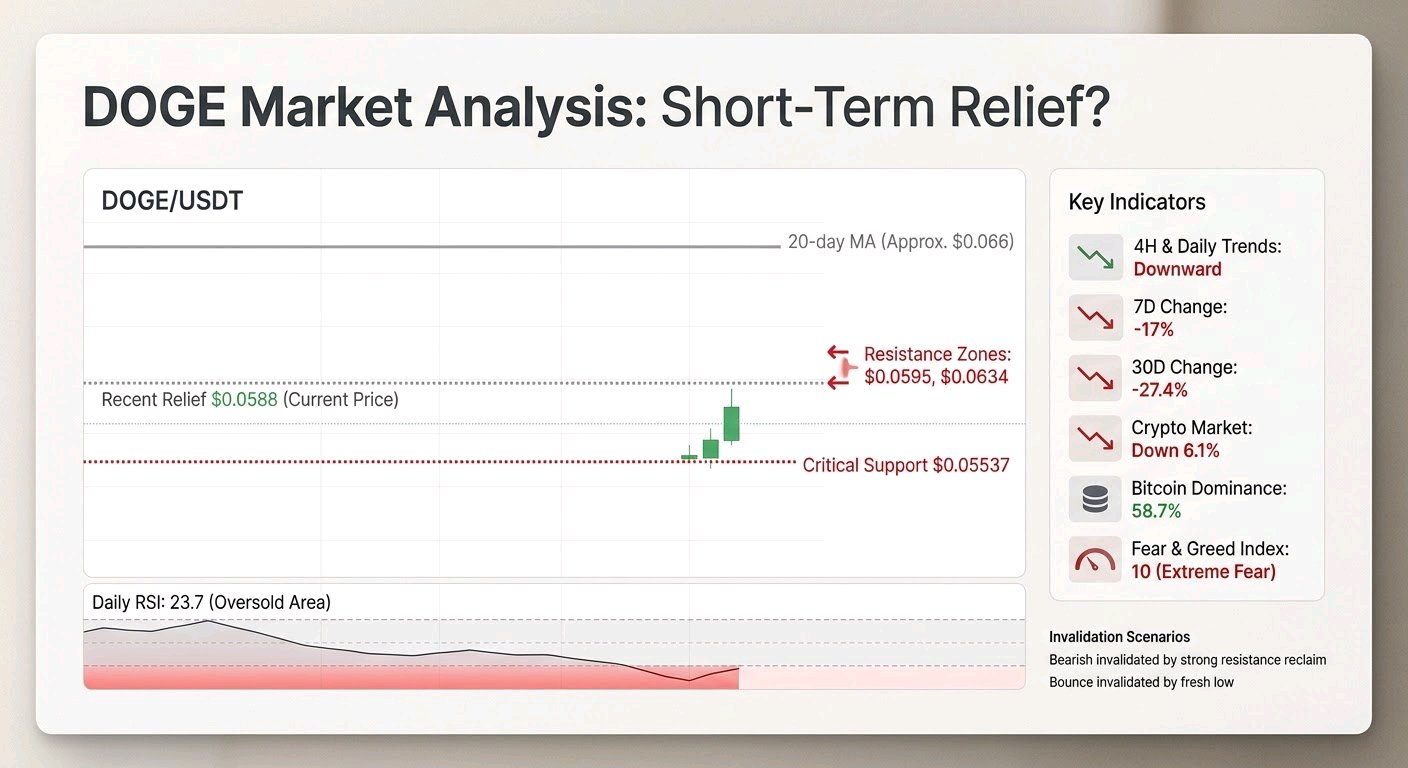
$DOGEUSDT is trying to bounce after a sharp breakdown, but so far the evidence looks more like short-term relief than a change in trend. At $0.0588, it is up 2.54% from the previous daily close, after trading as low as $0.05537. That low matters: it is the clearest recent support and the bottom of the past week’s selloff. Does holding there show that buyers are stepping in, or simply that selling paused after a fast decline? The broader structure is still weak. DOGE is down 17% over 7 days and 27.4% over 30 days. The 4-hour and daily trends remain downward, with price well below their 20-period averages. Daily RSI is 23.7, an oversold reading that can precede a rebound, but does not itself signal a reversal. On the hourly chart, price remains below the 20-period average near $0.0595 and the 50-period average near $0.0620. The bounce has not yet reclaimed either convincingly. I would watch $0.0595 first, then $0.0634. The latter is a recent resistance area and a more meaningful test of whether sellers are losing control. A brief move above a level is not enough; does price hold it on a retest, with stronger spot participation? No available data here confirms a 15-minute breakout, cumulative volume delta (the running balance of aggressive buying versus selling), or order-book imbalance. Nor do we have a reliable liquidation map. So exact liquidity clusters and liquidation levels should not be inferred from the chart alone. Derivatives give a mixed, not decisive, read. Perpetual open interest is reported at $324 million across 4 venues; OKX open interest is down 17.1% over 7 days. That suggests leverage has been coming out, though it is only one venue’s change and does not tell us whether spot sellers or futures traders initiated the move. Funding is slightly negative overall, meaning shorts pay longs, but Binance funding is positive. Top-trader positioning also differs from the long-heavy account ratio. Could this create fuel for a short squeeze if price rises? Possibly, but the negative dated-futures basis—30.4% annualised—shows substantial bearishness, not a reliable reversal signal. A squeeze can lift price without changing the underlying trend. The backdrop matters. The whole crypto market is down 6.1% over 24 hours, Bitcoin dominance is 58.7%, and the fear-and-greed reading is 10. News coverage describes a broad meme-coin rout and reports no net DOGE ETF flows for a month. Those facts fit weak risk appetite, but headlines do not establish what actually caused DOGE’s selling. A claim that whales bought 1.8 billion DOGE has circulated, yet the report lacks wallet and transaction details. Without verification, I would not treat it as evidence of accumulation. Likewise, no DOGE-specific on-chain or exchange-flow data is available here to confirm whether coins are moving onto exchanges or into long-term holdings. Fundamentally, DOGE’s circulating supply is reported as 157 billion, equal to total supply; that does not mean issuance stops, since DOGE has ongoing issuance. There is no verified, near-term project catalyst in the evidence reviewed. Protocol fees and revenue are small relative to market value, so price is more likely to respond to sentiment and market flows than to a sudden change in network economics. My read is cautious, not certain. The bullish case is a defended $0.05537 low followed by a sustained reclaim of $0.0595 and then $0.0634, ideally with spot demand and open interest stabilising or rebuilding. The bearish case is a failed resistance test and a decisive loss of $0.05537, especially if the wider market remains weak. What would invalidate the bearish interpretation? A held resistance reclaim with credible spot buying. What would invalidate the bounce? A fresh low. Until those questions are answered, the rebound is a possibility—not proof that control has changed.#IMPACTbyTrade
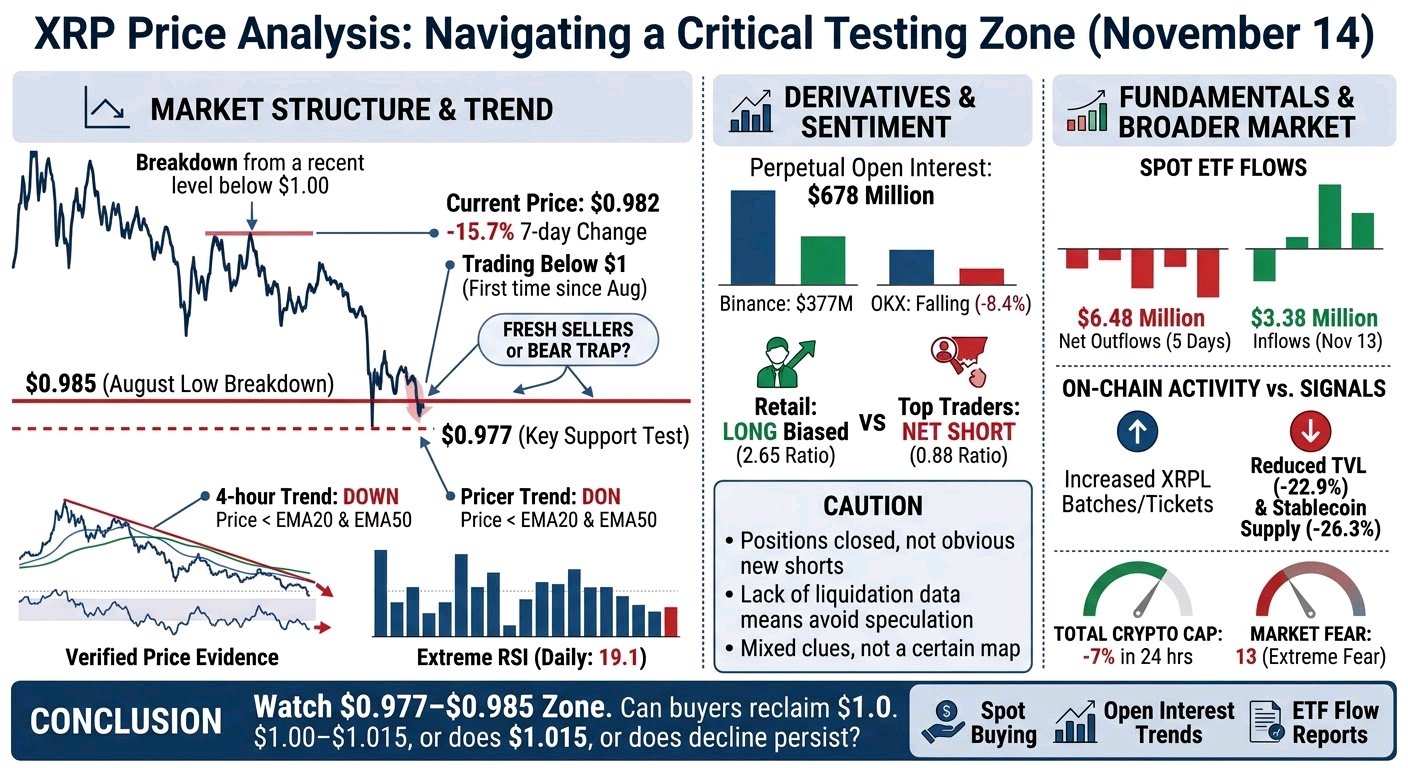
$XRPUSDT is caught between a clear downtrend and a price area where selling could become exhausted. At $0.982 on November 14, it had lost 15.7% in 7 days and was trading below $1 for the first time since August, after breaking the reported August low near $0.985. That is a meaningful loss of structure, but the market is now testing the same zone it just broke. Does a move below $0.977 attract fresh sellers, or do buyers reclaim it quickly and turn the breakdown into a bear trap? The answer matters more than the fact that XRP is oversold. Verified price evidence: The 1-hour, 4-hour, daily and weekly trends are down. Price is below the 1-hour EMA20 and EMA50 near $0.999 and $1.015, and the 4-hour averages near $1.026 and $1.083. Daily RSI is 19.1, an extreme reading, while 4-hour RSI is 30.6. Recent 4-hour candles show lower closes and a failed push toward $1.044 before selling resumed. To me, that says sellers still control the broader structure; it does not rule out a sharp bounce. A sustained reclaim of $1.00, then $1.015, would be the first evidence that buyers are changing the near-term balance. A close below $0.977 followed by a weak retest would make the breakdown more convincing. Neither outcome is confirmed yet. The derivatives picture is more mixed than the chart. Perpetual open interest is $678 million, with $377 million on Binance; OKX open interest fell 8.4% over 7 days. That decline alongside falling price is consistent with positions being closed or liquidated, rather than an obvious wave of new leveraged shorts. Funding is almost flat to slightly negative at -0.001% weighted. Retail accounts are long-biased at 2.65, while top traders’ positions are net short at 0.88. These are clues, not a map of who will be forced out. We do not have verified liquidation totals, liquidation-price clusters, CVD, or order-book imbalance. So claims that a particular level is “packed” with liquidations—or that a squeeze is imminent—would be speculation. There are signs of weak demand, but they need careful handling. Verified US spot ETF data show $6.48 million of net outflows over 5 days and $1.18 million over 20 days, despite $3.38 million of inflows on November 13. A separate report claims $19.13 million of weekly outflows; that conflicts with the 5-day figure and should not be treated as settled. News also reports exchange balances rose by 335.76 million XRP over 3 months. If accurate, that may mean more readily available supply, but it does not show that holders are selling now. We lack direct whale-flow and exchange-flow confirmation. The bullish counterpoint is increased XRPL batch and ticket activity. That shows activity, not necessarily XRP purchases: on-chain evidence does not establish that these transactions generated scaled token demand. Meanwhile, reported value locked is down 22.9% over 30 days and stablecoin supply on XRPL down 26.3%. Those figures make the activity headline less persuasive as a near-term demand signal. The broader market is also under pressure: total crypto capitalization fell 7% in 24 hours and fear is at 13. XRP’s weakness may therefore reflect both market-wide risk aversion and coin-specific supply concerns. My read is cautious, not certain. The key zone is $0.977–$0.985; above it, $1.00–$1.015 is the first reclaim test. Watch whether spot buying accompanies a recovery, whether open interest rises or keeps shrinking, and whether ETF-flow reports reconcile. Those answers would tell us whether this is capitulation, temporary exhaustion, or simply another pause in a persistent decline.#IMPACTbyTrade
$BNBUSDT is in a fragile position. The seven-day decline has been sharp, but the important question is whether this is a BNB-specific breakdown or a broad crypto deleveraging event. The verified facts are clear. BNB is near $615 after falling about 11.5% in 7 days. Bitcoin and the wider market also sold off heavily, with extreme fear at 13. BNB is below its 1-hour EMA20 and EMA50, at roughly $624 and $637, and well below its 4-hour averages near $643 and $667. Daily RSI is 24.6. That confirms strong selling pressure, but not a bottom. The immediate battle is around $612.50–$613.71. This area has held several tests, but the rebounds have been weak. Why does that matter? A support level is more credible when buyers can produce a strong recovery after defending it. So far, the market has shown defense, not clear accumulation. A confirmed hourly close below $612.50 would be meaningful. The next visible downside areas are $599.70 and then $585.20. However, a break alone would not prove that fresh short sellers are in control. Open interest has been declining, especially on OKX, where it fell 12.4% over 7 days and 24.5% over 30 days. Price falling while open interest falls often reflects deleveraging or liquidations rather than a clean build-up of new shorts. Derivatives therefore provide a warning, but not a complete explanation. Perpetual open interest is about $596M, concentrated on Binance at $481M. Funding is barely positive at +0.001% per 8 hours, which is too mild to show an extreme long squeeze by itself. Dated futures basis is more negative, at about -7.8% annualized. Retail accounts are long-skewed at 2.90, while top-trader ratios are below 1. That conflict matters: weaker participants may be leaning long, but stronger traders are not showing the same conviction. Spot activity is substantial, with roughly $1.16B in reported volume, but it is concentrated across a few venues. We do not have reliable CVD, order-book imbalance, liquidation totals, or verified liquidation heatmaps. That limits confidence in any claim that forced selling, rather than genuine spot distribution, caused the move. Fundamentally, the backdrop is not supportive. Thirty-day chain fees fell 33.7%, TVL fell 11.6%, and annualized valuation multiples remain very high relative to protocol revenue. These figures explain why BNB may be vulnerable, but they do not prove that fundamentals caused this week’s decline. The recent $40M application exploit is a risk, yet its direct price impact remains unestablished. The bullish scenario is a failed breakdown: support holds, price reclaims $620.60, then closes above $623.85. A move through $639.32–$649.60 would be stronger evidence that sellers are losing control. The bearish scenario is a close below $612.50 followed by expanding open interest and continued weak spot demand. My main uncertainty is the character of the next move. Is support absorbing supply, or merely delaying another liquidation wave? The final answer depends on whether price breaks support with new leverage, or reclaims resistance with real spot participation.#IMPACTbyTrade
$ETHUSDC Ethereum is sitting in an uncomfortable place: the short-term chart is stretched to the downside, but the evidence so far does not show that sellers have been exhausted. Verified: ETH is around $1,894, down 15.6% over 7 days. It has closed 6 consecutive weekly candles lower and remains beneath its daily EMA20 and EMA50, near $2,170 and $2,302. On the 4-hour chart, price is also below both trend averages, around $1,989 and $2,084. The immediate test is $1,875–$1,895, a recent low area. A decisive close below it would make the next weekly supports, $1,744 and $1,504, more relevant. But a level is not a prediction: what matters is whether price breaks and holds below it, or quickly reclaims it. The bearish structure is clear; the quality of the selling is less clear. Daily RSI is near 23 and 4-hour RSI near 27, readings consistent with an oversold market, not a reliable reversal signal. A bounce that stalls below $1,956–$1,989 would still leave the short-term downtrend intact. Reclaiming that zone and holding a retest would be a better first sign of buyers regaining control. Even then, price would remain below the 4-hour trend averages. What would turn a bounce into a genuine structural change? A higher low, follow-through, and stronger spot participation—not simply one green candle. Derivatives evidence is mixed. Open interest across the tracked perpetual venues is $10.7B; OKX open interest is down 12.1% over 7 days. Funding is close to flat, at a weighted +0.002% per 8 hours. That combination is more consistent with leverage being reduced than with a fresh, crowded short trade. Yet OKX long accounts outnumber shorts 3.26 to 1, while top-trader positions lean short. These are different measures of positioning, not proof of an imminent squeeze. We do not have verified liquidation totals or heatmaps, nor CVD, order-book imbalance, or a reliable futures-volume breakdown. So claims about exact liquidation clusters—or who is driving the next move—would be speculation. The broader demand picture is harder to dismiss. Verified: US spot ETH ETFs saw net outflows of $399M over 5 days and $1.42B over 20 days, though November 13 showed a small $2.3M inflow. One day does not establish a turn. Recent reporting also describes a Foundation-linked wallet selling ETH, alongside several large buyers accumulating during the decline. Those are notable, but isolated wallet transactions do not prove broad buying or explain the full price move. The wider market is weak too: total crypto market value fell 5.1% in 24 hours, and sentiment is at extreme fear. That makes it plausible ETH’s decline reflects general risk reduction as well as Ethereum-specific concerns. The fundamentals offer a real tension. Ethereum still records substantial activity: $51.1B of monthly DEX volume and $132B in stablecoins. Yet stablecoin balances are down 8.4% over 30 days and TVL is down 17.8%. Annual protocol revenue is $47.4M against a $231B market cap. Meanwhile, institutional tokenization and custody developments are constructive, but public evidence does not show that they have yet created material ETH buying or revenue. My read is cautious, not certain: the trend favors sellers, while oversold price action and selective whale buying leave room for a sharp rebound. The key questions are whether $1,875 holds, whether ETF flows turn persistently positive, and whether a reclaim of $1,956–$1,989 comes with genuine spot demand. If not, is this merely a pause before another leg lower? #IMPACTbyTrade
$BTCUSDT weakness looks less like a single liquidation event and more like demand retreating while traders reduce risk. That distinction matters: a market can keep sliding without a fresh wave of shorts if willing spot buyers are absent. What the evidence says: BTC is down 11.8% over 7 days, around $66,794, after breaking below $70,000. The 1-hour, 4-hour and daily trends are down; price is below the relevant short-term moving averages. RSI is deeply oversold—18.9 on the 4-hour chart and 22.5 daily—but oversold conditions can persist in a downtrend. The current test of $66,450 is important because it is the recent local low. It has been touched, but the available snapshot does not establish a confirmed hourly close below it. There are signs of real selling pressure beyond the chart. US spot Bitcoin ETFs had 7 consecutive days of outflows, totaling $2.10B over 20 days; the latest reported day was a $41.9M outflow. The Coinbase premium was reported negative for 51 days, a sign of weaker US-market demand relative to other venues. These do not prove that ETF flows caused each price leg, but together they point to a persistent demand headwind. The market has not yet shown clear evidence that buyers are absorbing it. Futures tell a more nuanced story. Perpetual open interest is $16.9B across the tracked venues; OKX open interest is down 10.6% over 7 days. That is evidence of deleveraging on OKX, not proof that leverage fell by the same amount everywhere. Weighted funding is only +0.002% per 8 hours, so longs are paying shorts, but not at an obviously extreme rate. Retail accounts remain long-heavy at 3.08, while top-trader position ratio is 0.88. That split warns against reading one positioning statistic as the whole market. No reliable CVD, order-book imbalance, or liquidation-level data is available, so claims about a particular liquidation cluster or a futures-led cascade would go beyond the evidence. The macro backdrop may matter more than isolated crypto headlines. A recent report attributed the decline to changing Fed-rate expectations rather than the Binance hack; that is an attributed explanation, not proof of causation. Meanwhile, the reported 75 BTC moved from a long-dormant wallet and Bitdeer’s sale of 256.1 BTC are small relative to BTC’s market, and the data does not show either transfer reaching an exchange or being sold. They are worth monitoring, not treating as the driver. On-chain readings are mixed. Transactions are down 33.4% over 30 days and miner revenue down 30.7%, while active addresses are nearly flat, off 0.5%. That suggests softer activity, but it does not by itself establish a sudden loss of network confidence. Supply is 95.8% issued, with no scheduled token unlock; the next difficulty adjustment is expected to be lower, which affects miner economics rather than the supply cap. For the next stage, the key question is whether $66,450 holds on a completed hourly close. A break followed by a failed retest would strengthen the downside case toward the broader daily support near $62,522. If support holds, a rebound is plausible, but reclaiming roughly $68,500–$70,025 and holding it would be more convincing than an oversold bounce alone. What would change my read most: ETF flows improving, US demand recovering, and spot buying showing up alongside any reclaim. Until then, both the downside continuation and a sharp countertrend bounce remain credible risks #IMPACTbyTrade
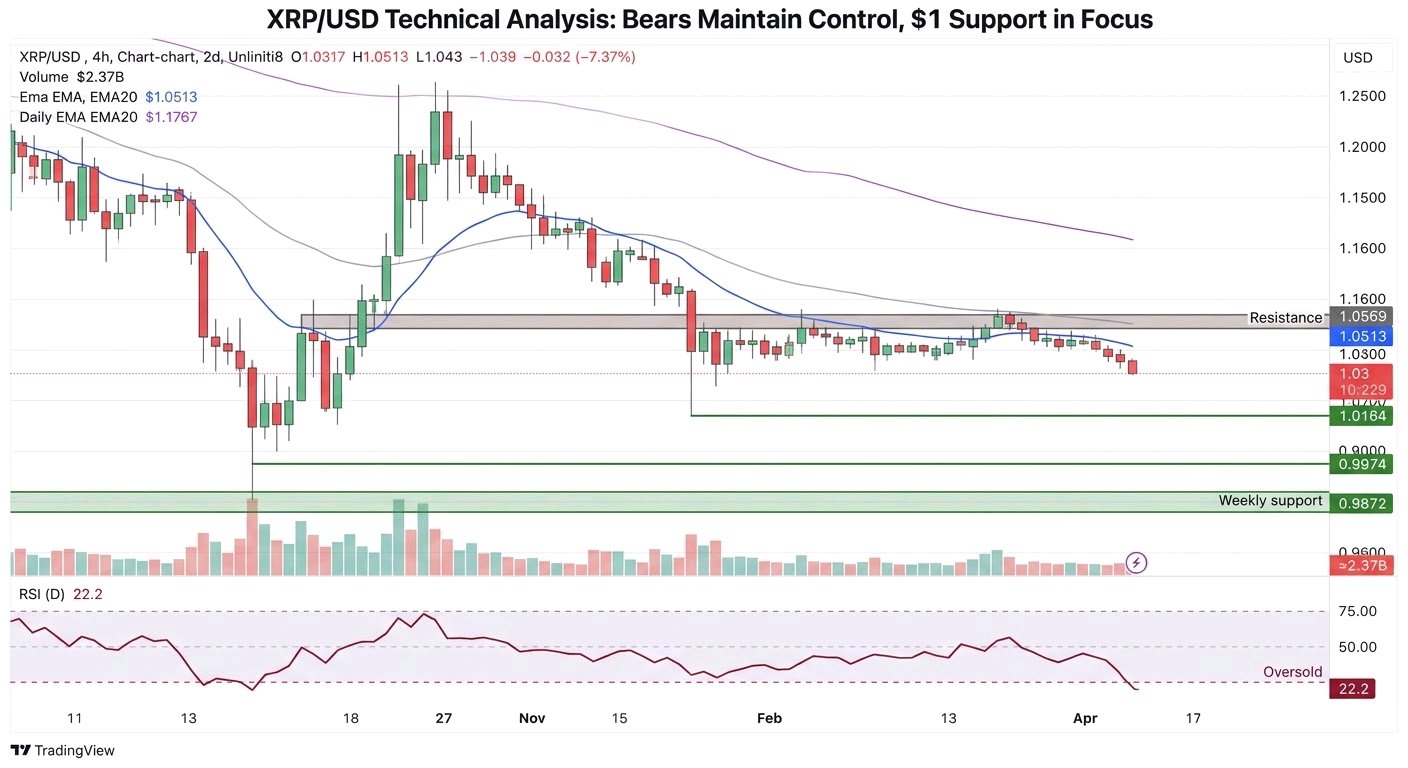
$XRPUSDT is trading near $1.03 after a sharp seven-day decline of about 13%. The important question is not simply whether it is “oversold.” It is whether buyers are absorbing supply or merely pausing the sell-off. The verified structure remains weak. Price is below the 4-hour EMA20 at $1.0513 and far below the daily EMA20 at $1.1767. The daily RSI is 22.2, which shows heavy selling pressure, but it does not prove that a durable bottom is forming. On the 4-hour chart, XRP has repeatedly struggled around $1.04–$1.0569. A sustained close above that zone, followed by a successful retest, would be the first credible sign that sellers are losing control. Without that, the recent bounce looks more like short covering or bargain hunting inside a larger downtrend. The main downside zones are $1.0164, $0.9974, and then the broader weekly support near $0.9872. The $1 area matters psychologically and technically. It has already attracted buyers, but one defense is not enough evidence of accumulation. If price breaks below $0.9974 and cannot quickly reclaim it, stops and leveraged long positions could add pressure. Conversely, a quick reclaim after a brief breakdown would suggest a liquidity sweep rather than genuine structural damage. Derivatives provide a useful warning, although not a complete liquidation map. Perpetual open interest is about $707M across the tracked venues. Funding is positive at roughly 0.009% per 8 hours, meaning longs are paying shorts. Retail accounts are long-heavy, with an OKX long/short account ratio of 2.72, while top-trader positions lean short at 0.87. This combination suggests that late longs remain vulnerable, but it does not tell us exactly where liquidation orders sit. Open interest has fallen 8.7% over seven days on OKX, so some leverage has already left the market. The recent 24-hour increase may represent new longs, new shorts, or both. Price behavior after that increase is the key clue. Spot turnover is large, around $2.37B over 24 hours, but high volume alone does not reveal net buying. The available data does not confirm CVD, order-book imbalance, whale exchange flows, or reliable liquidation clusters. That is an important limitation. Traders should not assume that a visible support level or liquidation pocket must produce a reversal. The broader backdrop is also unfriendly. ETF flows were negative by $10.6M over five days and $8.28M over 20 days. XRPL stablecoin supply fell 25.3% and TVL declined 22.5% over 30 days. These are signs of weakening marginal liquidity, although ETF outflows could partly reflect fund rotation rather than outright institutional rejection. RLUSD growth is a constructive ecosystem development, but there is no verified evidence yet that it is creating immediate XRP demand. My current interpretation remains cautious and bearish below $1.0569, but the daily RSI leaves room for a violent relief rally. The decisive questions are: can XRP reclaim $1.044 with expanding spot participation, or does rising open interest meet another failure? Does $0.9974 hold on a retest? And if it breaks, is the move forced liquidation—or the beginning of a deeper repricing? #IMPACTbyTrade
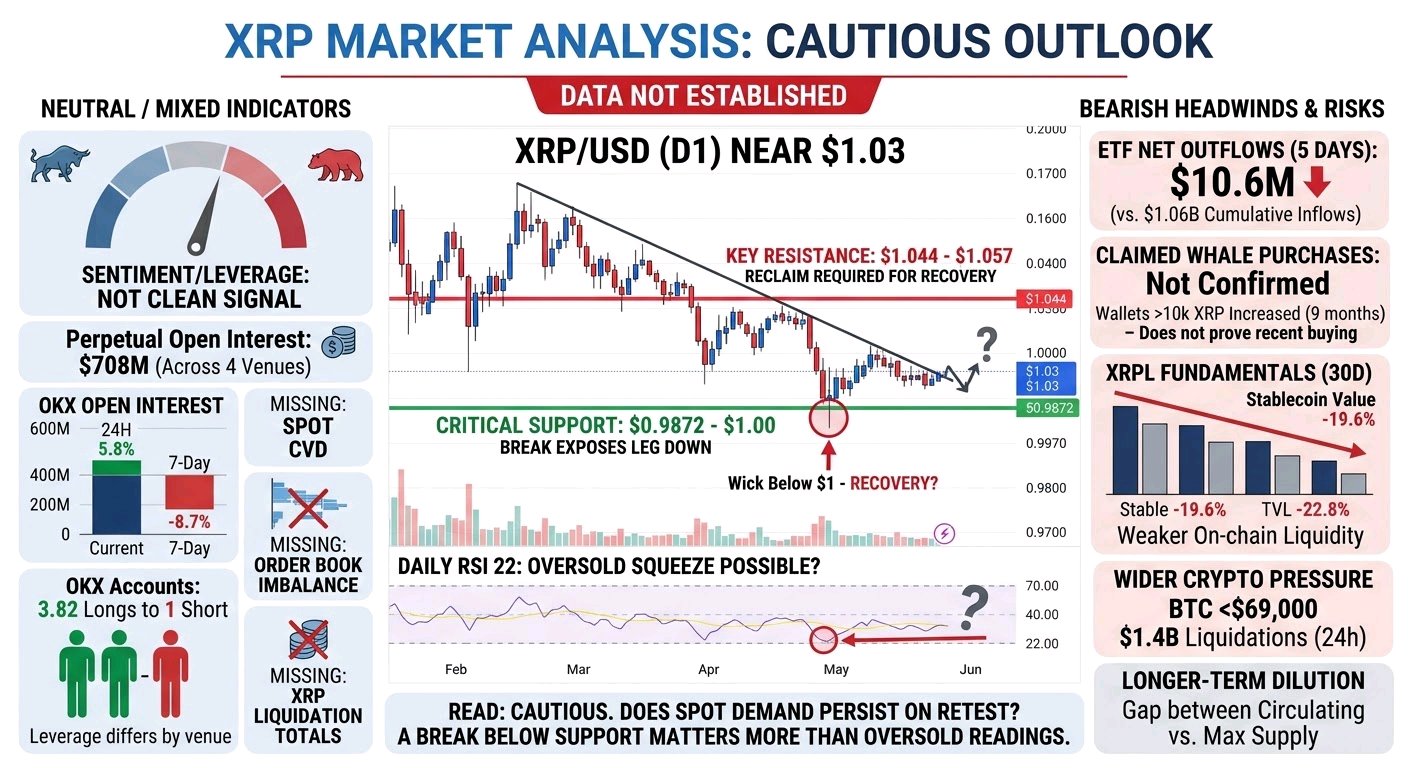
$XRPUSDT is caught between a possible oversold bounce and a market still behaving like a downtrend. It trades near $1.03, down 13.7% over 7 days. The wider crypto market is under pressure too: Bitcoin fell below $69,000, and reported liquidations reached $1.4 billion in 24 hours. XRP briefly dipped below $1 before recovering. That matters, but does the rebound show buyers stepping in—or only a pause after forced selling? The available data does not establish which. The facts are mixed. Perpetual open interest is about $708 million across 4 venues. OKX open interest is up 5.8% in 24 hours, but down 8.7% over 7 days. Funding is close to neutral overall, while OKX accounts show 3.82 longs for every short; top traders’ positions, however, are net short. That is not a clean market-wide positioning signal. It suggests leverage and sentiment differ by venue and trader group. We also lack verified XRP-specific liquidation totals, spot CVD—a running measure of aggressive buying versus selling—or order-book imbalance. High spot volume alone cannot tell us whether buyers are absorbing supply. ETF flows offer another headwind: about $10.6 million of net outflows over 5 days, despite roughly $1.06 billion in cumulative inflows since tracking began. Wallets holding at least 10,000 XRP have reportedly increased over 9 months, but that does not prove recent net buying or show whether large holders are moving coins to exchanges. The claimed whale purchases therefore remain a possibility, not confirmed evidence that they offset ETF selling. The price levels matter because they distinguish a bounce from an actual change in behavior. $0.9872–$1.00 is the key support area; a decisive break would weaken the case that buyers are defending the lows and could expose the market to another liquidation-driven leg down. Above, $1.044–$1.057 is the first meaningful resistance zone. A sustained reclaim, rather than a quick wick through it, would make an oversold recovery more credible. It could open room toward $1.11–$1.18, but that would still be a countertrend move, not proof the broader trend has reversed. The technical backdrop remains heavy: daily RSI is around 22, which raises the chance of a squeeze, while daily and weekly trends remain down. On the fundamentals side, XRPL stablecoin value fell 19.6% over 30 days and TVL fell 22.8%. Those figures suggest weaker on-chain liquidity, though they do not establish the cause of XRP’s price decline. A December 3 ledger fix is announced, but there is no evidence yet of a direct market impact. No near-term token unlock was identified; the large gap between circulating supply and maximum supply is a longer-term dilution consideration, not an immediate catalyst. My read is cautious, not decisively bearish: support has held so far, but the stronger proof would be spot demand lifting price through resistance. Does buying persist on a retest, and do ETF flows improve? If not, a break below $0.9872 would matter more than oversold readings.#IMPACTbyTrade
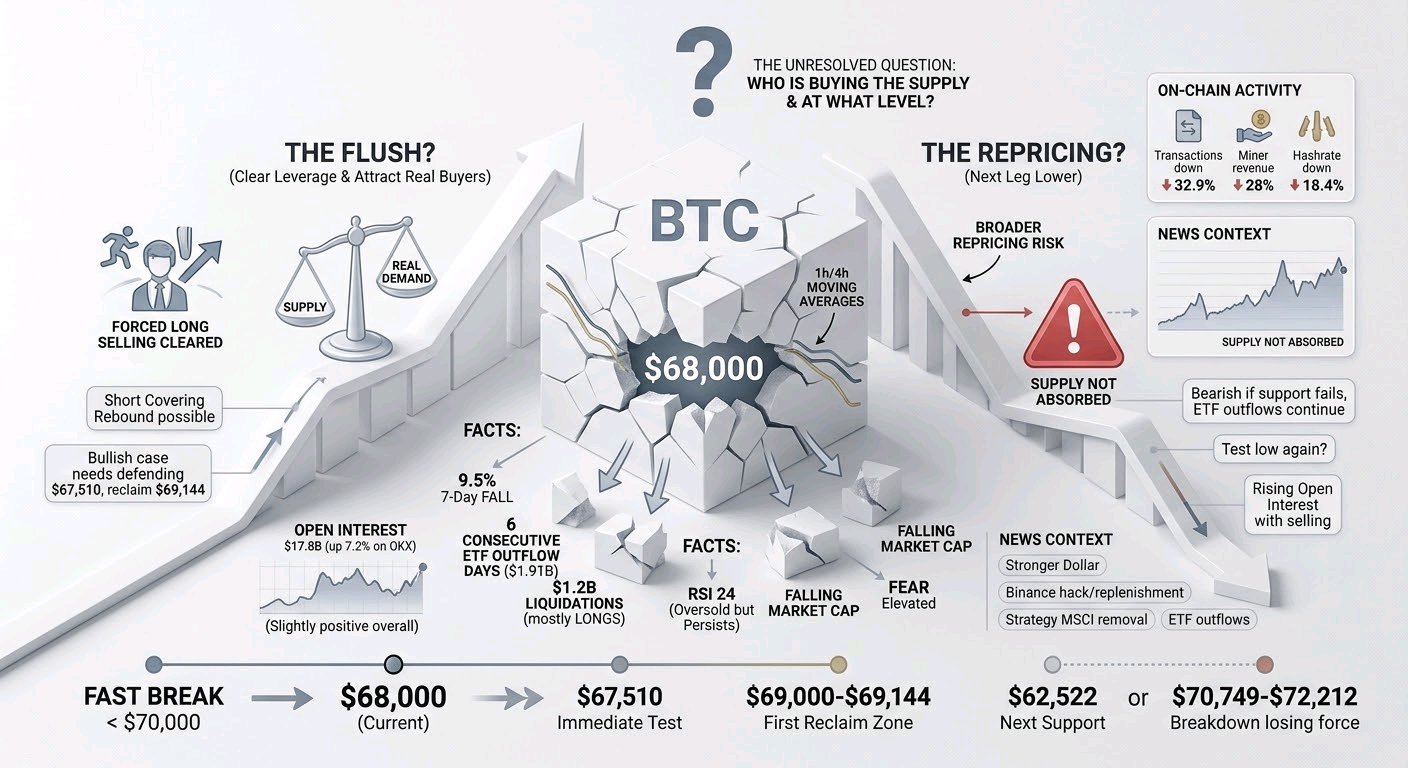
$BTCUSDT is near $68,000 after a fast break below $70,000. The important question is whether this is a flush that clears leverage and attracts real buyers—or the next leg of a broader repricing. The evidence supports both possibilities, but it does not yet show a confirmed turn. Verified facts: BTC has fallen about 9.5% in 7 days. Recent hourly candles show a sharp drop from the $71,000 area, a weak bounce that failed below $69,144, and a fresh low near $67,510. Price remains well below declining 1-hour and 4-hour moving averages. Daily RSI is around 24, an oversold reading, but oversold conditions can persist during a strong downtrend. Spot ETF flows were negative by $1.06B over 5 days and $1.91B over 20 days, with 6 consecutive outflow days. Reports put 24-hour liquidations above $1.2B, mostly from leveraged longs. Fear is elevated, while broad crypto market capitalization also fell sharply. My interpretation: forced long selling likely accelerated the decline, but liquidations are an amplifier, not a complete explanation. The persistent ETF withdrawals are a more meaningful demand warning: if that supply is not being absorbed, a bounce may struggle. Yet the flow picture is incomplete. Aggregate spot volume is substantial, but we lack reliable CVD, exchange-level buyer/seller data, and order-book depth. So claims that small traders are buying while large holders sell remain reports, not independently confirmed evidence of who is setting the marginal price. Derivatives are not giving an uncomplicated “washed out” signal. Open interest across tracked venues is about $17.8B, and OKX’s 7-day open interest is up 7.2%. Funding is only slightly positive overall, with some venues near zero or slightly negative. That suggests the market has not uniformly flipped to crowded shorts; it may also mean leverage is rebuilding while price remains weak. The numbers are venue-specific, and they do not reveal the full liquidation map. A cluster of stops can accelerate a move, but it does not guarantee a reversal at that level. The immediate test is $67,510, the latest low. If price breaks it, then cannot reclaim it, sellers may still control the tape; $62,522 is the next prominent daily support in the available structure. But after such a steep fall, short covering could produce a sharp rebound without changing the larger trend. On the upside, $69,000–$69,144 is the first reclaim zone. A sustained move above it would improve the short-term picture; acceptance back above the declining hourly averages near $70,749–$72,212 would be stronger evidence that the breakdown is losing force. A brief wick above resistance would not be enough. News offers context, not a proven single trigger. Reports cite a stronger dollar, ETF outflows, and leveraged liquidations. Binance says it replenished customer assets after the reported hack, though independent verification remains a question; the announcement alone does not establish BTC selling pressure. Strategy’s announced removal from MSCI indexes may affect its shares and related flows, but direct BTC impact is uncertain. On-chain activity is softer: transactions are down 32.9% and miner revenue 28% over 30 days, while hashrate fell 18.4%. These are relevant signs of weaker activity and mining economics, but not proof of imminent miner selling. My view: the daily and 4-hour structure remains bearish, while oversold momentum makes chasing the breakdown risky. The bullish case needs buyers to defend $67,510, reclaim $69,144, and show sustained spot demand. The bearish case strengthens if support fails, ETF outflows continue, and rising open interest accompanies renewed selling. The unresolved issue is absorption: who is buying the supply, and can they keep doing so if price tests the low again?#IMPACTbyTrade
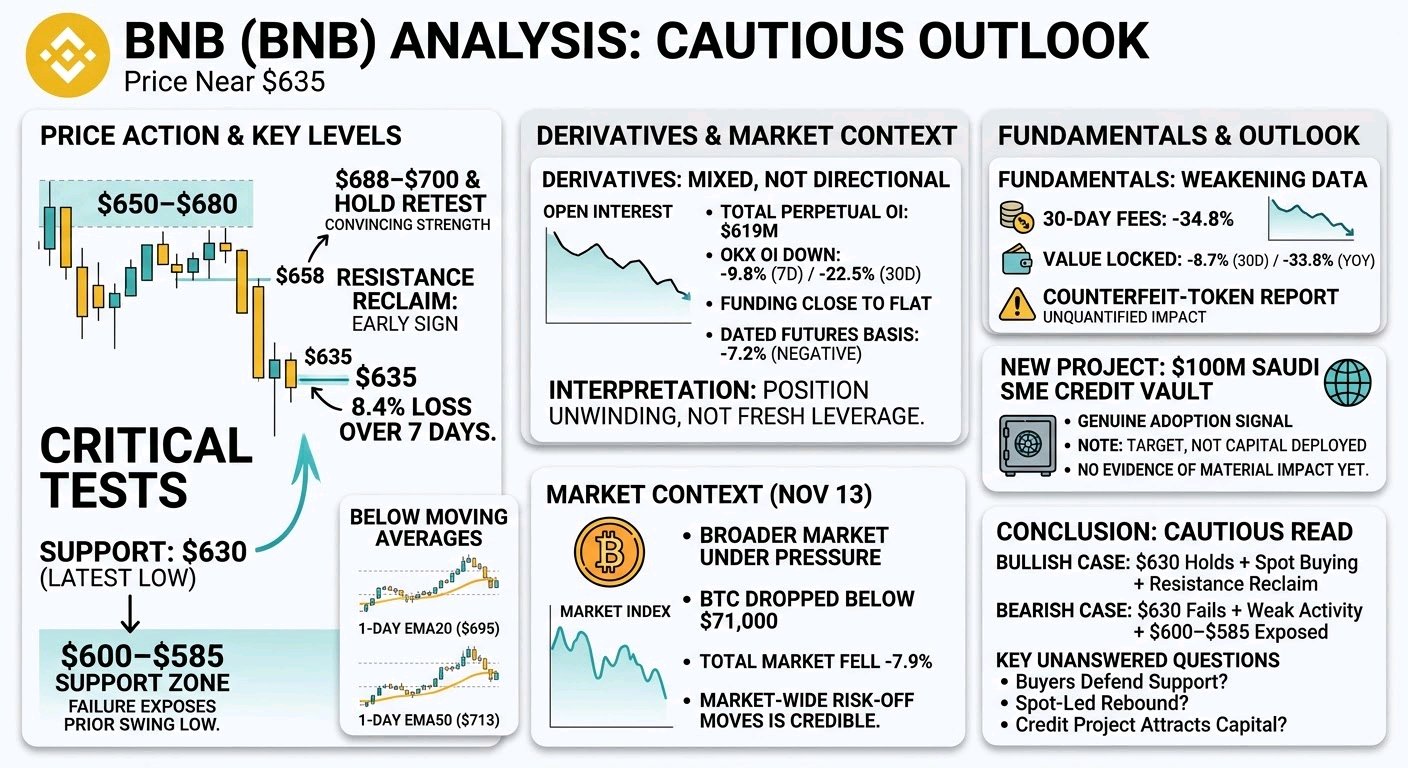
$BNBUSDT BNB is near $635 after losing 8.4% over 7 days. The important point is not simply that price is down; it is that selling has pushed it below the recent $650–$680 area while the broader market is under pressure. On Nov. 13, the whole market fell 7.9%, and Bitcoin dropped below $71,000. That makes a market-wide risk-off move a credible explanation for the timing. But it does not explain all of BNB’s weakness: BNB has also fallen 14.8% over 30 days, and the available data cannot separate market beta from coin-specific selling. The immediate test is $630, the latest low. If it gives way, the next meaningful support zone is around $600–$585, including a prior swing low. Holding $630 could produce a relief bounce, but I would not call that a structural turn by itself. Price remains well below its 1-day EMA20 at about $695 and EMA50 near $713; the weekly averages are also around $693–$694. A reclaim of $658 would be an early sign of stabilization. A stronger change would require price to recover the $688–$700 area and hold it on a retest. What would make that move convincing? Spot buying and sustained trading activity—not just a thin bounce or a short-lived squeeze. The derivatives picture is mixed, but not strongly directional. Perpetual open interest is $619 million; OKX open interest is down 9.8% over 7 days and 22.5% over 30 days. Funding is close to flat, while dated futures basis is negative at −7.2% annualised. Falling price alongside falling open interest is consistent with positions being unwound, rather than fresh leverage driving the decline. Yet OKX accounts still lean long, while top-trader ratios are below 1. Those are venue-specific measures, not a market-wide verdict. We do not have reliable liquidation levels, CVD, order-book imbalance, or whale and exchange flows, so claims about a forced-long flush or a major buyer stepping in would be speculation. Fundamentals do not yet provide a clear counterweight. BNB Chain’s 30-day fees are down 34.8%; value locked fell 8.7% over 30 days and 33.8% year over year. The announced Saudi SME credit vault, targeting $100 million, is a genuine adoption signal, but a target is not capital deployed, and there is no evidence yet that it has materially changed BNB demand. The counterfeit-token report raises a separate trust and user-safety concern; its market impact is unquantified. My read is cautious, not certain. The bullish case is that $630 holds, market stress eases, and BNB reclaims resistance with real spot participation. The bearish case is a break below $630 followed by failure to recover, exposing $600–$585 while activity remains weak. The key unanswered questions are whether buyers defend support, whether any rebound is spot-led, and whether the new credit project attracts actual capital and sustained use.#IMPACTbyTrade
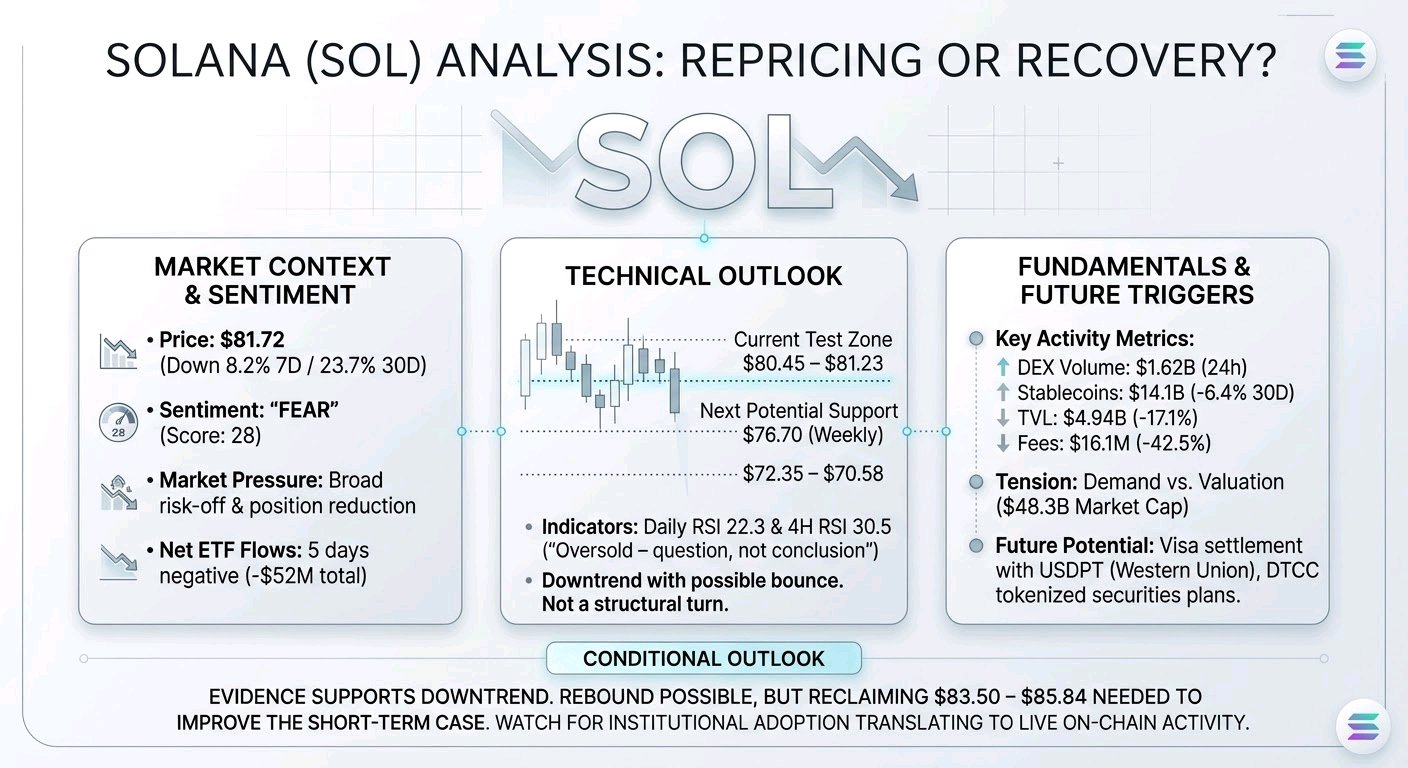
$SOLUSDT at $81.72 looks less like a market that has found its footing than one still trying to absorb a sustained repricing. It is down 8.2% over 7 days and 23.7% over 30 days. That weakness is not happening in isolation: the wider market is under pressure, fear has risen to 28 from 50 a week ago, and ETF flows have been negative for 5 straight days, totaling $52 million. The question is whether this is mainly broad risk-off and position reduction—or whether investors are also reassessing Solana’s own growth and value capture. The immediate price test is $80.45–$81.23. SOL has repeatedly traded around this area, but the available candles do not yet show a sustained reclaim or a confirmed breakdown. A clean close below $80.45 would put weekly support near $76.70 in view, then $72.35–$70.58. Those are reference zones, not guaranteed bounce points. On the other side, $83.50–$85.84 is the first meaningful resistance band; a break above it that holds on a retest would be more persuasive than a quick wick through. Weekly resistance near $83.98 also matters. Above that, the larger trend remains weak: price is well below the weekly EMA20 at about $95.57 and EMA50 near $104.08. The oversold readings invite a question, not a conclusion. Daily RSI is 22.3 and 4-hour RSI is 30.5, while price sits below the key moving averages on both timeframes. That can precede a sharp relief rally, but it does not by itself prove sellers are exhausted. Recent candles show lower prices and repeated tests of the $80.45 area, with only small rebounds. The evidence supports “downtrend with a possible oversold bounce,” not a confirmed structural turn. For that interpretation to change, I would want to see price reclaim resistance, hold it on a retest, and attract sustained spot participation. Derivatives offer a mixed, but useful, clue. Open interest is $1.86 billion across the reported venues, while OKX open interest is down 3.4% over 7 days and 5.3% over 30 days. Weighted funding is slightly negative at −0.004% per 8 hours. That combination is consistent with some leverage coming out rather than an expanding crowded long. Yet it does not tell us who drove the decline. Long/short account ratios are not the same as position size: accounts lean long, but top-trader positions skew short. Crucially, we do not have verified CVD, order-book imbalance, liquidation prints, or exchange wallet flows here. So claims about a liquidation cascade, whale distribution, or a decisive spot-seller takeover would go beyond the evidence. Broad spot turnover and tight quoted spreads show the market is trading; they do not reveal aggressor direction. The fundamental tension is harder to dismiss. Solana has real activity: $1.62 billion in 24-hour DEX volume and $14.1 billion in stablecoins. But stablecoin balances are down 6.4% over 30 days, fees fell 42.5% to $16.1 million, and locked value fell 17.1% to $4.94 billion. At roughly $48.3 billion market capitalization, valuation remains demanding against current fees and protocol revenue. High transaction activity is not automatically durable value for SOL holders. Is usage broadening into sticky payments and financial activity, or is it mostly episodic trading that fades with market appetite? There are genuine adoption positives, but timing matters. Visa’s reported settlement use of Western Union’s Solana-based USDPT and DTCC’s plan for eligible tokenized securities in the second half of 2027 could support future usage. Neither announcement yet demonstrates material on-chain fees, SOL demand, or an immediate change in flows. Meanwhile, ETF outflows are a measurable near-term headwind. The key test is whether these institutional plans become live activity—and whether activity translates into stronger economics. My view is deliberately conditional: the oversold market can rebound, but the evidence available does not justify calling a bottom. A sustained hold above $80.45, followed by a volume-supported reclaim of $83.50–$85.84, would improve the short-term case; a decisive break lower would keep $76.70 and then $72.35–$70.58 relevant. What would change the broader picture? Persistent ETF inflows, improving fees and locked value, and spot-led advances rather than leverage-led squeezes. The unanswered questions are whether buyers will defend support, whether selling is mostly deleveraging or fresh distribution, and whether Solana’s institutional pipeline can produce measurable value capture before the market loses patience.#IMPACTbyTrade
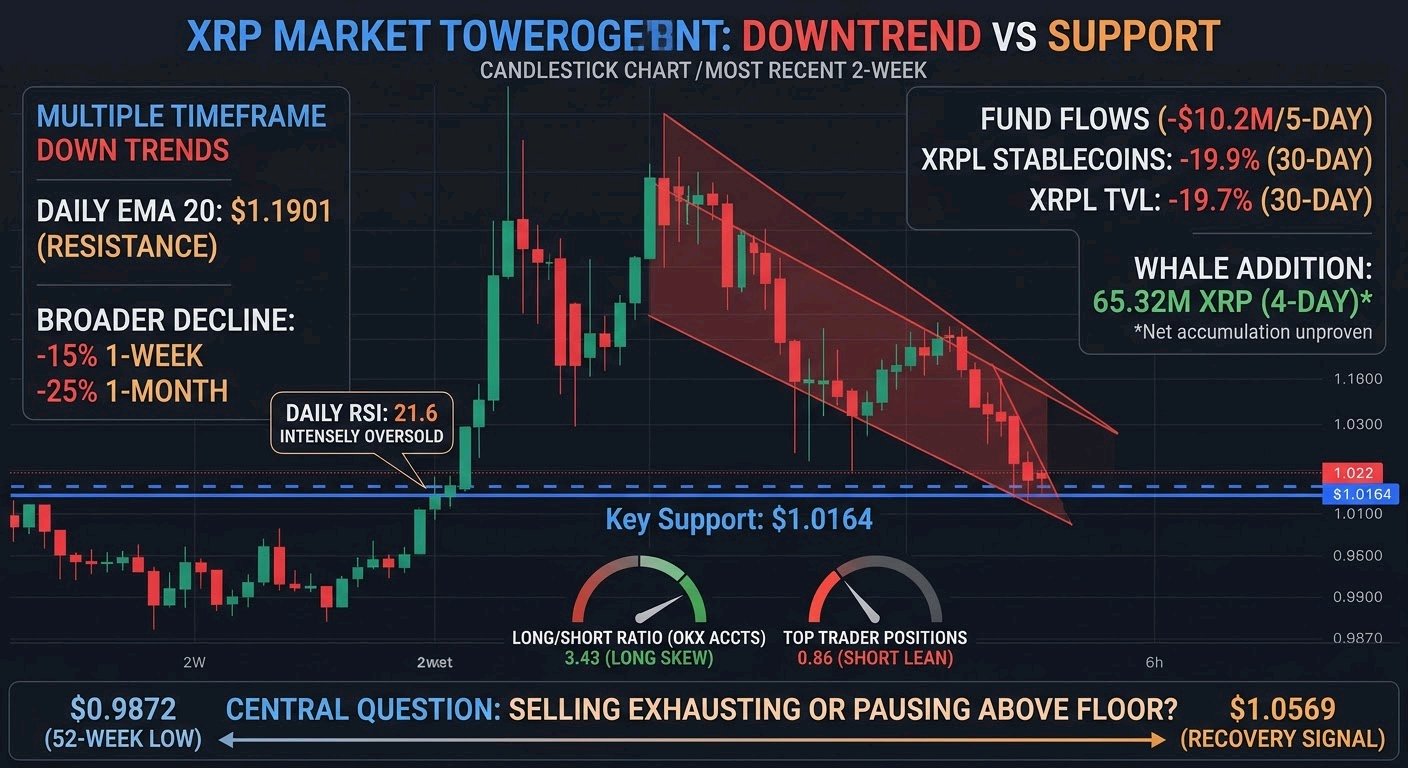
$XRPUSDT XRP is caught between a clear downtrend and a support level that has not yet broken. That distinction matters: the bearish case is stronger on the broader evidence, but a breakdown is not confirmed. At the latest snapshot, XRP was around $1.02, down 2.78% from the prior daily close. The question for the next few days to 2 weeks is whether selling can push it through $1.0164, or whether oversold conditions and buying near the lows produce a relief bounce. Verified market facts: The hourly, 4-hour, daily and weekly trends are down. XRP is below its shorter-term moving averages; the daily EMA20 is $1.1901, far above the current price. The last 6 closed hourly candles all finished above $1.0164. Price did wick to that level, then closed at $1.0274 before slipping to $1.0245. That is weak price action, but not a confirmed close below support. If $1.0164 fails, the next notable level is $0.9872, the 52-week low. The broader decline is substantial: XRP is down about 15% over 1 week and 25% over 1 month in the market snapshot. Daily RSI is 21.6; hourly RSI is about 29. These readings show intense selling and raise the chance of a reflex bounce. They do not tell us the decline is over. What would change the picture? A sustained recovery through $1.0569–$1.0654 would be a more meaningful sign than a single intraday bounce. A daily trend reversal would require much more. What may be driving the pressure: The reported US spot-fund flows were -$10.2M over 5 days, although the latest session recorded a modest $370K inflow. XRPL stablecoin supply fell 19.9% over 30 days, and value locked declined 19.7%. These are real headwinds to the near-term demand story, but they are not proof that ETF redemptions or XRPL activity directly caused each sell-off. Fees rose 23%, yet from only $42.3K over 30 days—too small, in my view, to offset the contraction in stablecoins and value locked. Whale activity is the main conflicting claim: a news report said large holders added 65.32M XRP over 4 days. But that figure does not establish net buying from outside wallets or withdrawals from exchanges. XRP fell sharply during the same period. Are these holders accumulating, moving tokens between wallets, or simply failing to absorb the available selling? The evidence provided cannot settle that. Futures and liquidity: Perpetual open interest is reported at $717M across 4 venues. The available venue-specific history is mixed: OKX open interest fell 8.7% over 7 days, then rose 5.8% in 24 hours. Funding is slightly positive overall at 0.003% per 8 hours, meaning longs pay shorts, but the rate is modest and Bybit funding is negative. OKX accounts skew long at 3.43, while top traders’ positions ratio is 0.86, a short lean. That split suggests vulnerability on both sides, not a clean crowded trade. We do not have reliable CVD, order-book imbalance, aggregate futures-volume changes or liquidation totals. So we cannot say whether spot sellers led, whether falling open interest reflects forced liquidations, or where a squeeze might occur. Reported spot turnover is $1.71B across many venues, but turnover alone does not reveal who was the aggressive buyer or seller. My read is bearish but conditional, not certain. Broad weakness, negative recent fund flows and declining XRPL liquidity argue against assuming the low is in. Yet support has held on hourly closes, and oversold momentum makes chasing the decline hazardous. I would watch for an hourly close below $1.0164, then whether price follows through toward $0.9872. If support holds and price reclaims $1.0569, the breakdown thesis weakens. The evidence still leaves one central question open: is selling pressure exhausting, or merely pausing above the floor?#IMPACTbyTrade
$DOGEUSDT looks less like a market that has found a floor than one testing whether a floor exists at all. The distinction matters. Price is near $0.0647 after falling 12.8% in 7 days and 23.5% in 30 days. That decline has happened alongside broad risk aversion—the total crypto market is down 5.2% over 24 hours and the fear-and-greed reading has dropped to 28 from 50 a week ago. But DOGE has been weaker than the market, so macro pressure alone may not explain the move. What is verified: The latest intraday low is about $0.0645, also the bottom of the recent 1H and daily ranges. DOGE is below declining moving averages on the 1H, 4H and daily charts. The daily EMA20 is around $0.0732; on the 4H chart, the EMA20 and EMA50 sit near $0.0682 and $0.0704. RSI is oversold—26.6 daily and 21.2 on the 1H—but that measures recent momentum, not whether buyers have returned. The latest candles show a sharp move down and only a small bounce. No confirmed reversal or successful support retest is visible. That makes $0.0645 the immediate test, not a proven support zone. If DOGE holds above it and starts making higher lows, the market may be absorbing selling. If it breaks and closes below, the current “potential base” interpretation weakens; the available data do not establish a reliable next support. Above price, $0.0675–$0.0689 is the first resistance area, followed by roughly $0.0696–$0.0717. Reclaiming those levels would matter more than a brief oversold bounce. A sustained move above $0.0732 would be a stronger sign that the daily trend is changing. The derivatives data are mixed. Tracked perpetual open interest is $376M across 4 venues, while broader venue coverage reports $929M across 83; these are different coverage sets, so they should not be combined. On OKX, open interest fell 9.2% over 7 days. That fits a possible reduction in leveraged exposure during the selloff, rather than fresh conviction building behind it. Funding is mildly negative, and dated futures basis is deeply negative at about -20.9% annualised. Those readings indicate weak futures demand, but they do not tell us whether shorts are initiating positions or longs are exiting. Nor do we have verified liquidation levels or a liquidation heatmap. It would be a mistake to assume a crowded short position means a squeeze is imminent. Positioning adds another wrinkle: OKX long/short accounts are near 5:1, yet top traders’ position ratio is 0.74. Account counts suggest many more long than short accounts, but the position ratio says larger traders may be tilted the other way. Which signal matters more? Without actual liquidation and order-flow data, neither gives a clean answer. Spot turnover is substantial at $867M across 63 venues, but 30% is concentrated on one venue. Turnover is not net buying; we lack spot CVD, order-book imbalance and reliable evidence of whale accumulation or exchange outflows. There is a possible catalyst, but it is still a claim to verify against delivery. DogeOS has been described as “very, very close” to launch, with more than 100 builders reportedly involved, but no date was given. That could create new utility; it has not yet demonstrated sustained DOGE demand. Reports also put spot ETF flows at zero from Oct. 14 to Nov. 10. DOGE’s entire 157B supply is already circulating, but issuance continues at roughly 5B coins a year. Long-term buyers still need to absorb that supply, and trading volume alone does not prove durable demand. Recent headlines also linked market weakness to inflation concerns; they establish a possible backdrop, not DOGE-specific causation. My read is cautious, not a call that DOGE must fall. The bullish case needs $0.0645 to hold, then a reclaim of resistance supported by spot buying and improving price structure. The bearish case is a decisive break below the low, especially if DOGE continues to underperform the broader market. The key questions are whether buyers actually defend support, whether futures positioning stabilises alongside spot demand, and whether DogeOS delivers measurable use rather than just anticipation.#IMPACTbyTrade
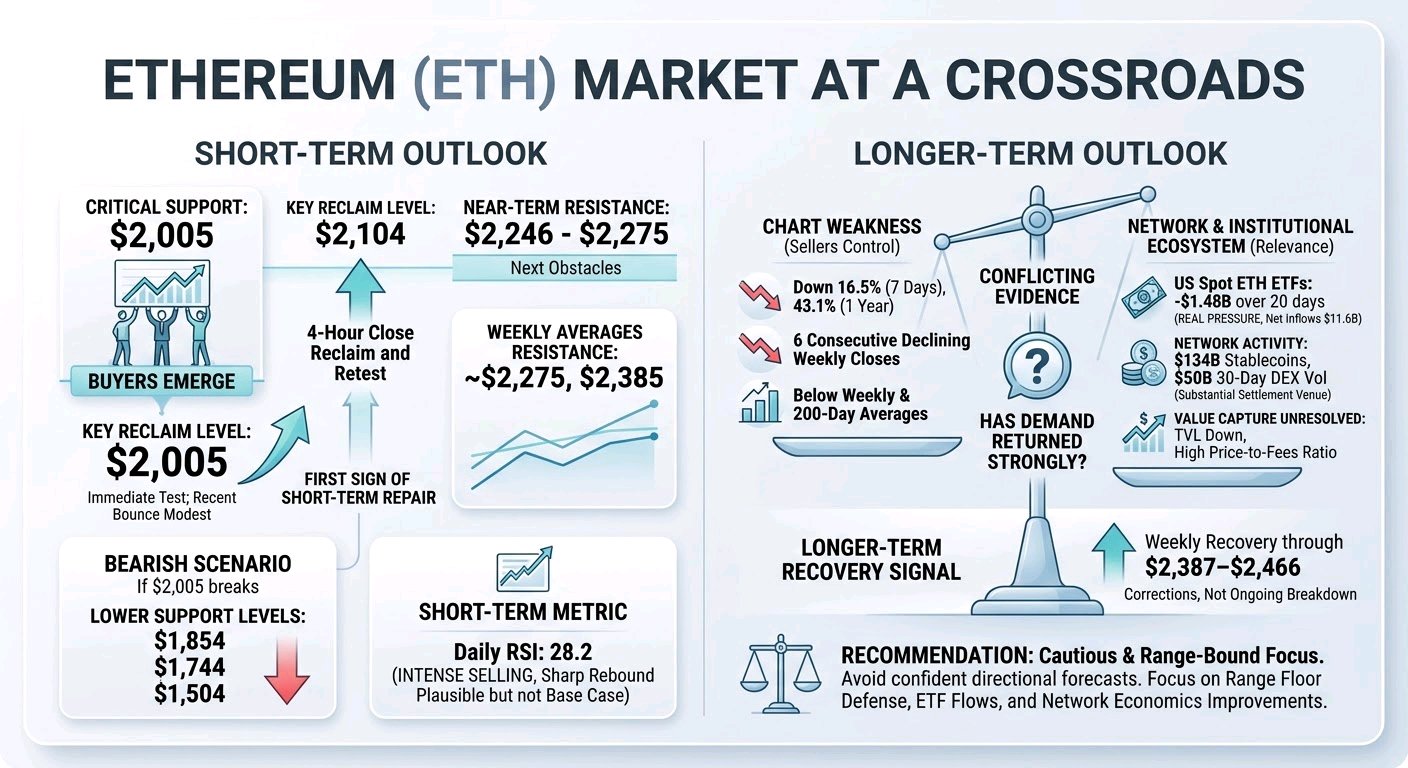
$ETHUSDT around $2,022 is a market caught between two different kinds of evidence: the chart says sellers still have control, while the network and institutional ecosystem say Ethereum remains relevant. Neither side has settled the question. For the next 6–12 months, I would focus less on whether ETH is “cheap” after its fall and more on whether demand returns strongly enough to defend the range floor. The immediate test is $2,005. ETH touched that area and bounced only modestly; the latest daily low was $2,013. That makes $2,005 more than a round number: it is the point where recent buyers have so far appeared. If price holds and then reclaims $2,104 on a 4-hour close, with a successful retest, the first sign of short-term repair would be in place. It would not prove a new uptrend. The next obstacles are around $2,246–$2,275, then the weekly averages at approximately $2,275 and $2,385. The broader chart remains weak. ETH is down 16.5% in 7 days and 43.1% over 1 year, with 6 consecutive declining weekly closes. Price is below both weekly averages and the 200-day average. Daily RSI is 28.2, which tells us selling has been intense; it does not tell us sellers are finished. My observation is that this creates room for a sharp rebound, but not yet a reason to treat one as the base case. If $2,005 breaks decisively, the next substantial support is near $1,854. Further down, weekly levels sit around $1,744 and $1,504. A move toward those levels would not be surprising in a weak market, but the available evidence does not establish that they must be reached. On the other hand, a weekly recovery through $2,387–$2,466 would matter because it would take ETH back above key resistance and make the recent decline look more like a correction than an ongoing breakdown. Positioning does not give a simple answer. Perpetual open interest is about $11.5B across the tracked venues, while OKX open interest fell 12.7% in 7 days. That decline suggests some leverage has been reduced during the selloff. Funding is still slightly positive at 0.004% per 8 hours, so longs continue to pay shorts. That is a modest headwind, not evidence of an extreme long crowded trade. OKX accounts lean long, while top traders’ positions lean short. These are partial snapshots, and there is no verified liquidation map or order-flow evidence here to show exactly where forced selling might be concentrated. I would avoid reading the open-interest decline as proof that selling pressure is exhausted. Spot participation is similarly hard to interpret from volume alone. Reported 24-hour spot volume is about $9.1B, but that does not reveal whether buyers are absorbing supply or simply trading into it. ETF flows offer a clearer near-term demand signal: US spot ETH funds lost $524M over 5 days and $1.48B over 20 days, including $145M on November 11. That is real pressure. Cumulative inflows remain about $11.6B, so institutional access and an existing investor base are established; what remains uncertain is whether those investors are still adding or now reducing exposure. Ethereum’s usage is meaningful, but value capture is the unresolved part. The chain has $134B in stablecoins and $50B of DEX volume over 30 days. Those figures support the case that Ethereum remains a substantial settlement venue. Yet TVL is down 13.6% in 30 days and 43.2% over 1 year; stablecoin balances also fell 7.6% in 30 days. Annual fees are $175M against a $247B market capitalization, implying a 1,037× price-to-fees ratio. Fees did rise 8.8% against the previous 30 days, but that small improvement has not overturned the larger picture. Does high activity eventually translate into stronger ETH demand and fee burning, or can usage grow without comparable value accruing to the token? The current figures do not answer that. There are constructive institutional developments: Deutsche Bank has launched custody for institutional clients, and Sygnum has opened an ETH-denominated fund targeting 8%–10% annual returns. These expand access, but they do not show how much new capital will arrive. BlackRock’s transfer of ETH to Coinbase Prime is also not, by itself, evidence of a sale. Near term, ETF flow direction and price response matter more than headlines. My view is balanced but cautious: a recovery is plausible, not confirmed. A hold above $2,005 followed by a reclaim of $2,104 would improve the short-term picture; sustained weekly strength above $2,387–$2,466, alongside improving ETF flows and network economics, would make the longer-term case more convincing. A decisive loss of $2,005 would put lower supports back in focus. Until one of those paths is confirmed, the range—not a confident directional forecast—is the most honest way to frame ETH.#IMPACTbyTrade
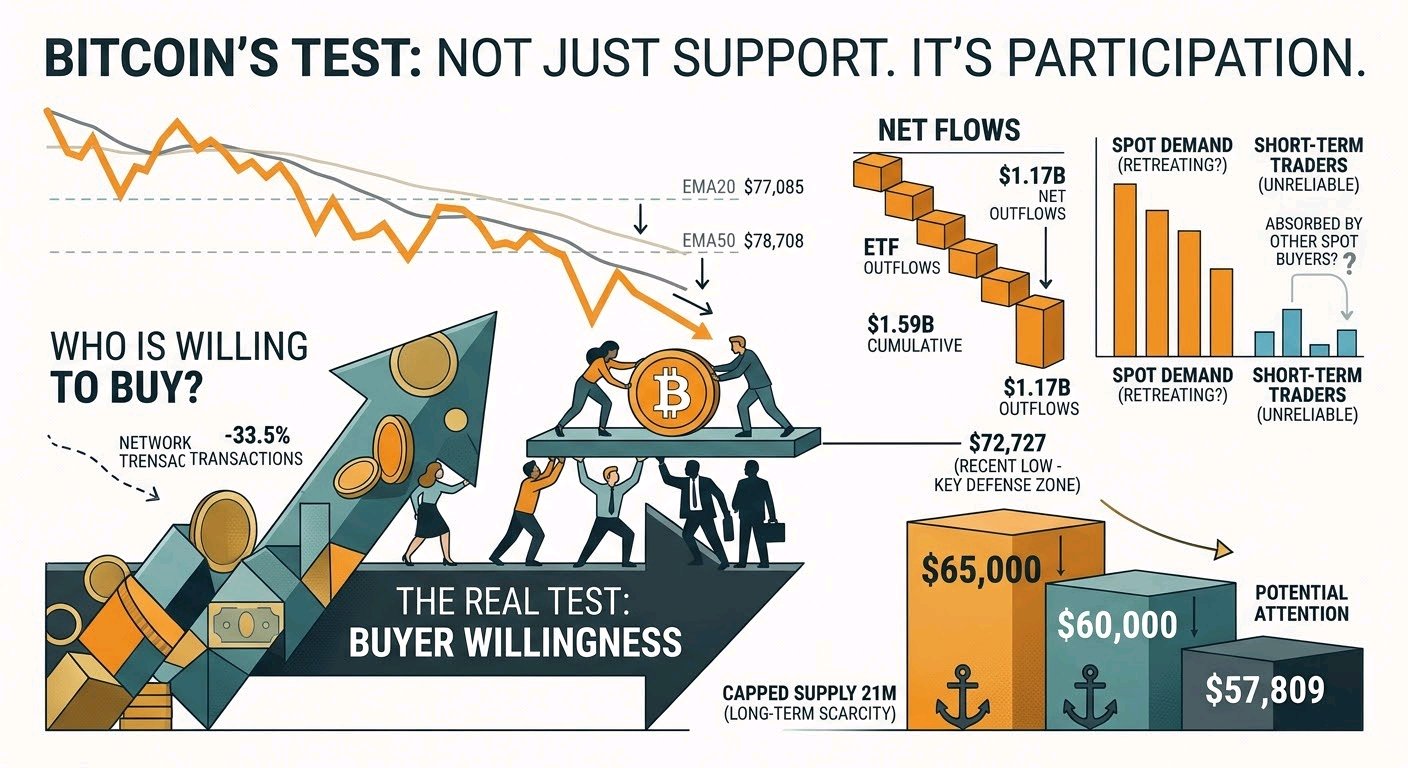
Bitcoin’s Test Is Not Just Support. It’s Who Is Willing to Buy. At about $73,800, Bitcoin is no longer asking whether it can produce a bounce. It is asking a more useful question: who is buying, and are they willing to keep buying when sellers press? That distinction matters. A price can rebound because short-term traders cover positions, yet still remain vulnerable if longer-term spot demand is retreating. The observable evidence is uncomfortable for the bulls. BTC is down 8.4% in 7 days, has closed lower for 6 consecutive weeks, and sits below its daily EMA20 near $77,085 and EMA50 near $78,708. On the weekly chart, it is below both key averages as well. Those levels do not predict the future, but they show that buyers have not yet repaired the trend. The question is not whether BTC can touch resistance; it is whether buyers can hold above it after the first wave of selling returns. The ETF figures make that test more demanding. US spot Bitcoin ETFs recorded $1.17B in net outflows over 5 days and $1.59B over 20 days, with outflows on 5 consecutive days. The cumulative $55.4B of inflows since 2024 tells us that the products once drew substantial demand. It does not tell us that investors are returning now. Are ETF redemptions being absorbed by other spot buyers? The available data do not establish that. Without clear evidence of stronger spot demand, a bounce alone cannot answer the question. That is why $72,727, the recent low, matters. It is the nearest visible test of buyers’ willingness to defend price—not a magic floor. BTC has traded near it and recovered, but that response has not carried price back above the key moving averages. A firm break below the low would shift attention to the longer-term support areas at $65,000, $60,000 and $57,809. A quick dip and recovery would tell a different story: sellers pushed through, but buyers absorbed the supply. The quality of the response matters as much as the level itself. For the recovery case, the first challenge is $76,000–$76,400, where weekly resistance and the weekly EMA20 converge. Next comes $82,842. Reclaiming either area would be more meaningful if accompanied by improving ETF flows and genuine spot buying. Why? Because rising prices without fresh spot demand can leave the market dependent on leveraged traders, who may leave quickly when momentum turns. Futures offer neither a clear alarm nor reassurance. Perpetual open interest was $18.9B across 4 venues, while OKX open interest was almost unchanged over 7 days, up 0.3%. Funding was mildly positive at +0.008% per 8 hours, so longs were paying shorts, but the rate was not extreme. Account positioning leaned long while top-trader positioning leaned short. That conflict makes it hard to call the market one-sided. And without verified liquidation totals, claims that a selloff is being driven by a cascade—or that a large liquidation wave is imminent—would go beyond the evidence. There are counterpoints to the demand weakness. A report described some whale accumulation through Nov. 9. But reported accumulation is not enough to call a broad shift: its scale, persistence and destination are unclear. Network transactions also fell 33.5% over 30 days. That signals lower activity, not proof of why BTC fell. Bitcoin’s capped supply of 21M remains a long-term feature, but scarcity does not guarantee short-term buying. So I would frame the market as a test of participation, not a contest between bullish and bearish slogans. The bearish case strengthens if BTC loses $72,727 and spot outflows continue. The recovery case gains credibility if buyers defend that low, flows improve, and price reclaims $76,000–$76,400 with follow-through. Until then, I see a market where sellers have the stronger evidence, but buyers have not yet given up the key nearby test. $BTCUSDT #IMPACTbyTrade
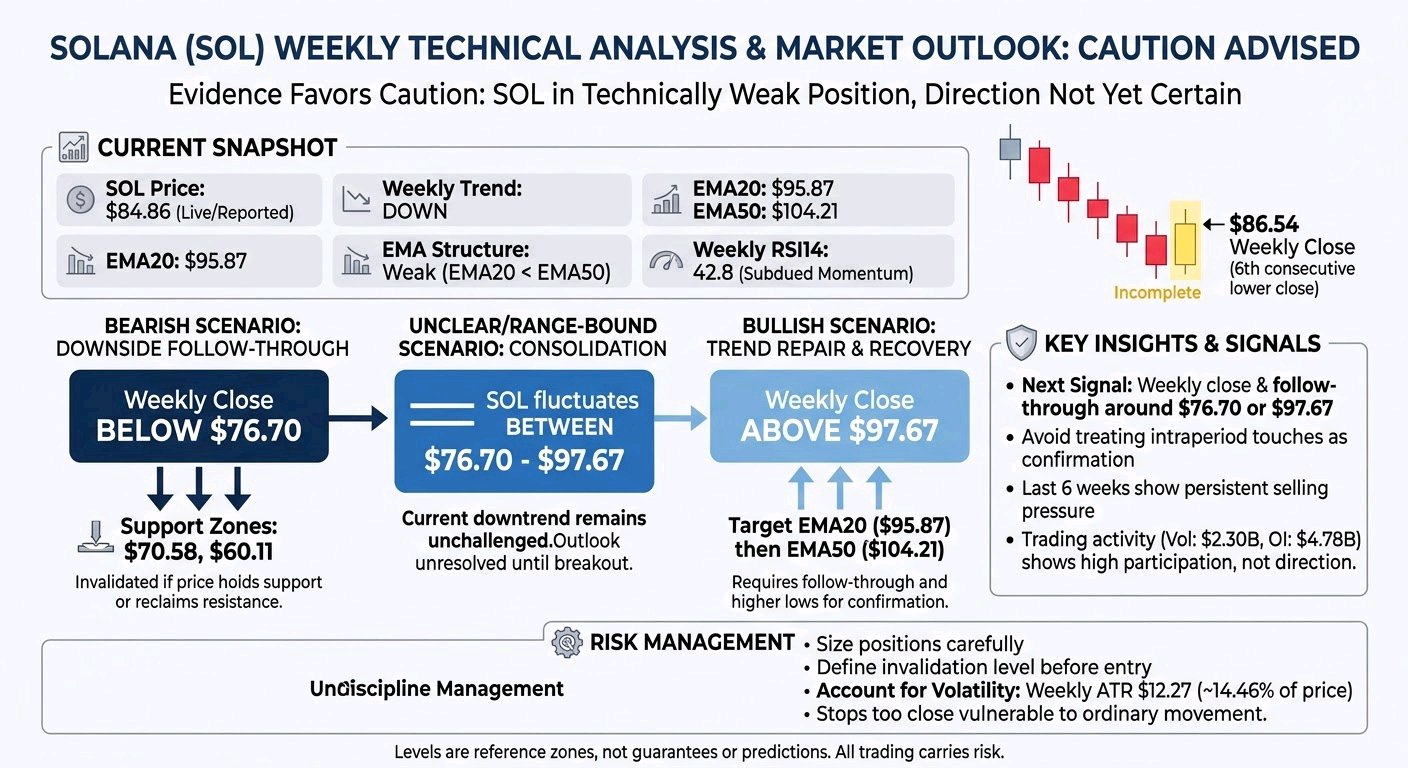
$SOLUSDT The weekly evidence still favors caution: SOL is in a technically weak position, but neither continued decline nor recovery is certain. The key distinction is between a price touching a level and closing above or below it—and then showing follow-through. A single move, especially while the weekly candle is still forming, is not enough to establish a breakout or a trend change. is around $84.86. The last 6 completed weekly candles closed progressively lower, from $121.60 to $86.54, and their highs also generally declined. The latest completed candle closed at $86.54, after reaching $98.16 and falling to $84.98. This sequence supports persistent selling pressure. It does not prove that selling will continue: a short run of candles cannot establish the next move, and the current weekly candle is incomplete. So far it has opened at $86.53, reached $88.46, and fallen as low as $81.23; its final close is not yet known. The broader weekly trend is classified as down. Price is below the weekly EMA20 ($95.87) and EMA50 ($104.21), with the shorter average below the longer one. The monthly trend classification is mixed, a reminder that weekly weakness does not settle the longer-term picture. Weekly RSI14 is 42.8, consistent with subdued momentum, but it is not by itself a reliable signal of either a reversal or further declines. The day’s reported range, $82.30–$85.42, is too short a window to change the weekly assessment. Bearish scenario: Further weakness would gain support if SOL closes a week below $76.70 and cannot reclaim that area. The next reference supports are $70.58 and $60.11. A sustained break below support would be evidence of downside follow-through, not proof that the next support must be reached. This scenario would be weakened if price holds above support and starts reclaiming resistance. A brief dip below a level followed by a close back above it would not, on its own, confirm a breakdown. Bullish scenario: The first meaningful test is a weekly close above $97.67, followed by a hold above that level. That would challenge the sequence of lower closes and place price back above the weekly EMA20, which is nearby. A subsequent reclaim of the EMA50 at $104.21 would provide stronger evidence of trend repair. This scenario would fail to gain confirmation if price is rejected near resistance or closes back below $97.67. Even a confirmed reclaim would not establish a long-term uptrend by itself; follow-through and higher weekly lows would matter. Unclear or range-bound scenario: SOL may hold between support near $76.70 and resistance near $97.67 without resolving direction. In that case, price could fluctuate while the current downtrend remains unchallenged and no new breakdown is confirmed. Repeated closes inside that range would leave the outlook unresolved. A move outside it would matter more if a weekly close and subsequent price action supported the break rather than quickly reversing it. Trading activity gives context, not direction. Reported 24-hour spot volume is $2.30B across 65 venues, while perpetual open interest is $4.78B. These figures show substantial activity and leverage exposure; without comparable historical volume or evidence of positioning shifts, they do not establish accumulation, selling pressure, or the likely direction of a move. Nor do they explain why the price has moved. The next important signal is therefore a weekly close and follow-through around $76.70 on the downside or $97.67 on the upside. Until that evidence arrives, avoid treating an intraperiod touch as confirmation. For risk management, size any position so that a stop-out is tolerable, define the invalidation level before entry, and account for volatility: weekly ATR is $12.27, about 14.46% of the current price. A stop placed too close may be vulnerable to ordinary price movement; a wider stop requires a smaller position. These levels are reference zones, not guaranteed floors, ceilings, or predictions.#IMPACTbyTrade
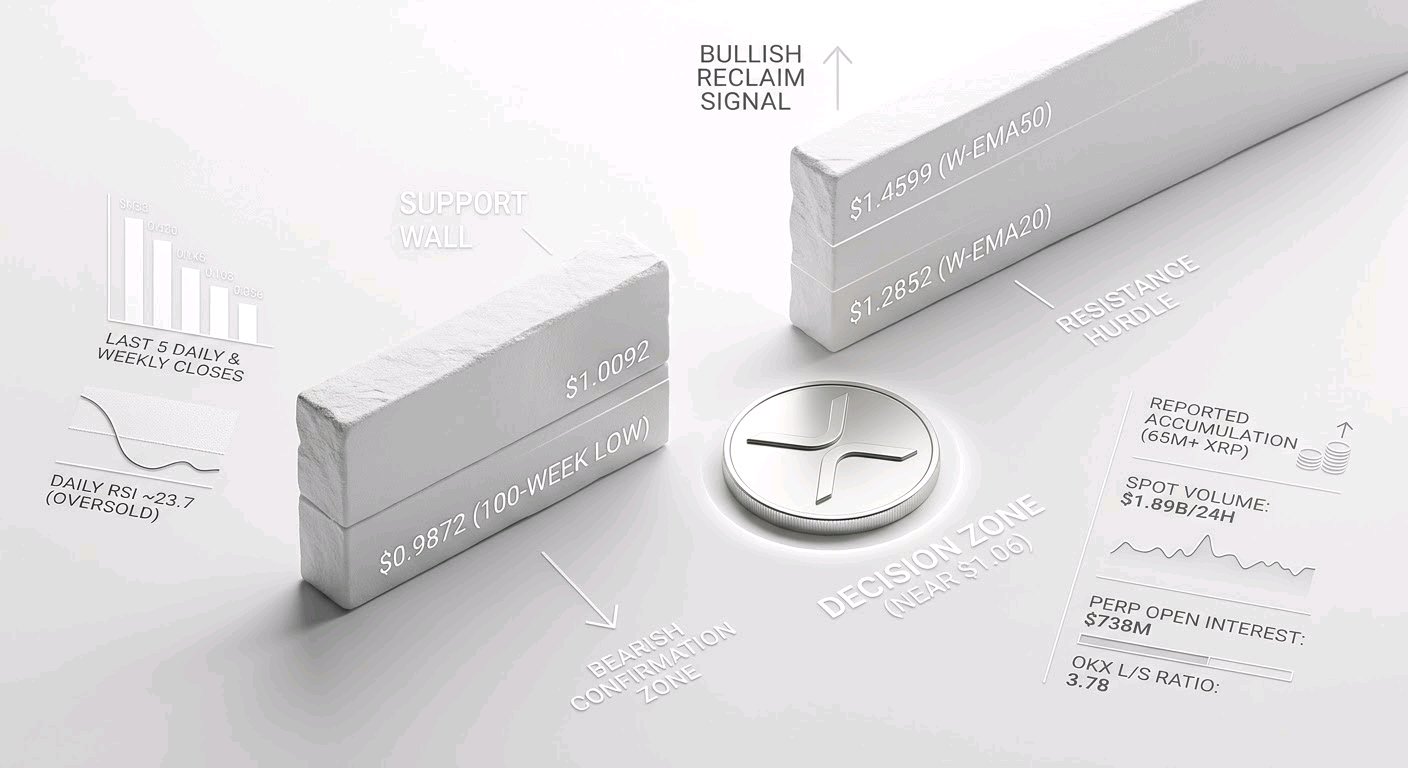
$XRPUSDT is not a clean “buy the dip” story, but neither is it a confirmed breakdown. The useful way to frame it is as a decision zone: the price is near important support, while the trend and several measures of market demand remain weak. A trader does not need to guess which side wins; the job is to define what evidence would change the view and size risk so being wrong is survivable. As of November 11, 2026, XRP is around $1.06. The last 6 completed daily candles closed progressively lower, from $1.2071 to $1.0565; the last 6 completed weekly candles also declined, from $1.5206 to $1.1132. Price sits below weekly EMA20 at $1.2852 and EMA50 at $1.4599. This is evidence of an established downtrend, not proof that it will continue indefinitely. Daily RSI is 23.7, showing weak momentum and a potentially stretched short-term move. It can accompany a bounce, but it cannot identify a bottom on its own. The immediate area to watch is weekly support at $1.0092, followed by the previous 100-week low at $0.9872. These levels are reference points, not guaranteed floors. A completed weekly close below $0.9872 would make the breakdown case more credible; a brief intraday dip would be less conclusive. On the upside, a weekly reclaim of $1.2852 would be the first meaningful challenge to the bearish structure. The next moving-average hurdle is $1.4599. Neither a single green candle nor a touch of resistance is enough to establish a trend change. The bearish case is the clearest current chart reading: lower closes, price below both weekly averages, and a market environment showing reduced risk appetite. It strengthens if XRP closes a week below $0.9872, particularly if spot selling volume rises and the price cannot quickly recover. It weakens if support holds through a retest and price begins making higher daily lows, then reclaims $1.2852. Volume matters because a price move with no evidence of increased participation is less persuasive; however, the supplied volume snapshot is only $1.89 billion across 72 venues in 24 hours. It does not give candle-by-candle buyer-versus-seller activity, so it cannot confirm either a breakdown or a reversal. The bullish case is conditional rather than imaginary. XRP is close to its recent low, the daily RSI is deeply depressed, and reports say large holders accumulated 65.32 million XRP over 4 days. Those facts leave room for a countertrend recovery. A stronger bullish signal would be support holding, improving daily structure, and a weekly close above $1.2852 with sustained spot volume. The bull case fails if $0.9872 gives way and price remains below it, or if an apparent bounce repeatedly stalls beneath the weekly EMA20. Oversold conditions and reported accumulation are not substitutes for price confirmation. The unclear case is also plausible: XRP may stay near support, swing sharply in both directions and offer no reliable trend signal. That would fit the tension between weak weekly momentum and a low RSI, as well as the mixed monthly trend. In that situation, waiting is a valid decision. A trader who must act could reduce position size, avoid adding simply because the price looks cheap, and set an invalidation point before entering. Futures positioning adds a caution, not a forecast. Perpetual open interest is $738 million across 4 venues; the supplied decline is for OKX only, where open interest fell 19.7% over 7 days. Funding is positive at a weighted 0.009% per 8 hours, meaning longs pay shorts. That suggests long exposure remains present and could be vulnerable if price falls, but it does not prove a squeeze is coming. OKX’s long/short account ratio is 3.78, while top traders’ position ratio is 0.86—a reminder that account counts and larger positions can tell different stories. Reliable liquidation levels and market-wide weekly open-interest change are not available, so claims about forced selling would go beyond the evidence. Fundamentals offer both catalysts and unresolved questions. XRP’s reported market capitalization is $66.9 billion, against $284,000 in annual fees and protocol revenue; the data therefore does not demonstrate that network activity currently captures meaningful value for token holders. Circulating supply is 63.5 billion of 100 billion, leaving 36.5 billion unissued. The available figures do not show how much new supply will enter circulation during the next year, so the supply risk is real but its near-term effect cannot be quantified. The latest news is mixed. XRPL lending and single-asset-vault amendments were reported as approaching the validator voting threshold, but approval, launch and real usage are not confirmed. Payments volume reportedly rose 207.4% to 1.16 billion XRP on November 9; one day of activity does not establish lasting demand for XRP. ETF flows reached about $1.06 billion cumulatively, but#IMPACTbyTrade