MAXJOHNS
5242點贊0分享121粉絲222關注
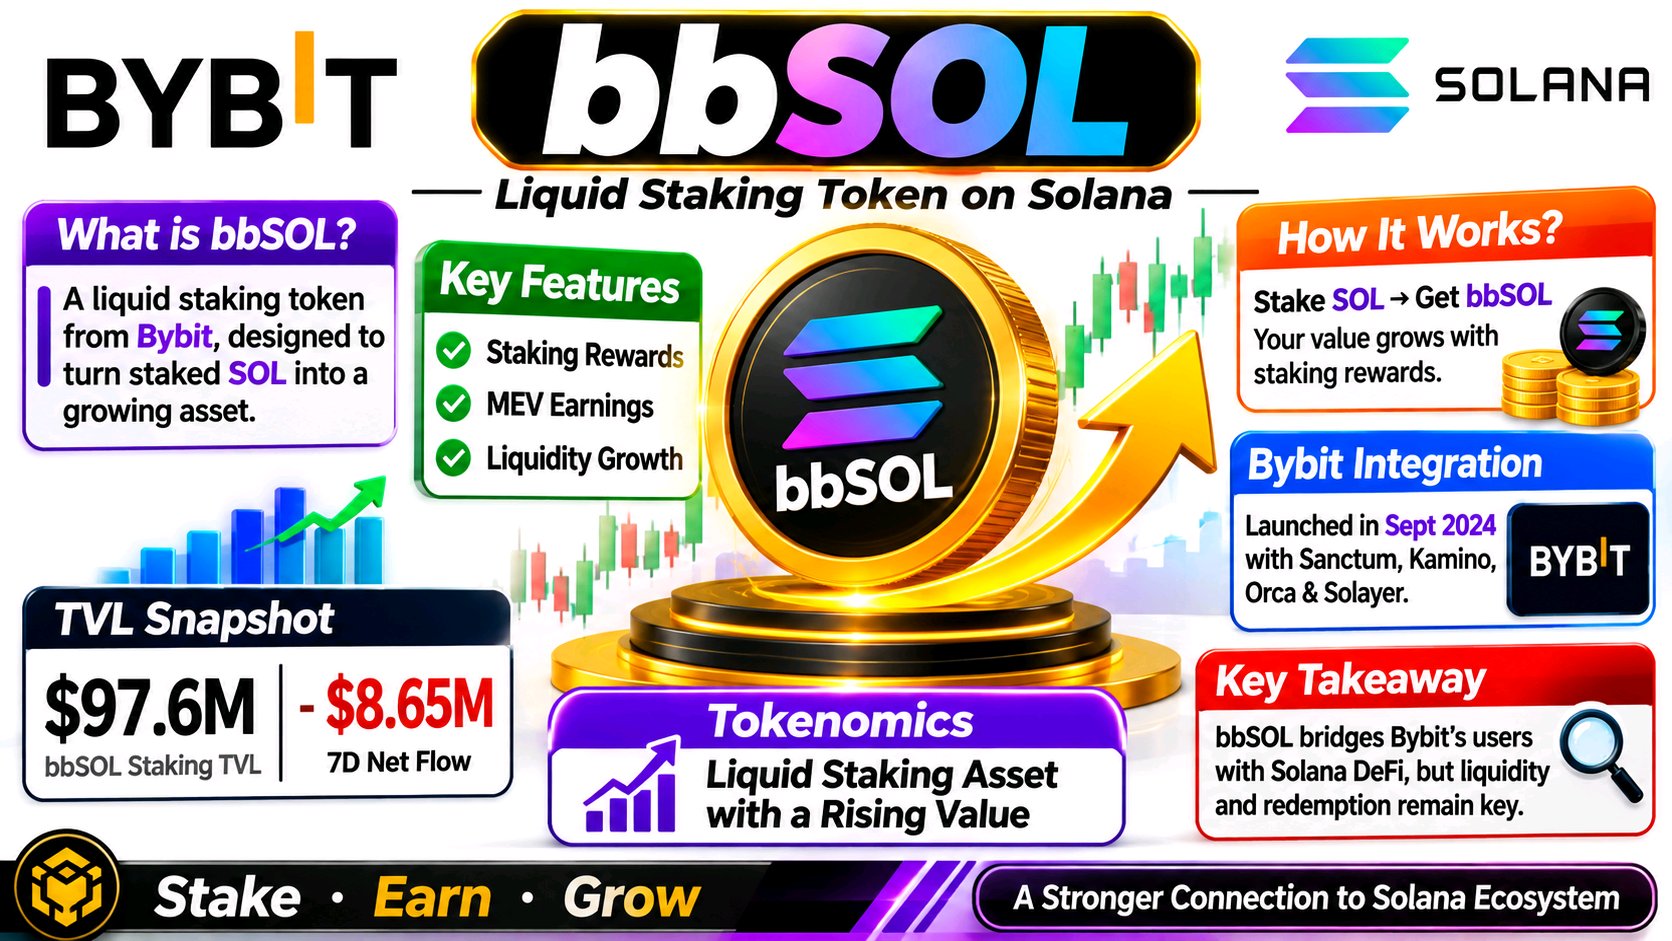
What stands out about bbSOL is that its real value is not simply earning Solana staking rewards. The more important question is whether Bybit can turn a centralized exchange's user base into sustained liquidity across Solana DeFi. That distinction matters because bbSOL is not an independent blockchain or a conventional governance token. It is a liquid staking asset issued through Bybit, with its value designed to appreciate against SOL as staking rewards accumulate. What caught my attention about bbSOL is the gap between its institutional story and the liquidity actually moving through its markets. Bybit introduced bbSOL in September 2024 with Sanctum, Kamino, Orca and Solayer. The product turns staked SOL into a liquid receipt: staking rewards, MEV and liquidity-related earnings accrue through a rising bbSOL-to-SOL exchange rate rather than regular cash payouts. Bybit’s documentation also makes the trade-off clear: a 0.1% deposit fee applies, and larger redemptions can take an epoch, roughly two to three days. So “liquid” does not mean frictionless under every condition. prnewswire.com +2 The more interesting development is distribution. Bybit announced Anchorage Digital custody support in October 2025, potentially making bbSOL easier for institutions to hold. But institutional access is not the same as institutional demand. DeFiLlama’s latest snapshot lists roughly $97.6 million in bbSOL staking TVL and an approximately $8.65 million negative seven-day net flow. That suggests capital has recently been leaving, despite the expanded custody route. Bybit Press +1 This is the tension traders should focus on: bbSOL’s value proposition depends on SOL staking economics, but its market quality depends on redemption confidence and usable DeFi liquidity. A yield-bearing token can still trade with meaningful slippage or discount if exits become crowded. I would watch net flows, bbSOL/SOL pricing, pool depth and redemption conditions before treating new integrations as adoption. The key question is whether institutional access turns into persistent on-chain liquidity—or remains mostly a distribution headline. #ByXIMPACT $BBSOLUSDT
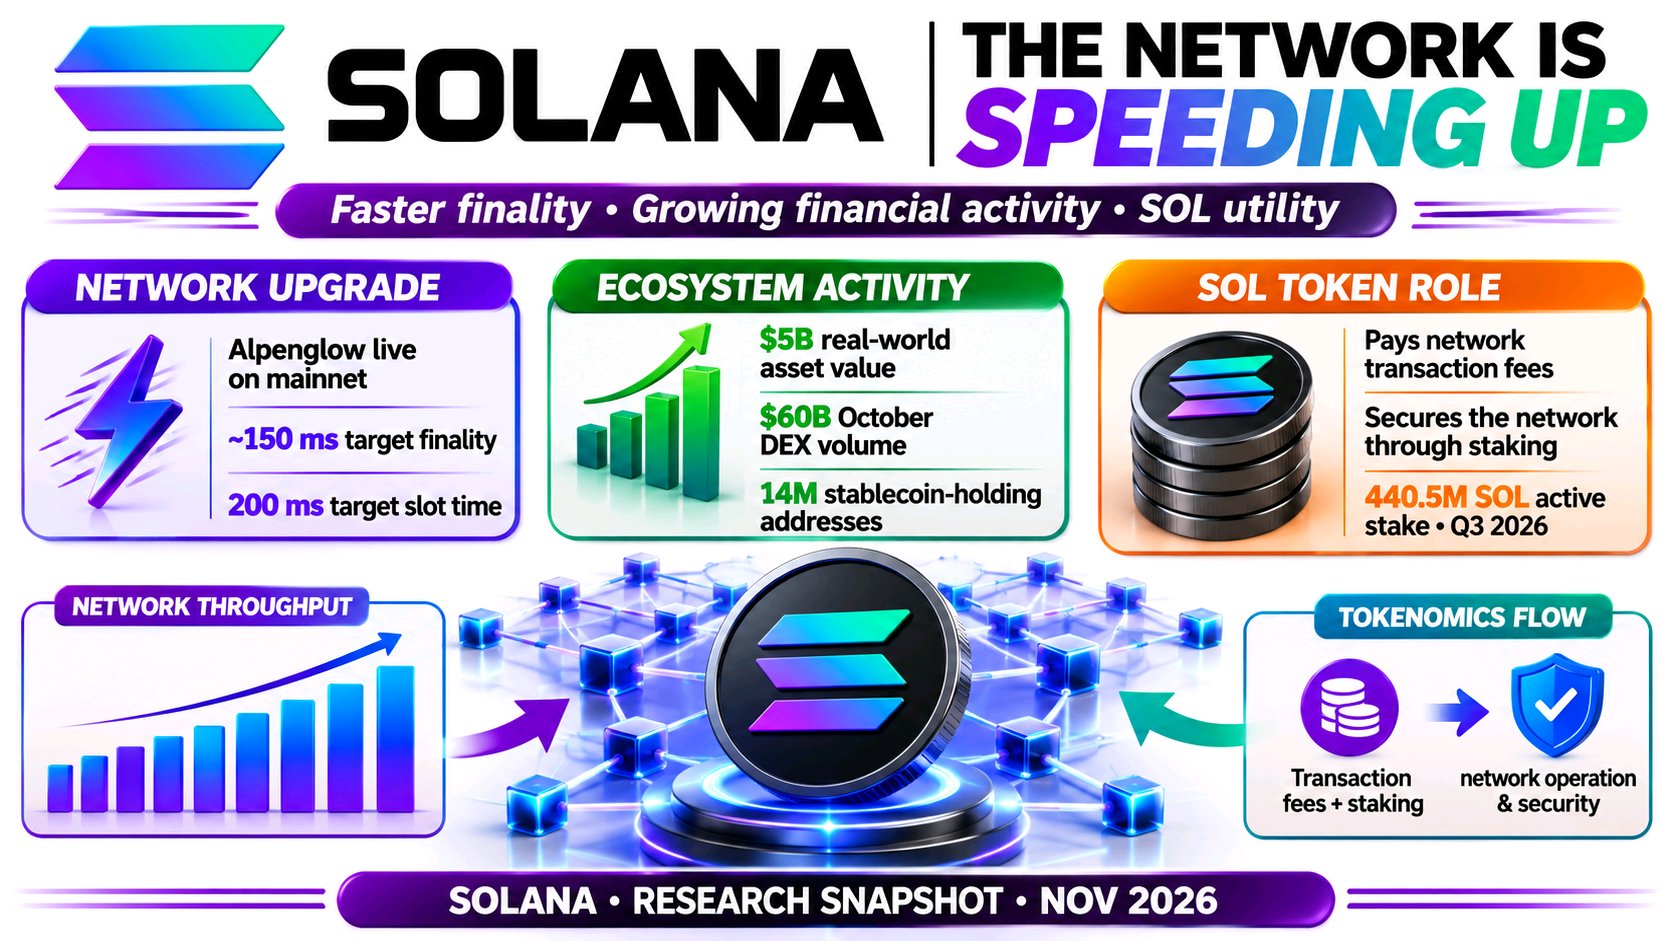
目前 Solana 最讓我關注的,是其底層網路活動與市場上 SOL 面臨的壓力之間的差異。兩者並未朝同一方向發展,這種區別值得關注。 Solana 的基礎設施持續發展:Alpenglow 於 10 月上線主網,目標最終確認時間約為 150 毫秒,同時目標區塊時間降至 200 毫秒。基金會還報告稱,10 月份有 50 億美元的現實世界資產價值和 600 億美元的去中心化交易所(DEX)交易量。DeFiLlama 目前顯示約 46 億美元的 DeFi 總鎖倉量(TVL)、139.6 億美元的穩定幣,以及 24 小時內 233 萬個活躍地址。這些是實質的活動,但並不能讓 SOL 免受市場壓力的影響。 SOL 的交易價格在 72 美元左右,七天內下跌約 16%。期貨未平倉合約接近 41 億美元,24 小時內下跌 8.45%,而爆倉金額達到約 8900 萬美元,其中大部分來自多頭。Solana DEX 的交易量也較上週下降約 19%,永續合約交易量下降約 37%。交易者似乎是在鏈上交易降溫時降低風險,而不是完全放棄該網路。 我會觀察 TVL、穩定幣供應量和活躍地址是否會穩定下來,同時觀察現貨需求是否回升,以及未平倉合約是否能在沒有過度槓桿的情況下重建。Alpenglow 和機構代幣化是具有意義的里程碑,但持續的使用率和流動性仍需轉化為對 SOL 的持久需求。這段差距才是我所關注的部分。 #ByXIMPACT $SOLUSDT
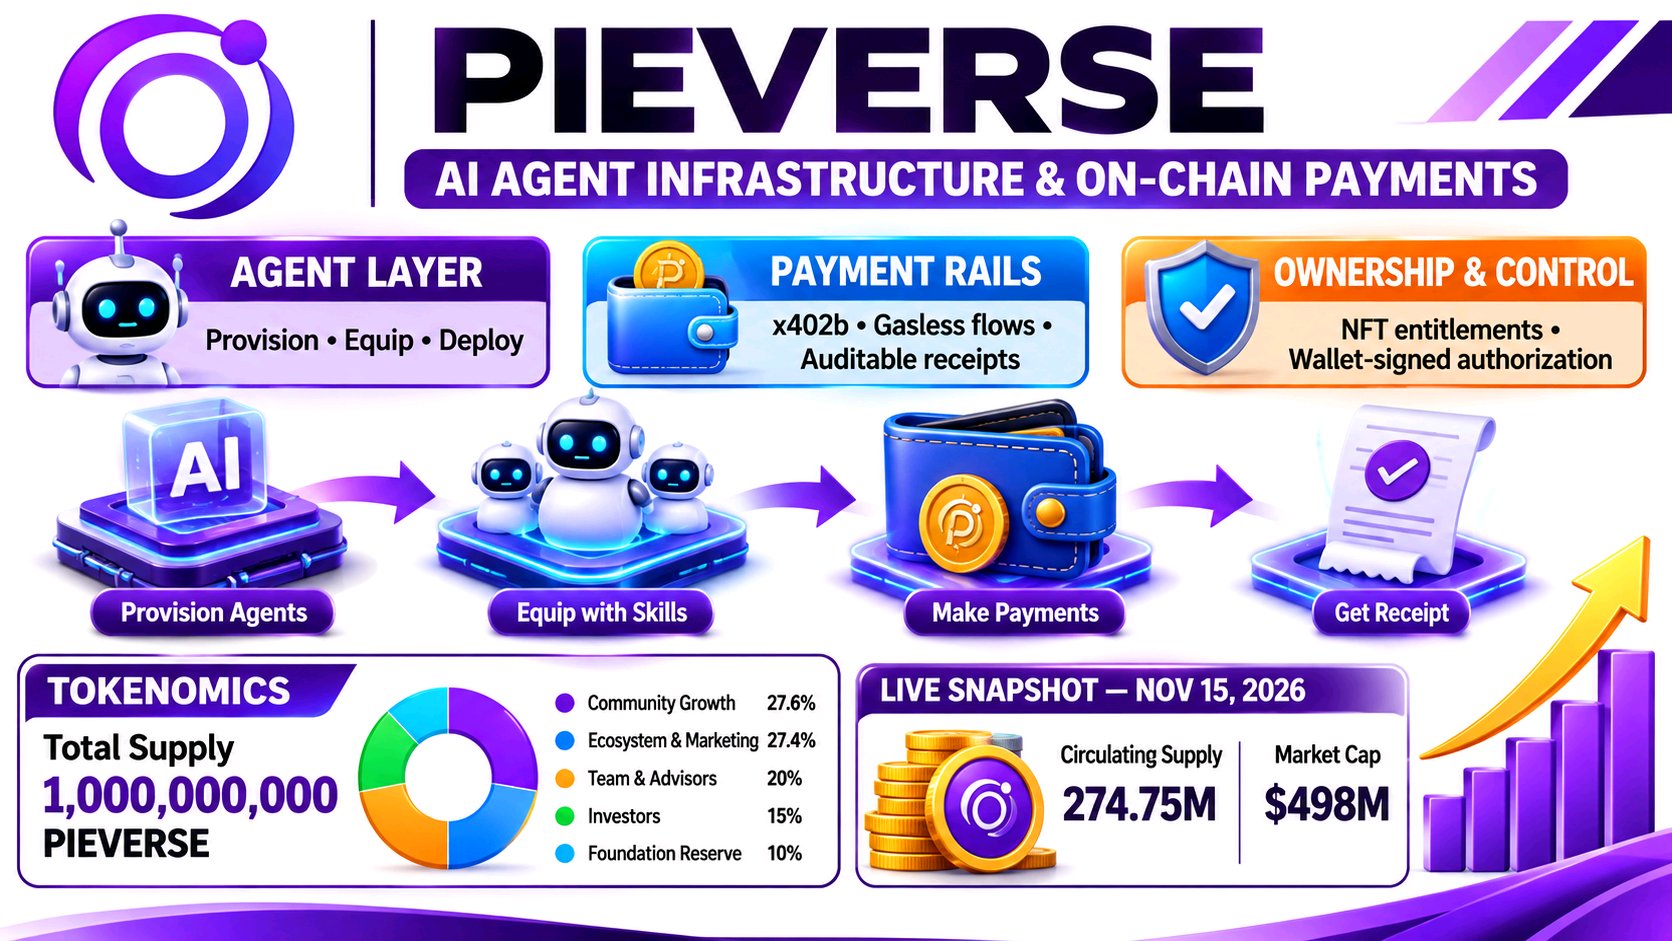
What stands out in Pieverse is the timing: its market valuation has expanded sharply just as the project reaches an important transition in token distribution. The interesting question is whether ecosystem adoption can keep pace with the supply entering circulation. What caught my attention in Pieverse is the collision between a fast-growing AI-agent story and a major change in token supply. The project’s current site describes tools for provisioning Web3 agents, equipping them through a Skill Store, and verifying ownership with NFT entitlements. Its earlier whitepaper focused more heavily on gasless, auditable agent payments, so the product direction is evolving rather than standing still. Pieverse +1 Agents need wallets, permissions, payment rails and usable services, not just better models. Pieverse is trying to connect those pieces, and its November 11 partnership with Four.meme points toward distribution through BNB Chain’s on-chain launch ecosystem. But a partnership announcement is not proof of recurring users or fee revenue. X Web Viewer +1 That distinction matters now because the token’s one-year lockup ended on November 14, with team, advisor and investor allocations beginning linear vesting. Those groups represent 35% of the fixed one-billion supply. The exact first release amount is not clearly stated in the reporting, so I would avoid treating headline unlock estimates as confirmed circulating supply. Coinranking +1 Market positioning adds another layer. CoinGecko showed PIEVERSE around $1.81, roughly 19% below its $2.23 all-time high, while perpetual open interest was about $86 million and around 17% of market cap; funding remained positive. That suggests derivatives activity is meaningful beside spot demand. CoinGecko I would watch whether spot volume absorbs newly available tokens, whether open interest cools, and whether agent usage produces measurable fees. Can adoption grow faster than dilution? #ByXIMPACT $PIEVERSEUSDT
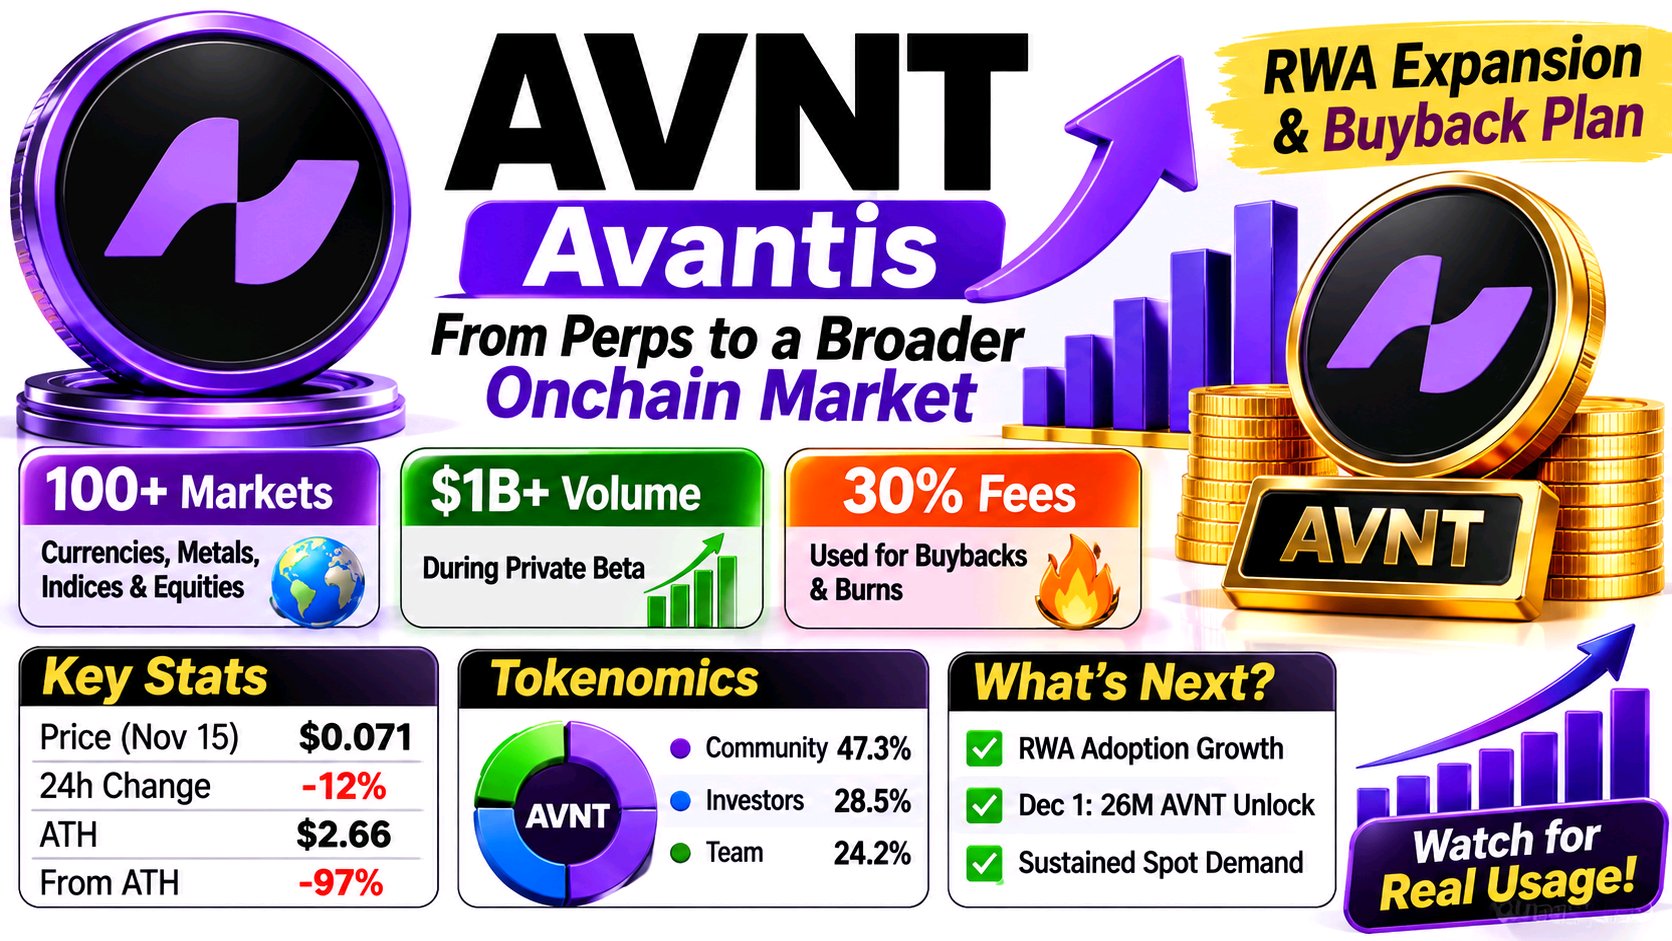
What caught my attention in AVNT is the gap between the exchange’s expanding ambition and the token’s market behaviour. Avantis is now Veranta, but the ticker remains AVNT. The September rebrand was more than a name change: the team is moving from crypto perpetuals toward a broader onchain market for currencies, metals, indices and equities. Its announcement says 100+ real-world markets are already supported. During private beta, the platform reportedly processed over $1 billion in volume, 100,000 trades and $200,000+ in revenue; open interest roughly tripled from $10 million to $30 million. Global Onchain Markets +1 There is also a direct token-economics link. Since March, 30% of eligible opening, closing and profitable-trade fees have funded open-market AVNT buybacks and burns. That connects activity to supply reduction, although the impact depends on fee generation, not headline volume alone. Veranta +1 The market is not rewarding that story yet. On November 15, AVNT traded near $0.071, down about 12% in 24 hours and roughly 97% below its $2.66 peak. Futures volume was around five times spot volume, open interest had fallen 12.8%, and funding was negative. That suggests leveraged positions are unwinding, not clear fresh spot accumulation. CoinGlass For me, the test is whether broader RWA activity produces sustained eligible fees, verifiable burns and deeper spot liquidity. I would also watch the scheduled 26 million AVNT release on December 1. Can adoption close the gap before new supply becomes the market’s bigger concern? NAUT #ByXIMPACT $AVNTUSDT
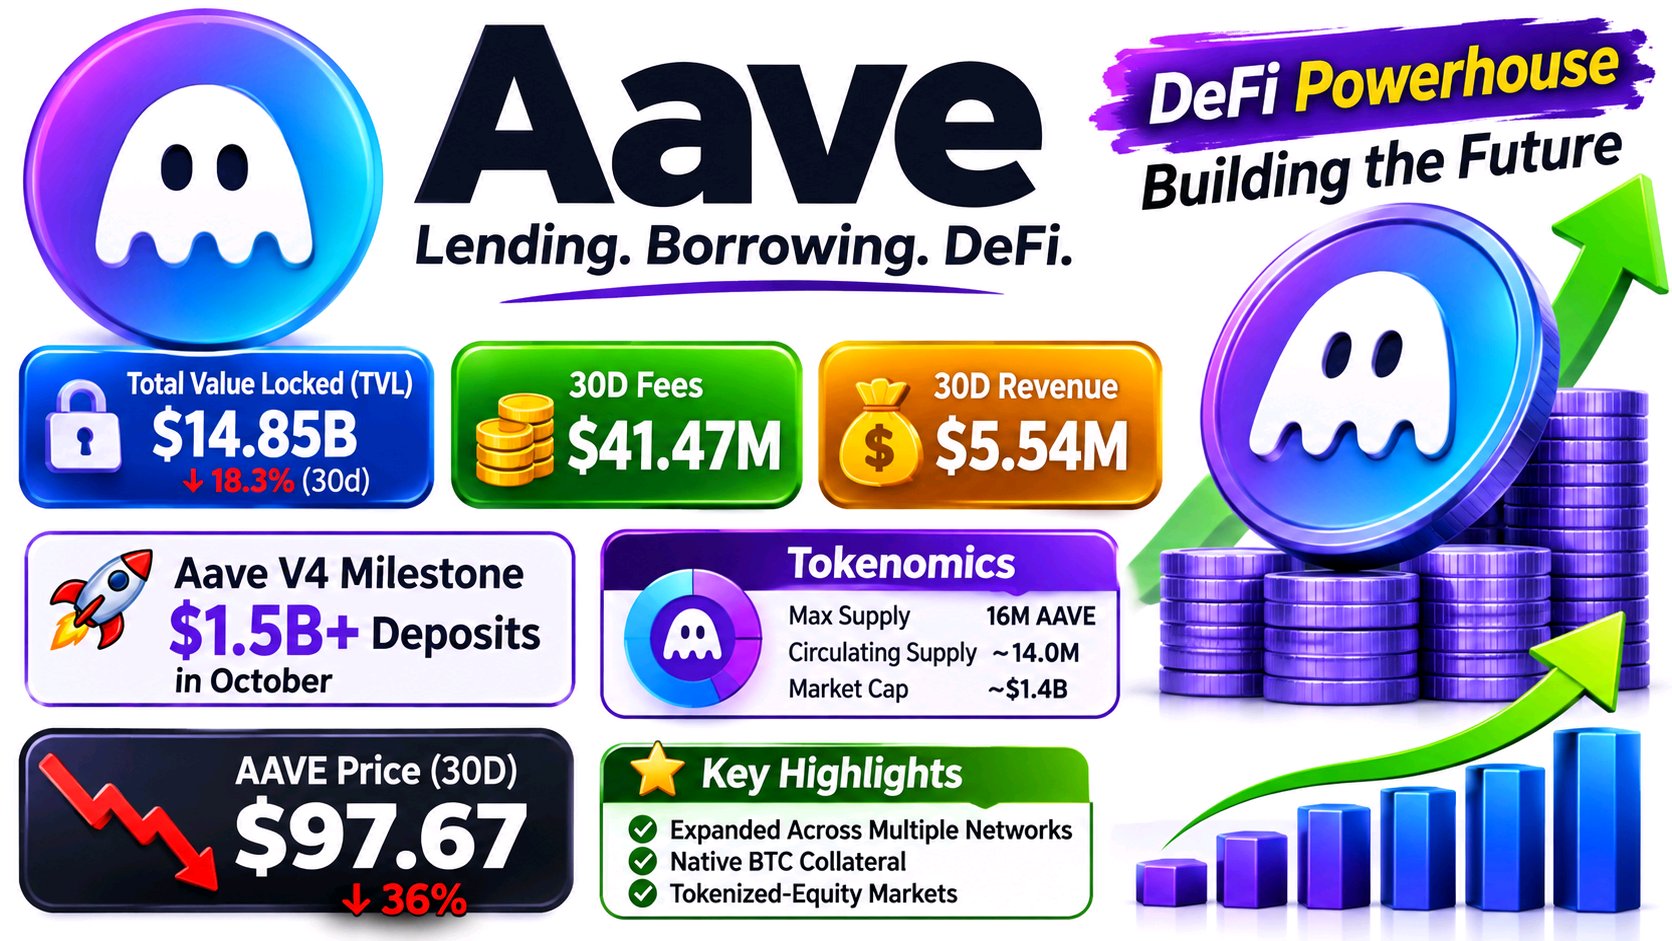
我目前覺得 Aave 最有趣的一點,在於其基礎業務活動與市場對待其代幣方式之間的脫節。AAVE 的價格大幅下跌,但該借貸協議仍在產生可觀的經濟活動。 根據 DefiLlama 的數據,截至 11 月 15 日,Aave 的鎖倉量 (TVL) 約為 148.5 億美元,而在過去 30 天內產生了 4147 萬美元的手續費和 554 萬美元的協議收入。然而,TVL 在此期間下降了 18.3%,這表明儘管協議仍在持續賺取豐厚的手續費,流動性卻正在流失。DefiLlama 還有另一個值得關注的發展。Aave Labs 報告稱,V4 在 10 月份的存款額突破了 15 億美元,擴展到多個網絡,並迎來了首位外部市場管理員。原生比特幣抵押品和代幣化股票市場也顯示出 Aave 如何嘗試超越傳統加密貨幣借貸的範疇。2026 年 10 月 - 開發 - Aave +1 這形成了一個有趣的對比:產品基礎設施正在擴張,但更廣泛的流動性狀況仍然缺乏支撐。 DefiLlama 顯示 AAVE 價格接近 97.67 美元,在 30 天內下跌了約 36%。因此,市場定價的因素不僅僅是協議收入:還包括存款下降、風險偏好減弱以及對未來成長的不確定性。DAO 的收入資助回購計劃擁有 5000 萬美元的年度預算,但它無法保證價格支撐。DefiLlama +1 對於交易者來說,我會關注 TVL 是否穩定、V4 存款是否轉化為持續的借貸和手續費,以及現貨交易量是否能確認任何復甦趨勢。不斷擴張的基礎設施最終能轉化為持久的流動性和更強的代幣價值捕獲嗎? #ByXIMPACT $AAVEUSDT
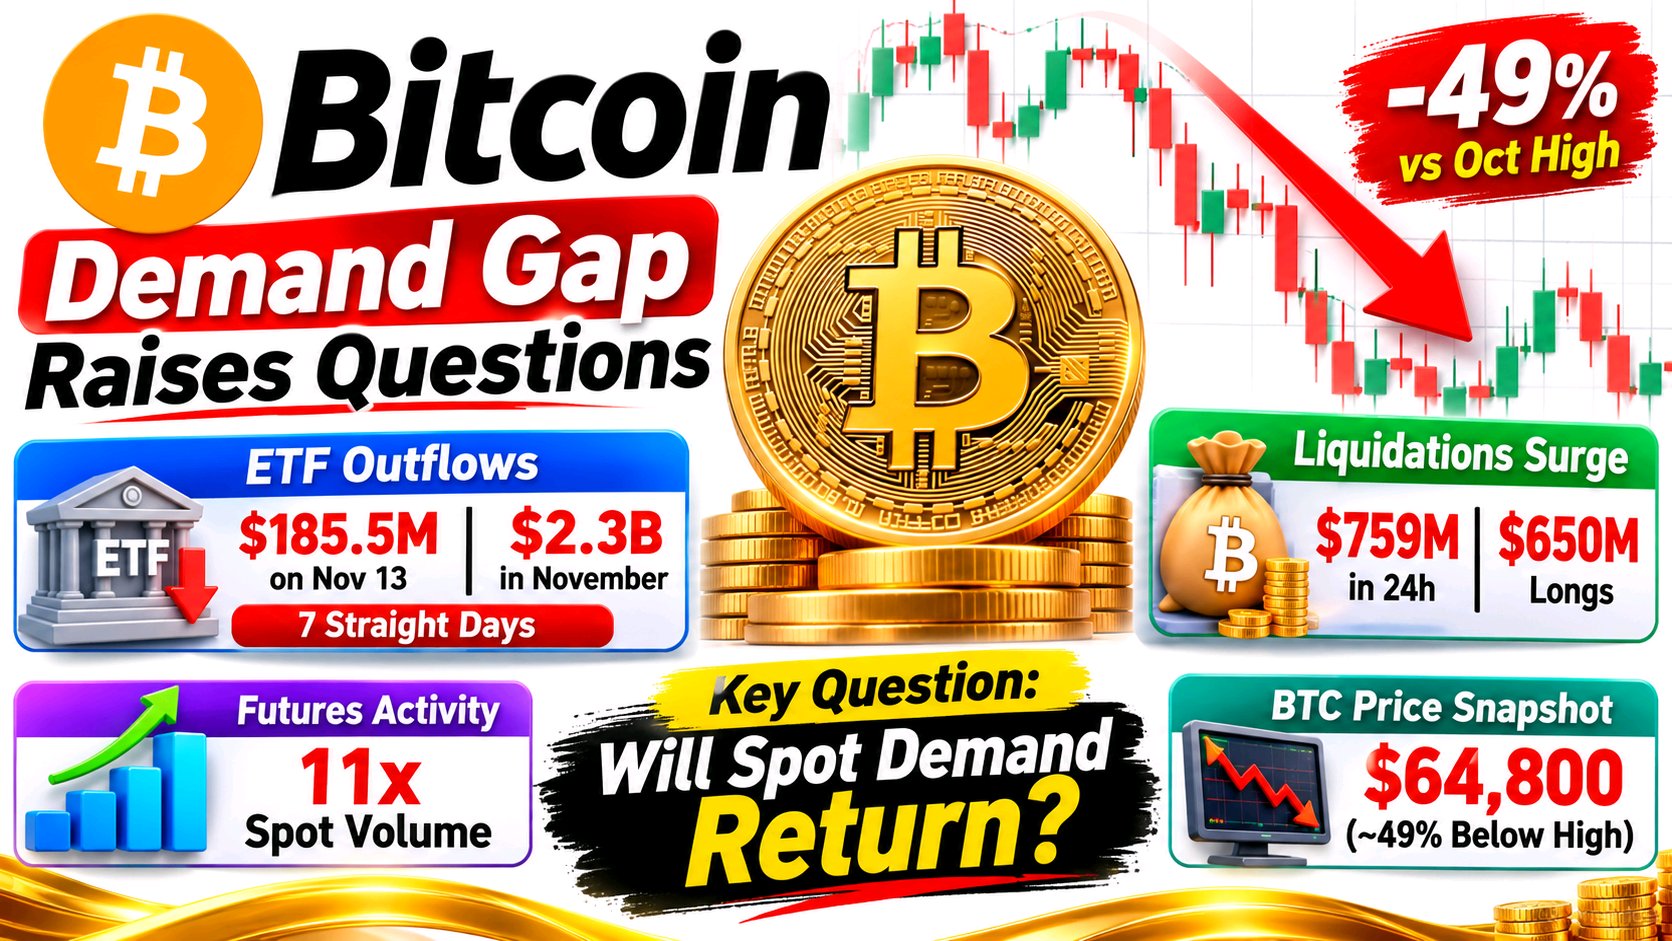
本週引起我對比特幣關注的是其「固定供應」說法與實際市場需求之間的差距。 比特幣的發行計劃並未改變,但短期內邊際買家的影響力比那眾所周知的 2,100 萬枚硬幣上限更為重要。美國現貨比特幣 ETF 在 11 月 13 日錄得約 1.855 億美元的淨流出,撤資趨勢已延續至第七個交易日。截至該日,11 月的流出總額已達到約 23 億美元。這是一個可衡量的機構需求重要渠道的逆轉,並非長期持有者拋棄 BTC 的證據。 衍生品交易正在加劇這種壓力。CoinGlass 報告稱 24 小時內清算金額約為 7.59 億美元,其中約 6.5 億美元來自多頭倉位,而期貨交易量約為現貨交易量的 11 倍。在該數據快照時間點,比特幣價格接近 64,800 美元,較其 2025 年 10 月的高點下跌了近 49%。 這種組合至關重要:ETF 贖回顯示現貨需求疲軟,而擁擠的槓桿交易可能將跌勢轉化為被迫拋售。這兩個指標單獨來看都無法解釋整個市場走勢,且清算總額會因交易平台和衡量窗口的不同而有所差異。 我會觀察 ETF 資金流是否轉正,以及在復甦過程中現貨交易量是否擴大。如果價格在未平倉合約減少的情況下趨於穩定,則說明槓桿可能正在出清。如果資金持續流出,且反彈主要依賴期貨推動,那麼對於這次回升應保持懷疑態度。關鍵問題在於:在下一波倉位建立之前,真正的現貨需求是否會回歸。 #ByXIMPACT $BTCUSDT
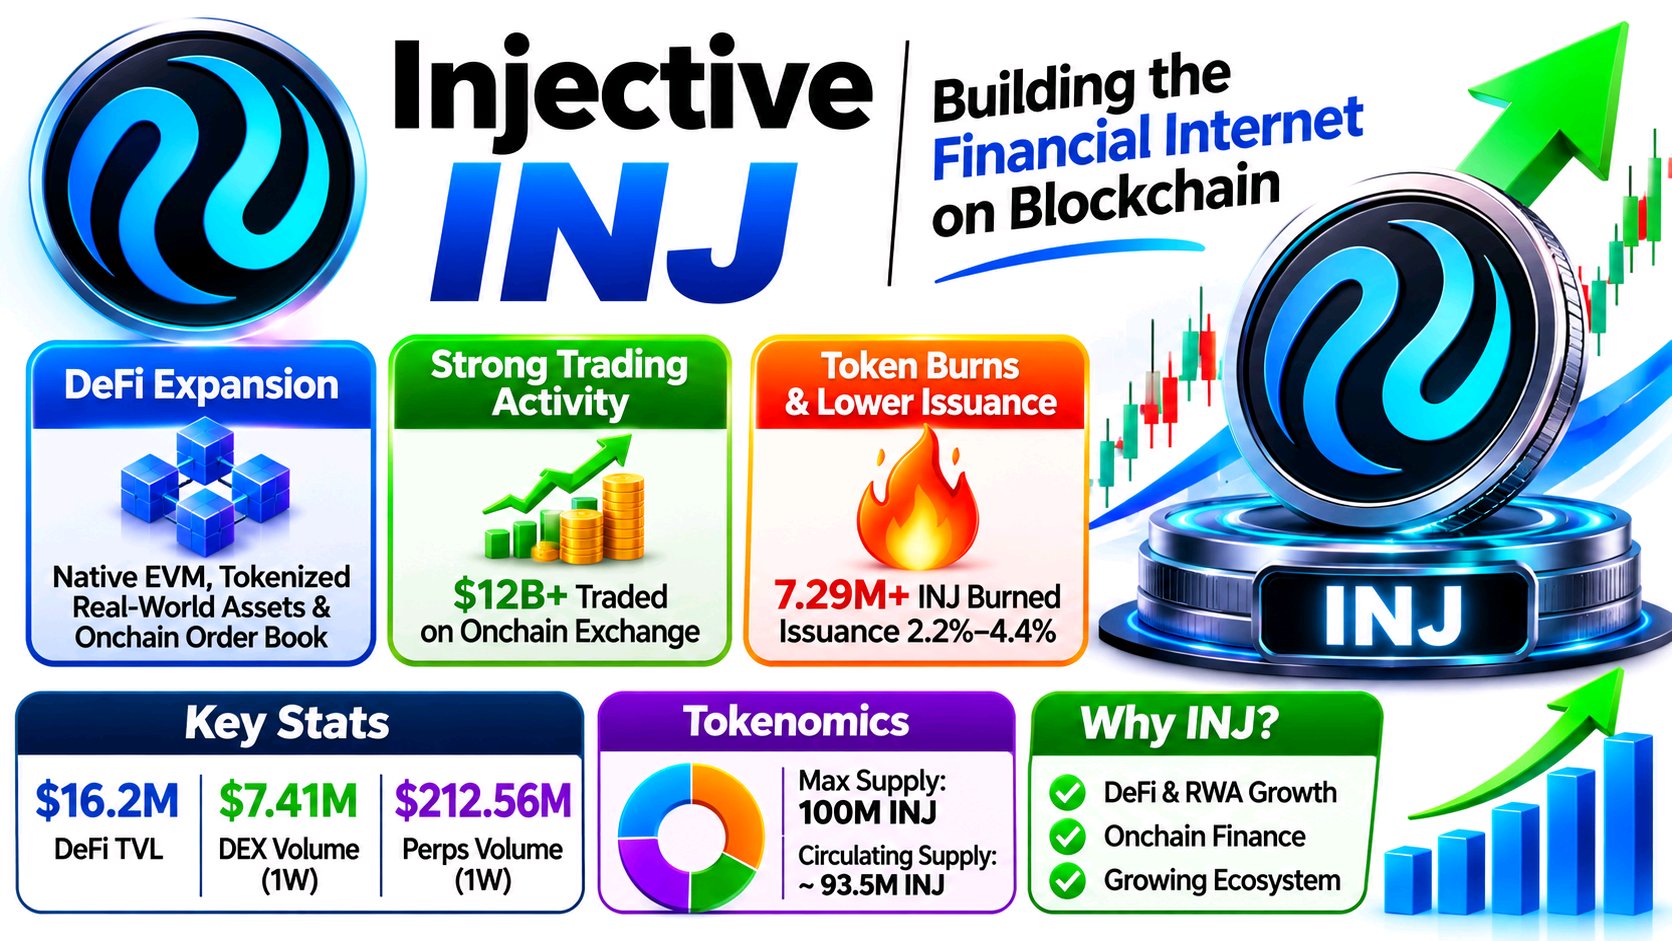
引起我對 INJ 關注的是 Injective 不斷擴大的金融野心與其 DeFi 生態系統中目前相對較小的資本規模之間的差距。 該網路不再僅僅是一條專注於交易所的鏈。其 11 月 8 日的週年回顧中提到了原生 EVM、代幣化現實世界資產 (RWA)、股票和外匯市場,以及 USDC 結算。Injective 還報告稱,過去一年其鏈上訂單簿的交易額超過 120 億美元。交易所模組在鏈上處理訂單簿、撮合和結算,為這些市場提供了共享的金融基礎設施。injective.com +1 但使用量需要與資本深度區分開來看。根據 DefiLlama 的數據,11 月 14 日其 DeFi TVL(總鎖倉價值)約為 1,620 萬美元,穩定幣規模為 1,596 萬美元。每週 DEX 交易量下降了 26.1%,降至 741 萬美元,而永續合約交易量下降了 10.2%,為 2.1256 億美元。這雖是顯著的活動量,但尚未展現出廣泛且持續增長的流動性。DefiLlama 代幣的情況也值得深入探討。Injective 表示已有超過 729 萬枚 INJ 被銷毀,而其 2026 年的發行量削減計畫將年度目標範圍降低至 2.2%–4.4%。然而,一份 SEC 備案文件顯示,9 月份 INJ 的總供應量為 1.229 億枚,這表明銷毀並不自動導致供應量縮減;發行量仍然至關重要。injective.com +1 對於交易者來說,我會觀察新的 RWA 和穩定幣通道是否能轉化為持續的 TVL、更深的訂單簿以及不斷增加的手續費。如果活動量增長但流動性沒有跟上,那麼其擴張的敘事仍是不完整的。Injective 能否將產品的廣度轉化為持久的資本需求? #ByXIMPACT $INJUSDT
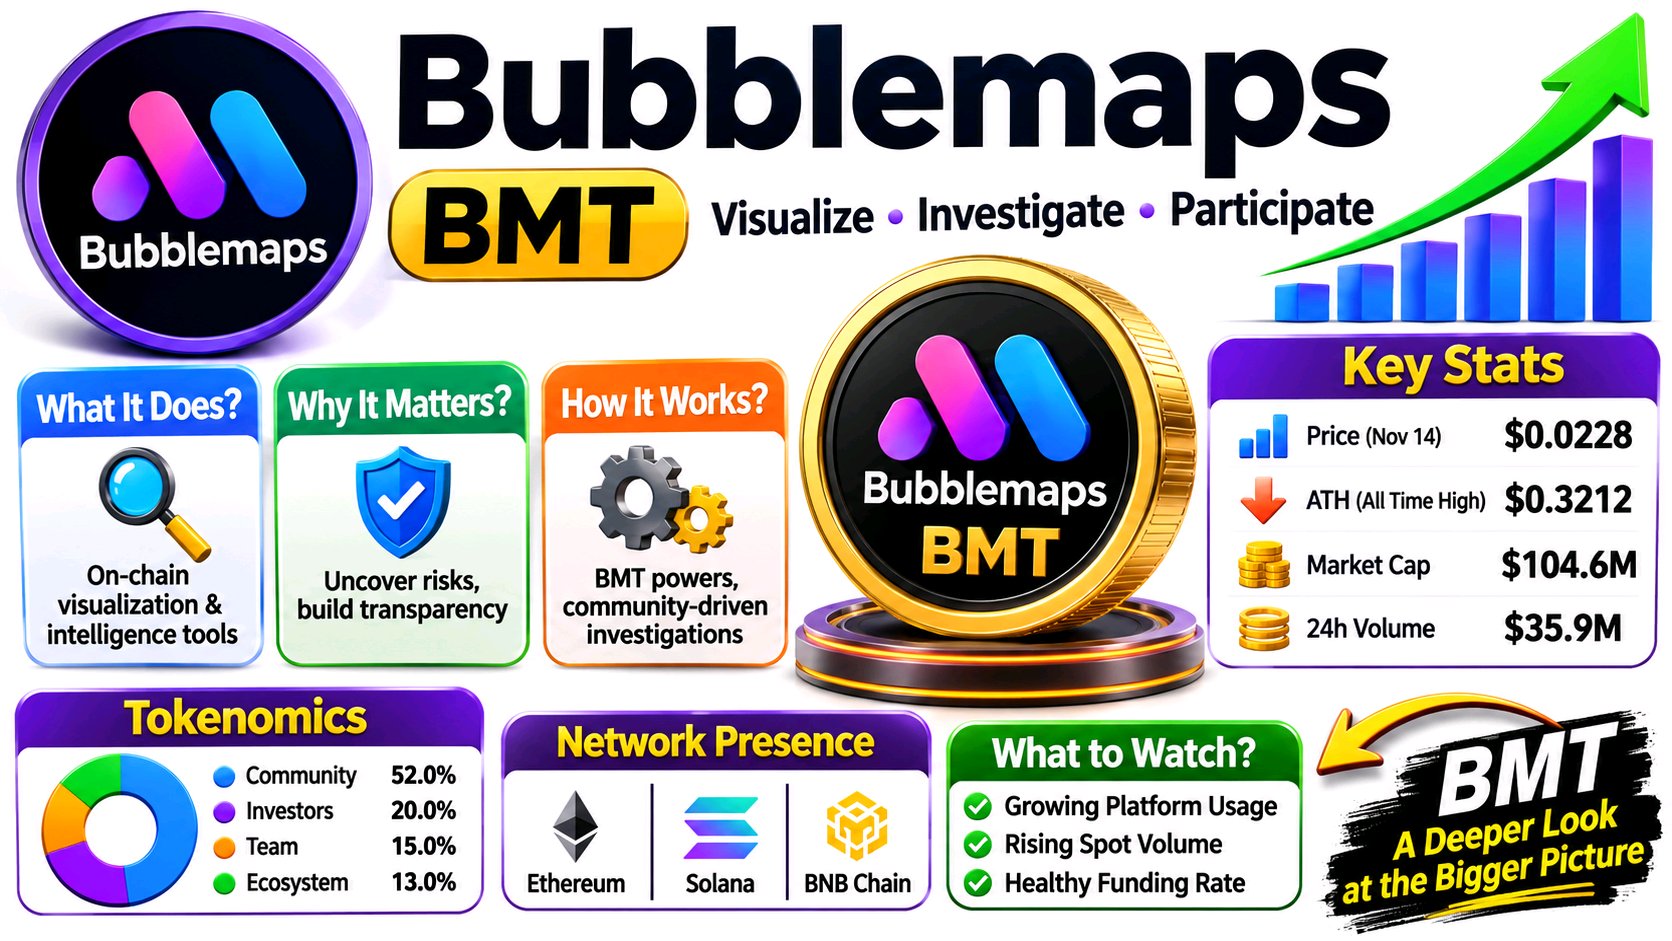
What interests me about BMT is the gap between what Bubblemaps is building and what the market is trading. Bubblemaps is more than a wallet-visualisation tool. V2 maps token holders, wallet clusters and historical distribution across multiple chains, including Solana, Ethereum and BNB Chain. Intel Desk turns community investigations into public case records. BMT links these products to participation: holders allocate tokens to prioritise cases, fund independent bounties and unlock advanced analytics. The token therefore has a role inside the workflow, not merely a ticker attached to a product. Bubblemaps +2 But utility and demand are different things. Bubblemaps documents how BMT voting and deposits work, yet public data does not establish how much recurring platform activity becomes sustained token demand. That is the metric I want to see. Bubblemaps Wiki +1 The market structure adds another layer. CoinGlass placed BMT near $0.0228 on November 14, roughly 93% below its $0.3212 peak. Futures volume was about $63.5 million against $35.9 million spot volume, with open interest near $9.6 million. Derivatives activity outweighed spot participation, while funding was sharply negative in that snapshot. CoinGlass That can reflect crowded positioning and short-side pressure, not necessarily durable accumulation. Traders should watch whether spot volume expands with price, whether open interest rises without destabilising funding, and whether Intel Desk and V2 usage becomes measurable. BMT’s longer-term case depends on people repeatedly needing its tools, not simply trading the narrative. Can product engagement become visible, persistent token demand? #ByXIMPACT $BMTUSDT
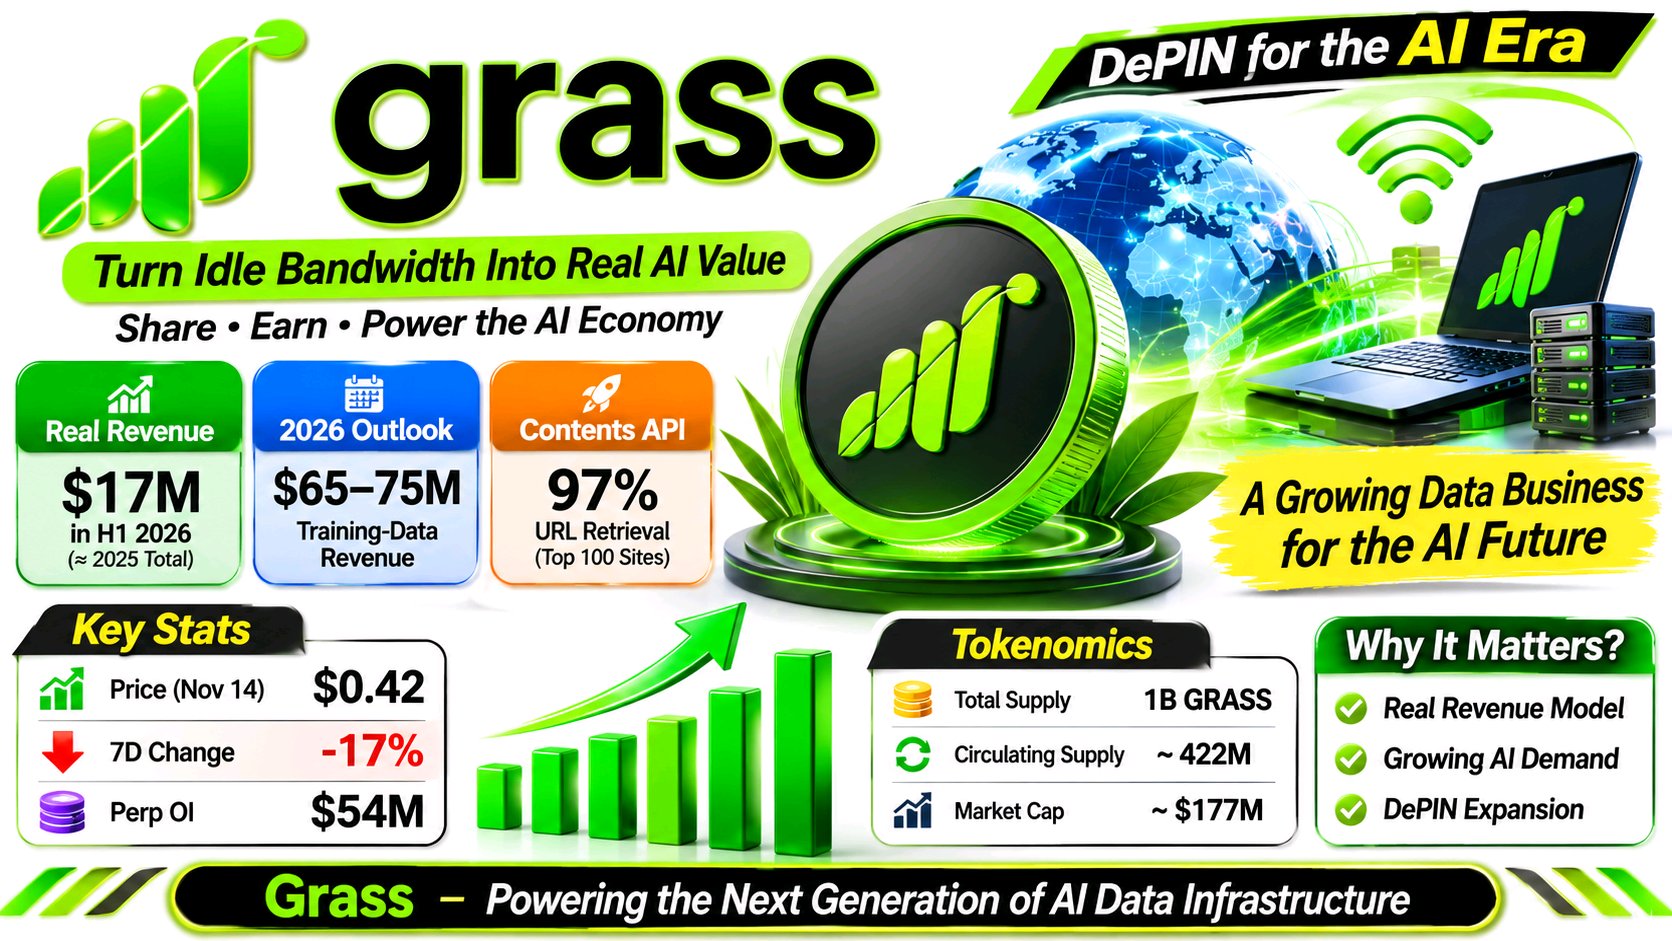
What caught my attention in Grass is the gap between operating progress and the way GRASS is priced. It is no longer just an idea about sharing spare bandwidth; it is building a commercial data business on that network. In its July 2026 holder update, Grass reported $17 million in first-half revenue, matching all of 2025, and monthly operating costs of roughly $2–3 million. It projected $65–75 million in 2026 training-data revenue, although that is guidance, not realized income. The October launch of its Contents API adds another product: Grass reported retrieving 97% of URLs in its 100-site benchmark, versus 84% for Firecrawl and 76% for Parallel. These are company-run results, but they show a shift from selling datasets toward live web retrieval for AI systems. That connection matters. Training-data sales can finance wider crawling, while broader coverage may make search and real-time retrieval more useful. Yet business growth does not automatically create token demand. Grass says Stage 2 participant rewards are funded by network revenue in USDC, without adding new GRASS emissions. Meanwhile, GRASS traded near $0.42 on November 14, down about 17% over seven days, while CoinGecko listed roughly $54 million in perpetual open interest. I would watch whether API usage turns into repeat revenue and whether spot demand absorbs continuing token releases. The key question is whether a growing data business creates durable demand for GRASS, rather than value for the network alone. #ByXIMPACT $GRASSUSDT
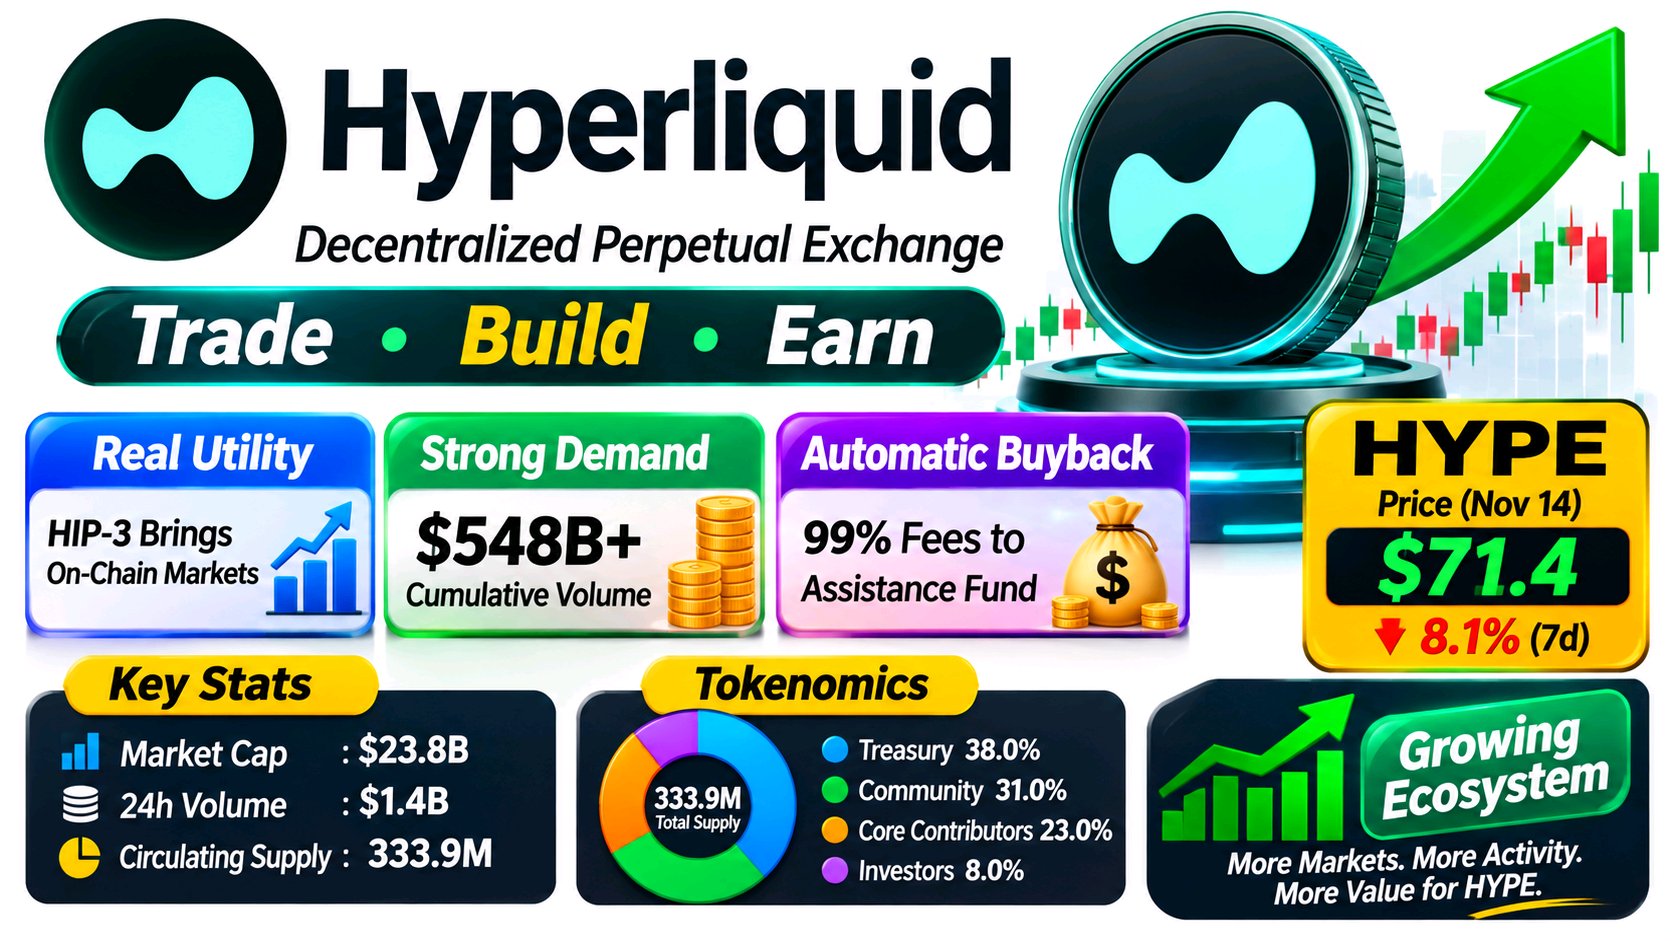
Hyperliquid 最引人注目的一點在於,$HYPE 與交易所受歡迎程度以外更具衡量價值的指標——即交易基礎設施本身的擴張——聯繫日益緊密。關鍵問題在於,這種活動能否轉化為持久的代幣需求。 證據就是 HIP-3。它允許第三方開發者為股票、商品和指數推出永續合約市場,但要求他們必須質押 $HYPE 作為抵押品。9 月份的一份 SEC 文件顯示,這些市場約佔 Hyperliquid 過去 30 天交易量的 30%,自推出以來累計交易量已超過 5,480 億美元。這將產品採用率與直接的代幣用途聯繫起來,而不是空泛的功能聲稱。sec.gov 還有第二個聯繫:Hyperliquid 的文檔顯示,99% 的合格協議費用會流入援助基金(Assistance Fund),該基金會自動購買 $HYPE;SEC 文件報告稱,截至 9 月 8 日,已有 4,710 萬枚代幣被收購並永久銷毀。因此,活動可以透過部署抵押品和費用資助的購買來支撐需求。Hyperliquid Docs +1 但市場並未自動買單這個故事。11 月 14 日,$HYPE 交易價格在 71.4 美元左右,七天內下跌了 8.1%,而期貨交易量大約是現貨交易量的十倍,未平倉合約(open interest)在 24 小時內下滑了 2.5%。CoinGlass 這種背離值得關注。交易者應追蹤 HIP-3 的活動是否仍具意義、費用資助的購買是否跟得上代幣歸屬(vesting)的供應速度,以及現貨需求是否能證實衍生品活動。真正的考驗在於擴張的市場是否能產生持久的代幣需求,而不僅僅是令人印象深刻的交易量。 #ByXIMPACT $HYPEUSDT
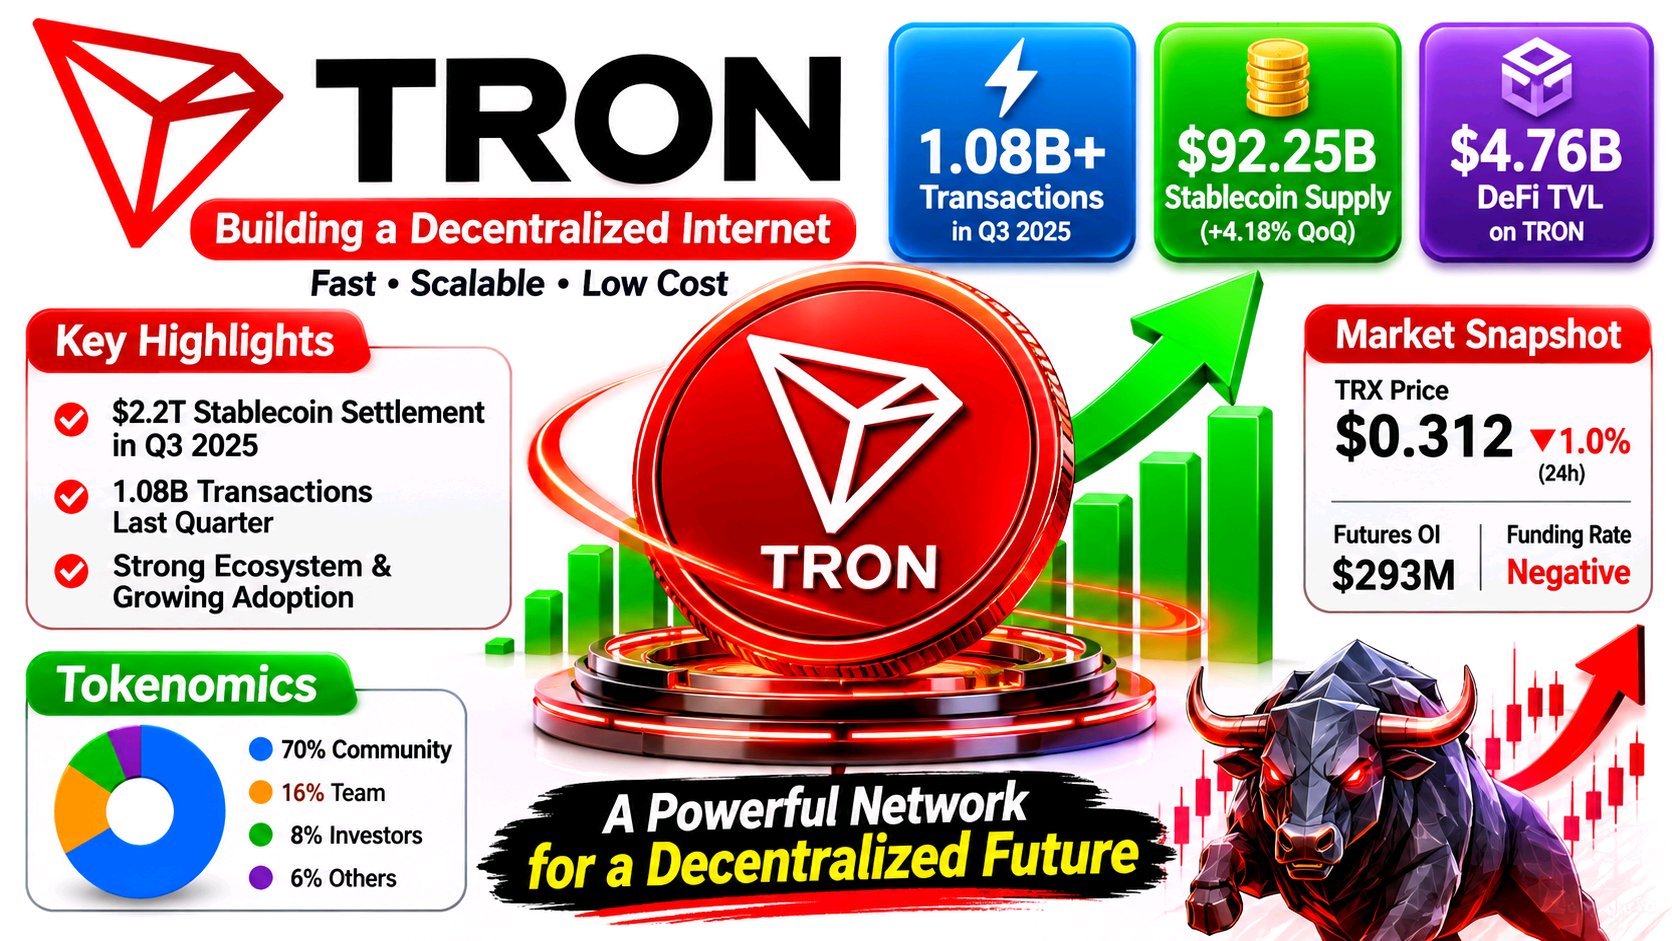
What stands out in TRON is the gap between its enormous stablecoin activity and the much weaker trading activity developing around its own token. That distinction matters because network adoption and TRX market demand are not necessarily moving together. TRON DAO’s Q3 report puts average stablecoin supply at $92.25 billion, up 4.18% quarter over quarter, with approximately $2.2 trillion in quarterly stablecoin settlement. It also reports 1.08 billion transactions during the quarter. DefiLlama’s November 14 snapshot still shows roughly $93.9 billion in stablecoins and $4.76 billion in DeFi TVL, although weekly DEX volume had fallen 46.9% to $370.8 million. TRON DAO: Moving Trillions, Empowering Billions +1 That contrast is important. TRX is used for fees, staking, governance and DeFi collateral, while staking also supplies Bandwidth and Energy. Fees can burn TRX, but block and voter rewards issue new tokens, so network activity alone does not guarantee net scarcity. TRON Developer Hub +1 The market is showing a different kind of tension: TRX was near $0.312, down about 1% over 24 hours, while aggregate futures open interest remained around $293 million and funding was negative. That suggests leveraged positioning is still active despite spot weakness; it is not proof of an imminent reversal. CoinGlass +1 I would watch whether stablecoin balances and actual transfer activity keep holding up, whether DEX activity recovers, and whether spot demand starts confirming any improvement in derivatives positioning. TRON’s infrastructure looks busy. The question is how much of that activity ultimately accrues to TRX. #ByXIMPACT $TRXUSDT
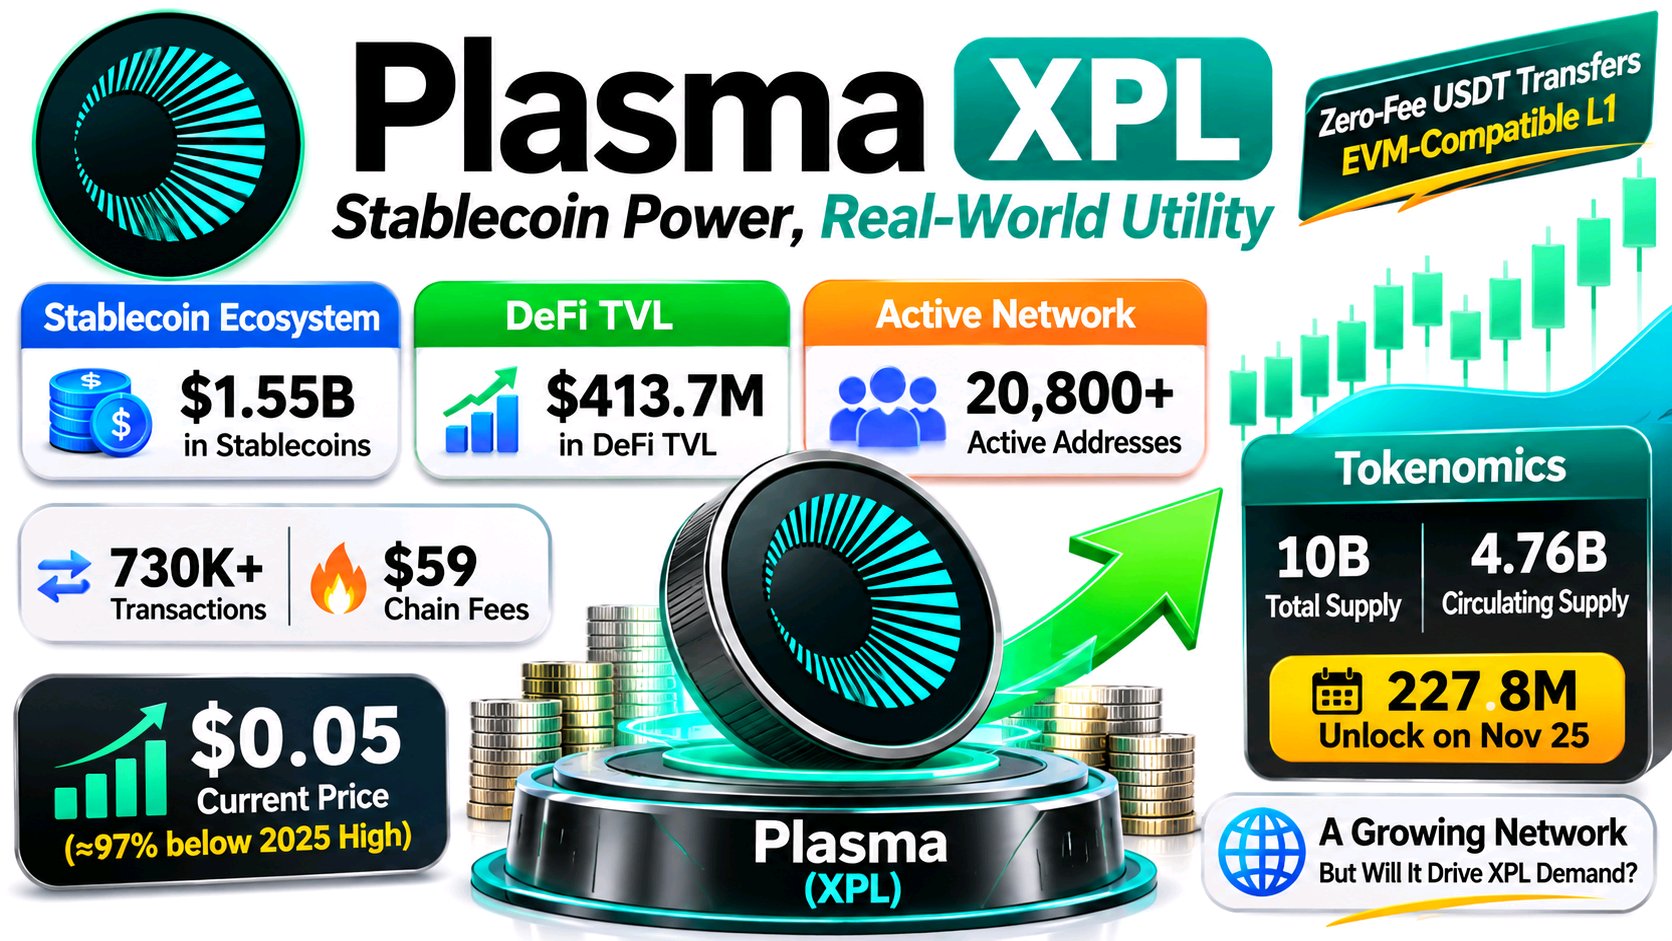
Plasma 最吸引我注意的地方在於,儘管其網路運作繁忙,其代幣經濟學卻難以自圓其說。 Plasma 是一條圍繞穩定幣結算構建的 EVM 相容 Layer 1 區塊鏈,提供零手續費的 USDT 轉帳,並設計了旨在降低支付摩擦的 Gas 選項。其採用數據不容小覷:根據 DefiLlama 數據,11 月 13 日該鏈擁有約 15.5 億美元的穩定幣餘額、4.137 億美元的 DeFi TVL,活躍地址約 20,800 個,交易量達 73 萬筆。然而,同一時間的快照顯示鏈上產生的手續費僅約 59 美元,而應用程式卻產生了約 10.9 萬美元的手續費。這種區別至關重要:雖然網路確實有活動,但大部分經濟價值是被應用程式捕獲,而非底層鏈本身。 這就是 XPL 的故事變得複雜之處。該代幣旨在用於支付 Gas、提供 DeFi 流動性與激勵,以及未來的驗證者安全性,而 Plasma 表示基礎交易手續費將會銷毀。然而,零手續費的 USDT 轉帳和替代性 Gas 選項削弱了「更多的支付量必然會創造即時 XPL 需求」這一假設。 供應量則是另一個壓力點。在 100 億枚的創世分配中,目前流通量約為 47.6 億枚 XPL,另有約 2.278 億枚預計於 11 月 25 日解鎖。同時,XPL 的交易價格在 0.05 美元附近,較 2025 年高點下跌約 97%。 我會持續觀察穩定幣餘額是否能轉化為持續的應用程式使用率、實質的 XPL 需求以及更強的手續費捕獲能力,同時密切追蹤現貨買盤與解鎖及期貨持倉的情況。網路增長令人鼓舞;代幣的價值捕獲才是真正的考驗。 #ByXIMPACT $XPLUSDT
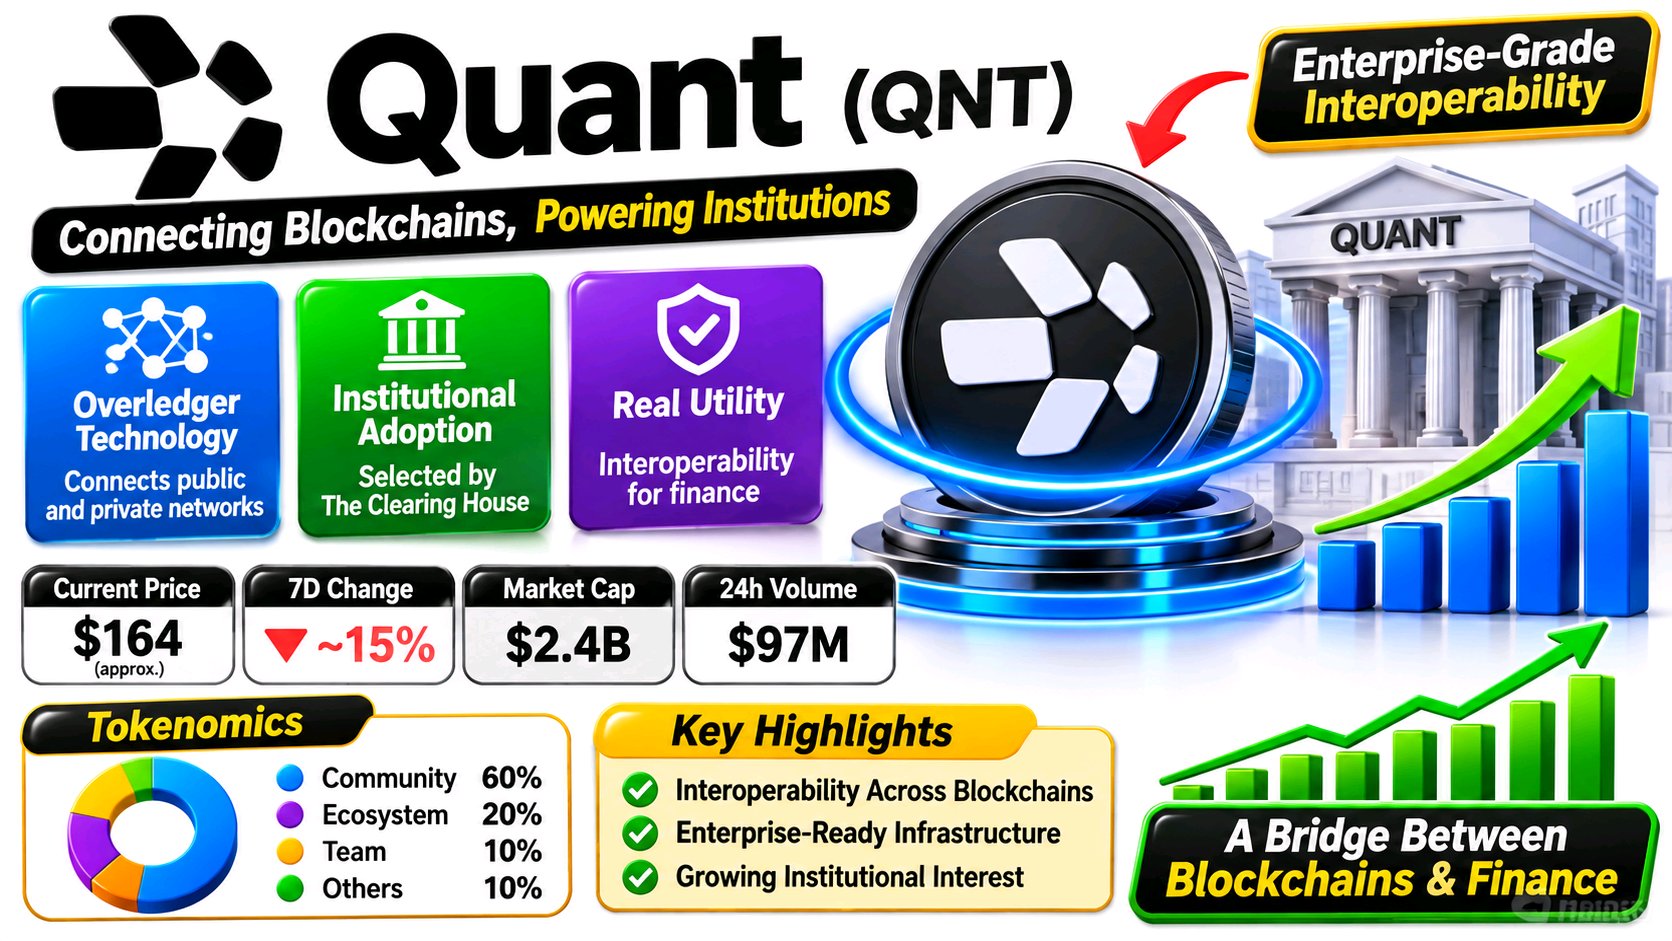
QNT 特別令人感興趣的地方在於,Quant 在機構金融基礎設施中日益增長的角色,與市場目前對待其代幣的方式之間存在差距。重要的問題在於,不斷擴大的企業採用率最終能否轉化為對 QNT 的實際需求,而不僅僅是提升公司的聲譽。 Quant 最引起我注意的地方在於,其機構影響力正變得更加具體,而 QNT 的市場結構卻難以反映出這種進展。 Overledger 並非另一個獨立鏈。它的架構通過 API、連接器和編排層連接公共和許可帳本,讓應用程式能夠跨網路協調活動。9 月 24 日 The Clearing House 的選擇對這一主張進行了嚴峻的考驗:Quant 將為一個與 RTP 和 CHIPS 支付軌道掛鉤的美國代幣化存款網路提供互通性和交易編排。該網路預計將於 2027 年上半年向機構開放,因此這只是一個選擇,而非大規模實時使用的證明。The Clearing House +1 代幣的關聯性值得審視。Quant 的常見問題解答稱,客戶可以用美元或 QNT 支付 Overledger 訂閱費用。QNT 在存取和許可方面確實發揮作用,但企業採用並不自動產生公開市場的買入壓力。這種區別很重要。常見問題解答 +1 市場數據增加了背景資訊。根據 CoinGecko 的數據,11 月 14 日 QNT 的價格約為 164 美元,七天內下跌了約 15%,永續合約未平倉量接近 7300 萬美元,衍生品交易量遠超現貨交易量。這表明槓桿部位仍然很重要;但它並未顯示機構是否正在積累籌碼。CoinGecko 我會密切關注 2027 年的網路推出、Overledger 的經常性使用情況,以及以 QNT 計價的支付是否會增加。對於交易者來說,由更強勁的現貨交易量支撐的復甦,比另一個合作夥伴關係的頭條新聞更重要。真正的考驗在於機構整合是否會成為可衡量的代幣需求。 #ByXIMPACT $QNTUSDT
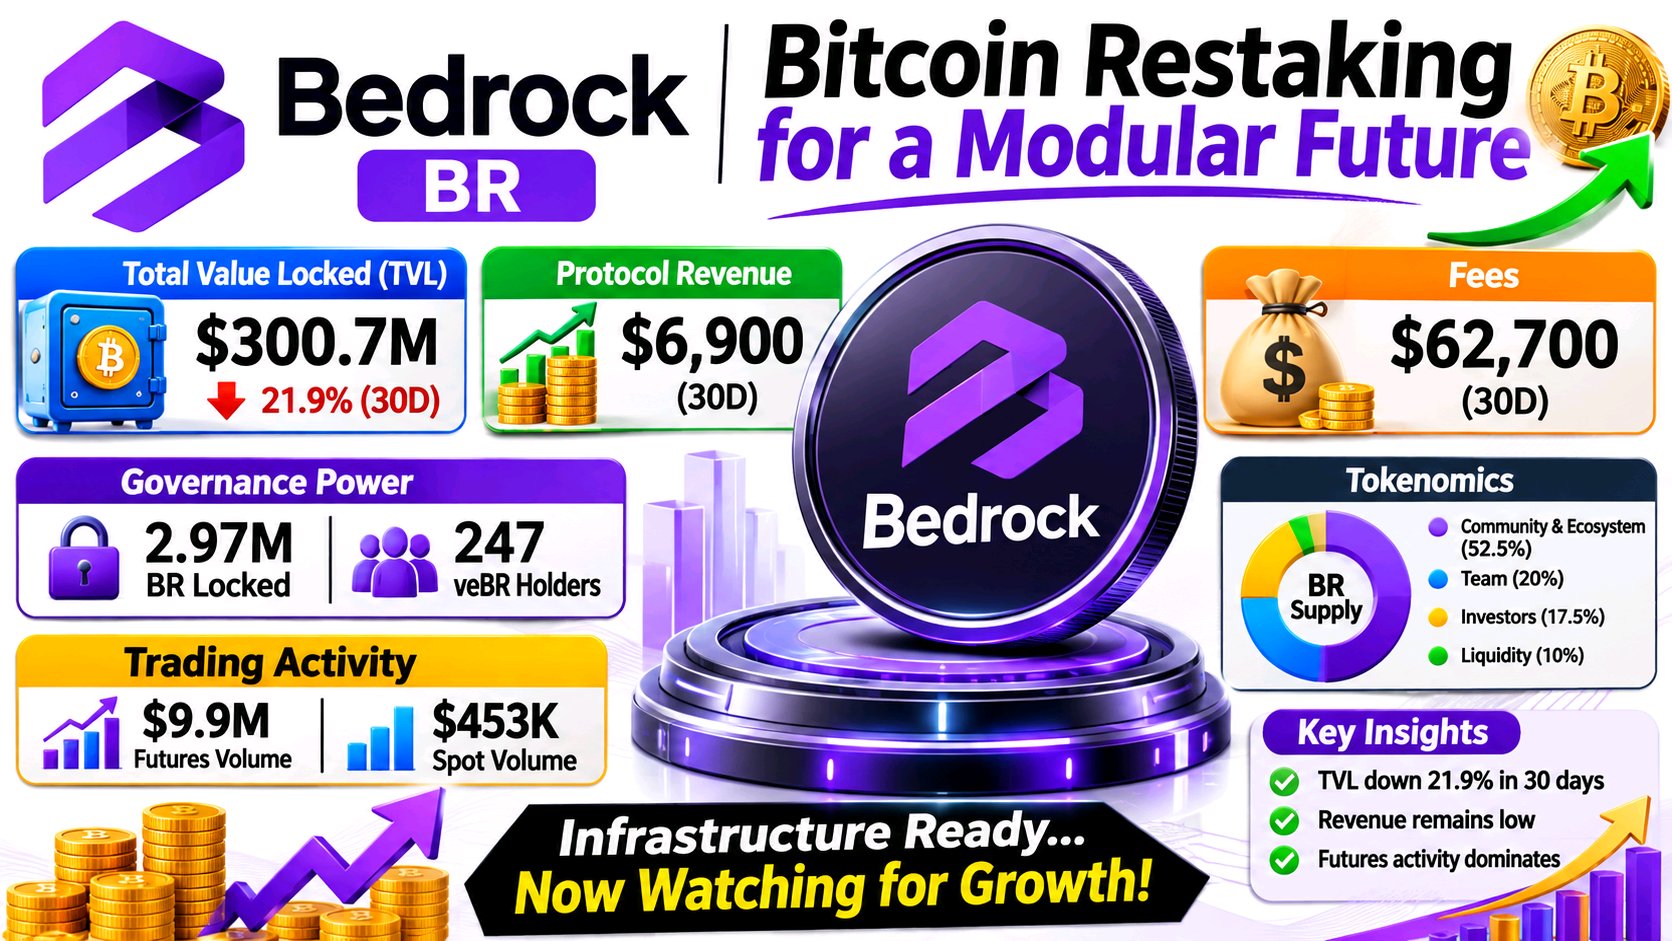
引起我注意的是 Bedrock 的再質押產品規模與目前轉化為可衡量營收的活動之間的落差。 Bedrock 不僅僅是一個 BR 治理代幣。其生態系統涵蓋了 uniBTC、uniETH 和 brBTC 等流動性再質押產品,將資產連接到外部質押和再質押網絡。DefiLlama 顯示,截至 11 月 12 日,Bedrock 的總 TVL(總鎖倉量)接近 3.007 億美元,但報告稱過去 30 天內下降了約 21.9%。這是一個顯著的收縮,雖然不能證明用戶已經放棄了該協議,但這確實讓預期增長變得更加困難。 營收狀況同樣值得關注。DefiLlama 估計其 30 天內的手續費收入約為 62,700 美元,但協議營收僅約 6,900 美元。這種區別很重要:產品上的活動並不自動轉化為協議或其代幣持有者所捕獲的價值。 BR 的作用主要在於治理和激勵,持有者可以將其鎖定為 veBR 以獲得投票權。DAO 儀表板顯示大約有 297 萬枚 BR 被鎖定,擁有 247 名 veBR 持有者。與此同時,CoinGlass 報告稱其期貨交易量約為 990 萬美元,而現貨交易量僅為 45.3 萬美元,未平倉合約接近 2,070 萬美元。這表明衍生品目前推動的交易活動遠多於現貨需求。 我會觀察 TVL 是否趨於穩定、治理參與度是否擴大,以及現貨交易量是否開始確認期貨主導的走勢。Bedrock 已經具備基礎設施;下一個考驗是使用量、營收和代幣需求是否開始同步增長。 #ByXIMPACT $BRUSDT
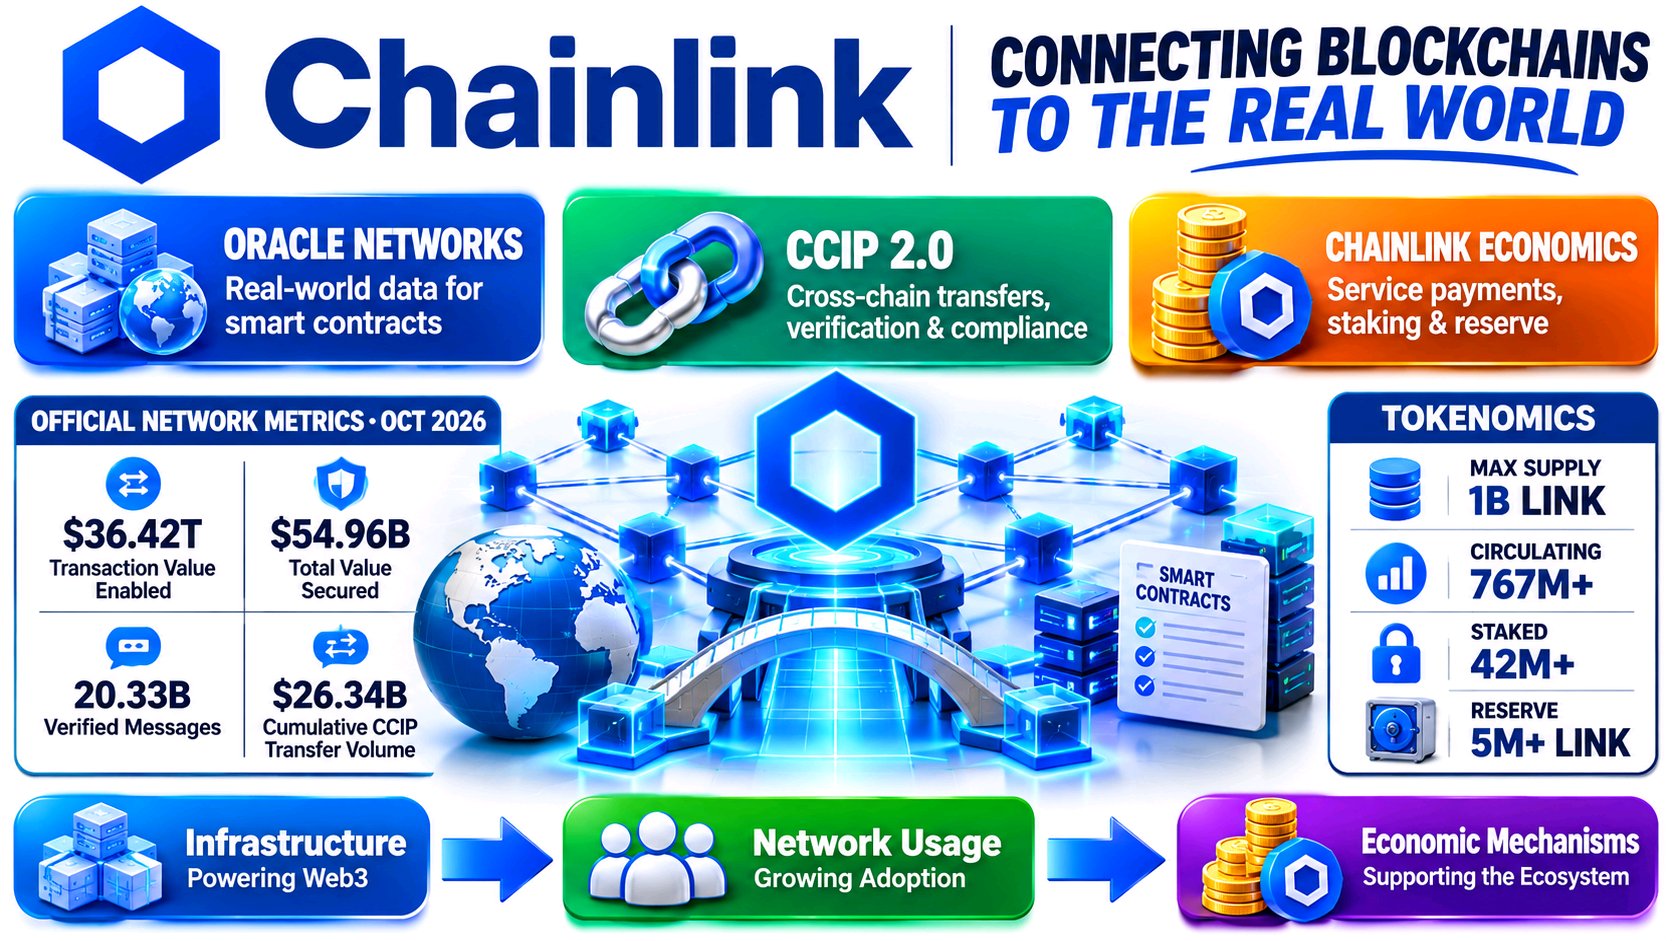
引起我關注 Chainlink 的點在於,其基礎設施的採用與市場目前對 LINK 的態度之間存在著越來越大的差異。這段差距比又發佈了一項合作公告更值得關注。 Chainlink 早已不僅僅是提供價格預言機。其生態系統將智能合約與外部數據、跨鏈基礎設施、儲備金證明(Proof of Reserve)以及機構金融系統連結起來。CCIP 尤為重要,因為它解決了資產和訊息如何在原本互不連通的網絡之間流動的問題。 這些發展正變得更加具體。Chainlink 在 2026 年 9 月宣佈了 CCIP 2.0,同時致力於將金融機構連結到 Swift 的區塊鏈帳本。Coinbase 也在 8 月選擇了 Chainlink 作為其代幣化股票的基礎設施。這些發展表明,互操作性正成為一項實際需求,而不僅僅是一個技術敘事。Chainlink 此外,還有一個值得觀察的經濟連結。LINK 用於支付網絡服務費用、支持安全性,並激勵可靠的性能。根據 Chainlink 的官方經濟儀表板報告,目前流通中的 LINK 約為 7.67 億枚,最大供應量為 10 億枚,同時有超過 4200 萬枚 LINK 處於質押狀態。Chainlink +1 但採用並不自動轉化為立即的代幣需求。11 月 13 日,LINK 的交易價格約為 9.68 美元,24 小時內下跌了約 4%。衍生品數據也顯示未平倉合約正在減少,這表明市場出現了一些減倉行為,而非單純的積累。COINOTAG +1 我會觀察現貨買盤是否回歸、由營收支持的 LINK 積累是否增強,以及價格能否在更健康的成交量下復甦。在此之前,採用率與市場確認仍然是兩回事。 #ByXIMPACT $LINKUSDT
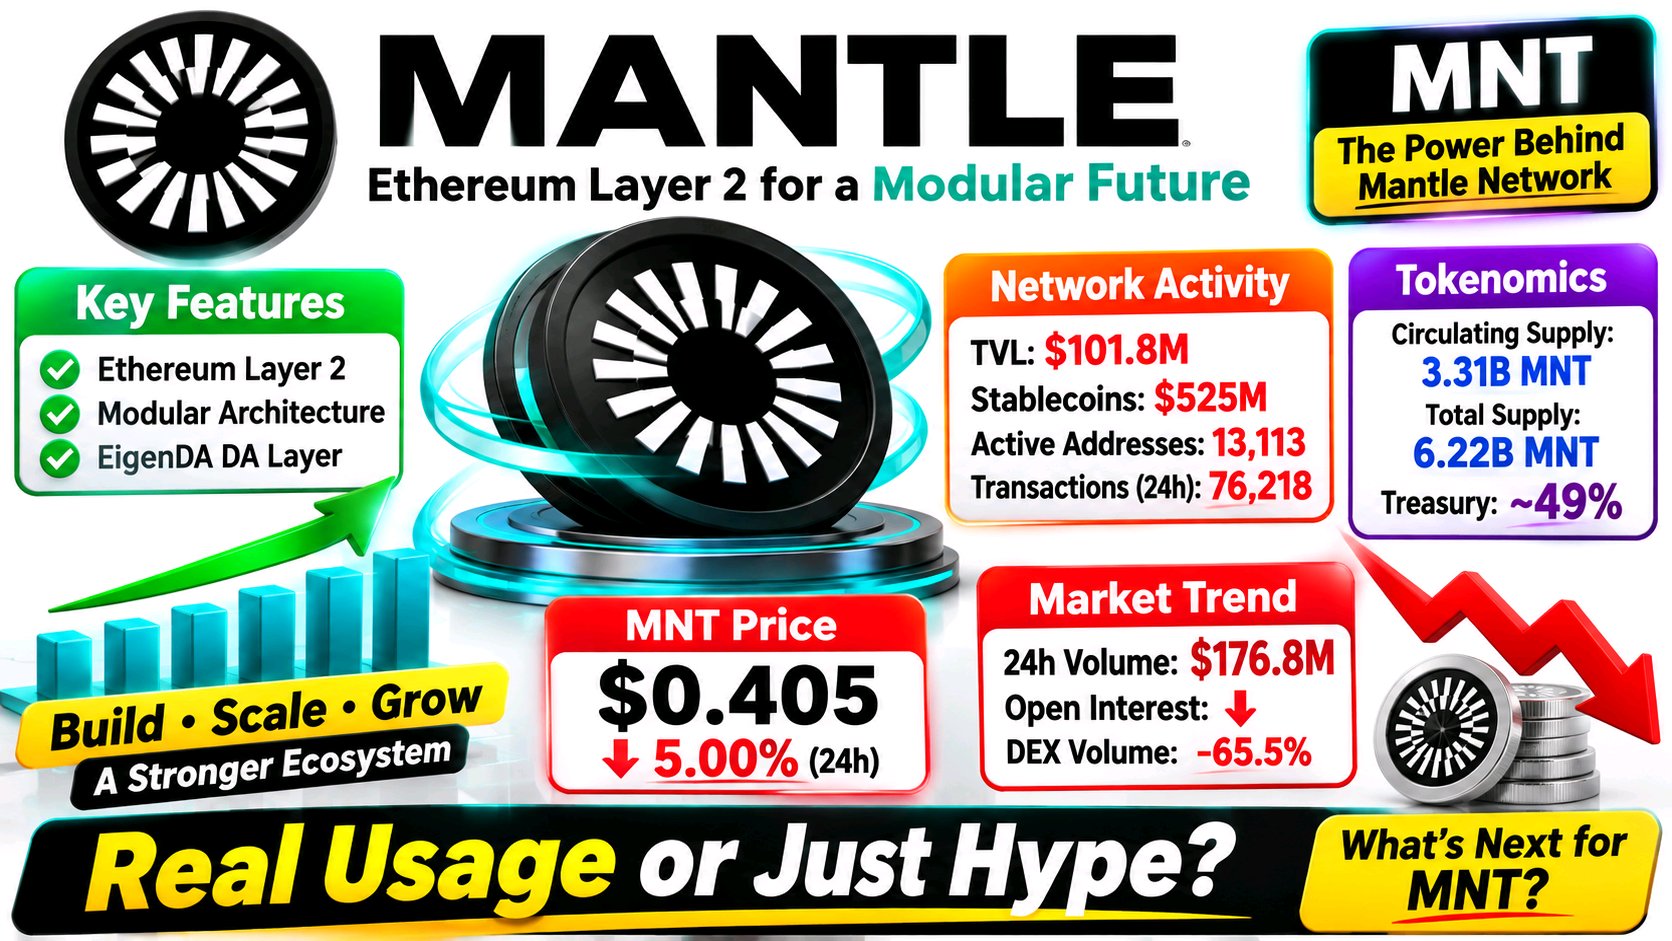
Mantle 最吸引我注意的地方,在於其可見的鏈上活動與金庫仍控制的 MNT 數量之間存在差距。 Mantle 是一個具備模組化設計與 EigenDA 資料可用性的以太坊 Layer 2。MNT 用於支付網路費用,並賦予持有者對生態系統與金庫決策的治理權。但代幣效用並不自動等於代幣需求。GitHub +1 根據 DeFiLlama 11 月 13 日的快照顯示,DeFi TVL 約為 1.018 億美元,穩定幣約為 5.25 億美元,24 小時內活躍地址數為 13,113 個,交易筆數為 76,218 筆。這是可衡量的使用量,儘管單日數據無法證明長期趨勢。同一份快照顯示淨流出約 3,045 萬美元,而每週 DEX 交易量下降了約 65.5%。DefiLlama +1 供應量則是另一個層面。約 33.1 億枚 MNT 在流通,總供應量接近 62.2 億枚。目前沒有列出確切的解鎖期限,但約 49% 的代幣仍保留在 Mantle 金庫中,未來的分配取決於治理決策。這雖然不是迫在眉睫的解鎖,但仍是一個重大的供應分配問題。DefiLlama +1 11 月 13 日 MNT 價格約為 0.405 美元,24 小時內下跌約 5%,期貨未平倉合約也在下降。這更傾向於部位正在減少,而非新的槓桿正在建立。CoinGlass +1 我會觀察穩定幣流動性與鏈上活動是否恢復,金庫提案是否改變了預期的供應量,以及現貨需求是否改善,再來決定是否將價格反彈視為確認信號。更大的問題在於,真正的網路使用量能否轉化為對 MNT 的持久需求。 #ByXIMPACT $MNTUSDT
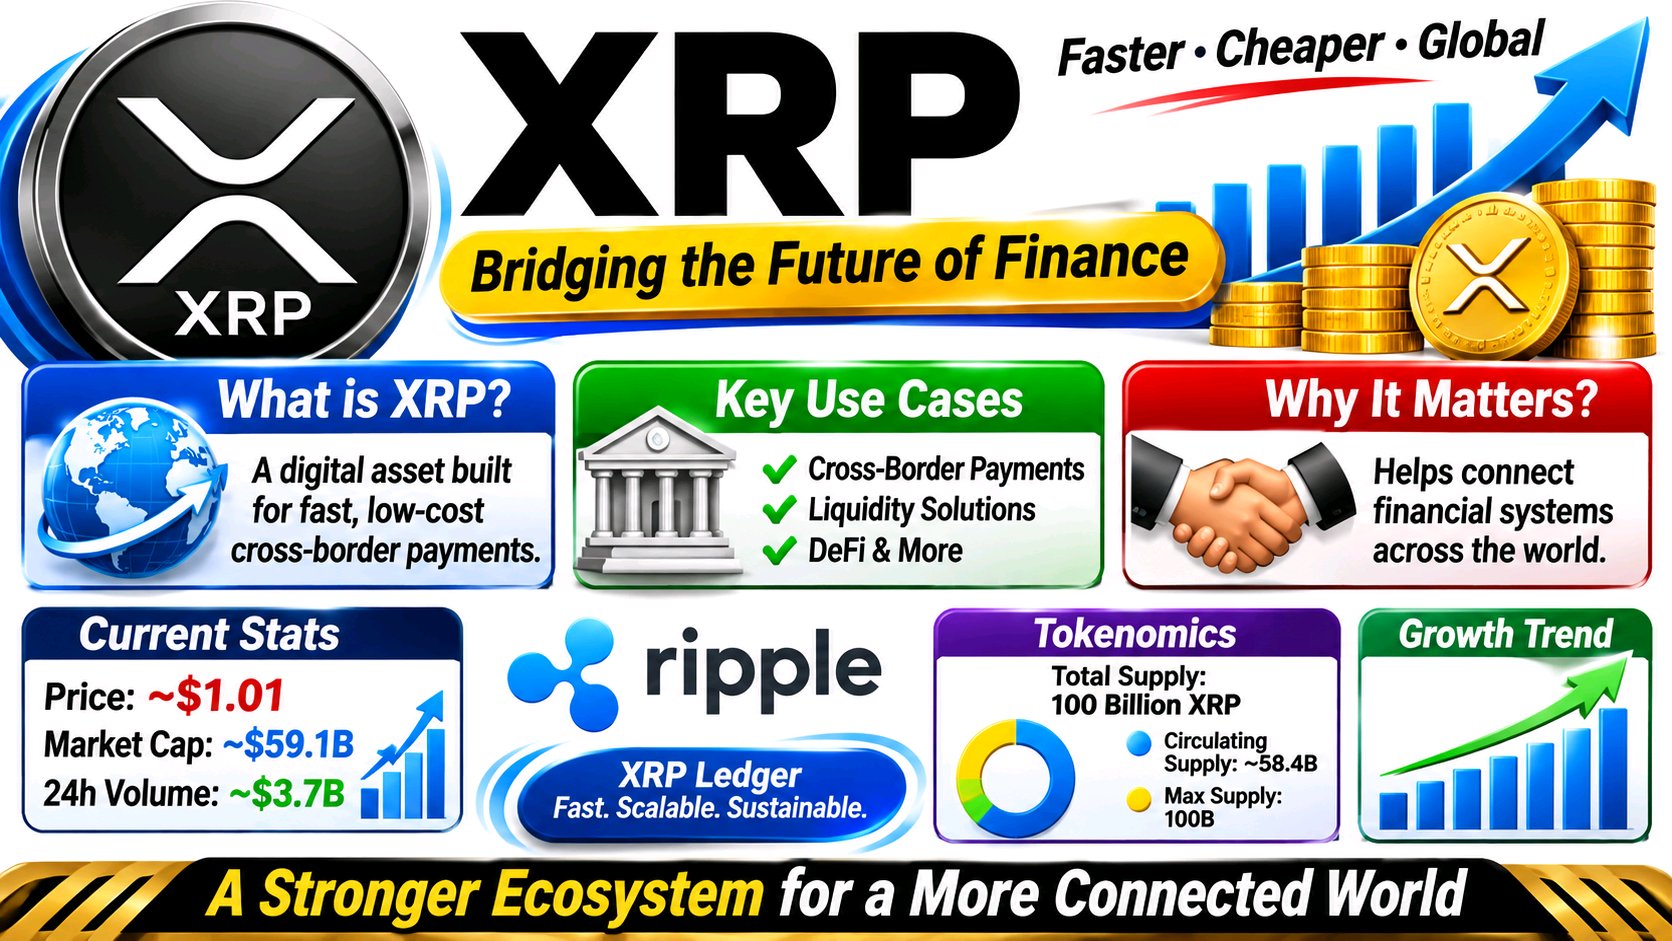
XRP 目前市場結構中最顯眼的部分,在於其機構投資敘事與交易員實際行為之間的落差。長期生態系統發展與短期市場需求之間的區別,正變得尤為重要。 引起我注意的是 XRP 在 Ripple 推動機構穩定幣與 XRP 自身需求之間的差距。 Ripple 於 10 月 28 日在 Coinbase 推出的服務,使 RLUSD 可在 Coinbase 的散戶、交易所及 Prime 平台上使用,而渣打銀行也已為 XRPL 上的 RLUSD 推出了機構託管服務。這些都是在分發與託管方面具有意義的舉措。但 RLUSD 是一種美元穩定幣;其採用並不自動要求機構持有 XRP。Ripple +1 這種區別反映在網路數據上。根據 DefiLlama 的數據,截至 11 月 13 日,XRPL 上的穩定幣價值接近 9 億 800 萬美元,其中 RLUSD 約佔 90%。然而,DeFi 的總鎖倉量(TVL)約為 3,200 萬美元,24 小時 DEX 交易量約為 576 萬美元。帳本雖然活躍,但穩定幣的規模並未轉化為同樣深度的鏈上交易或 DeFi 流動性。穩定幣價值在七天內也下跌了約 8%,因此單一時間點的快照並非直線採用的趨勢。DefiLlama +1 XRP 仍然扮演著實際角色:它是帳本的原生資產,用於支付交易成本,並且可以橋接貨幣;Ripple 的隨需流動性(ODL)也使用它作為橋接資產。問題在於有多少機構活動實際上是透過 XRP 進行路由的。xrpl.org +1 與此同時,XRP 交易價格在 1.01 美元附近,七天內下跌約 14%。期貨交易量約為現貨交易量的四倍,且以多頭清算佔主導地位。我會觀察穩定幣餘額是否趨於穩定、DEX 流動性是否擴大,以及現貨需求相對於槓桿是否有所改善。這種聯繫比又出現一則合作頭條新聞更為重要。 #ByXIMPACT $XRPUSDT
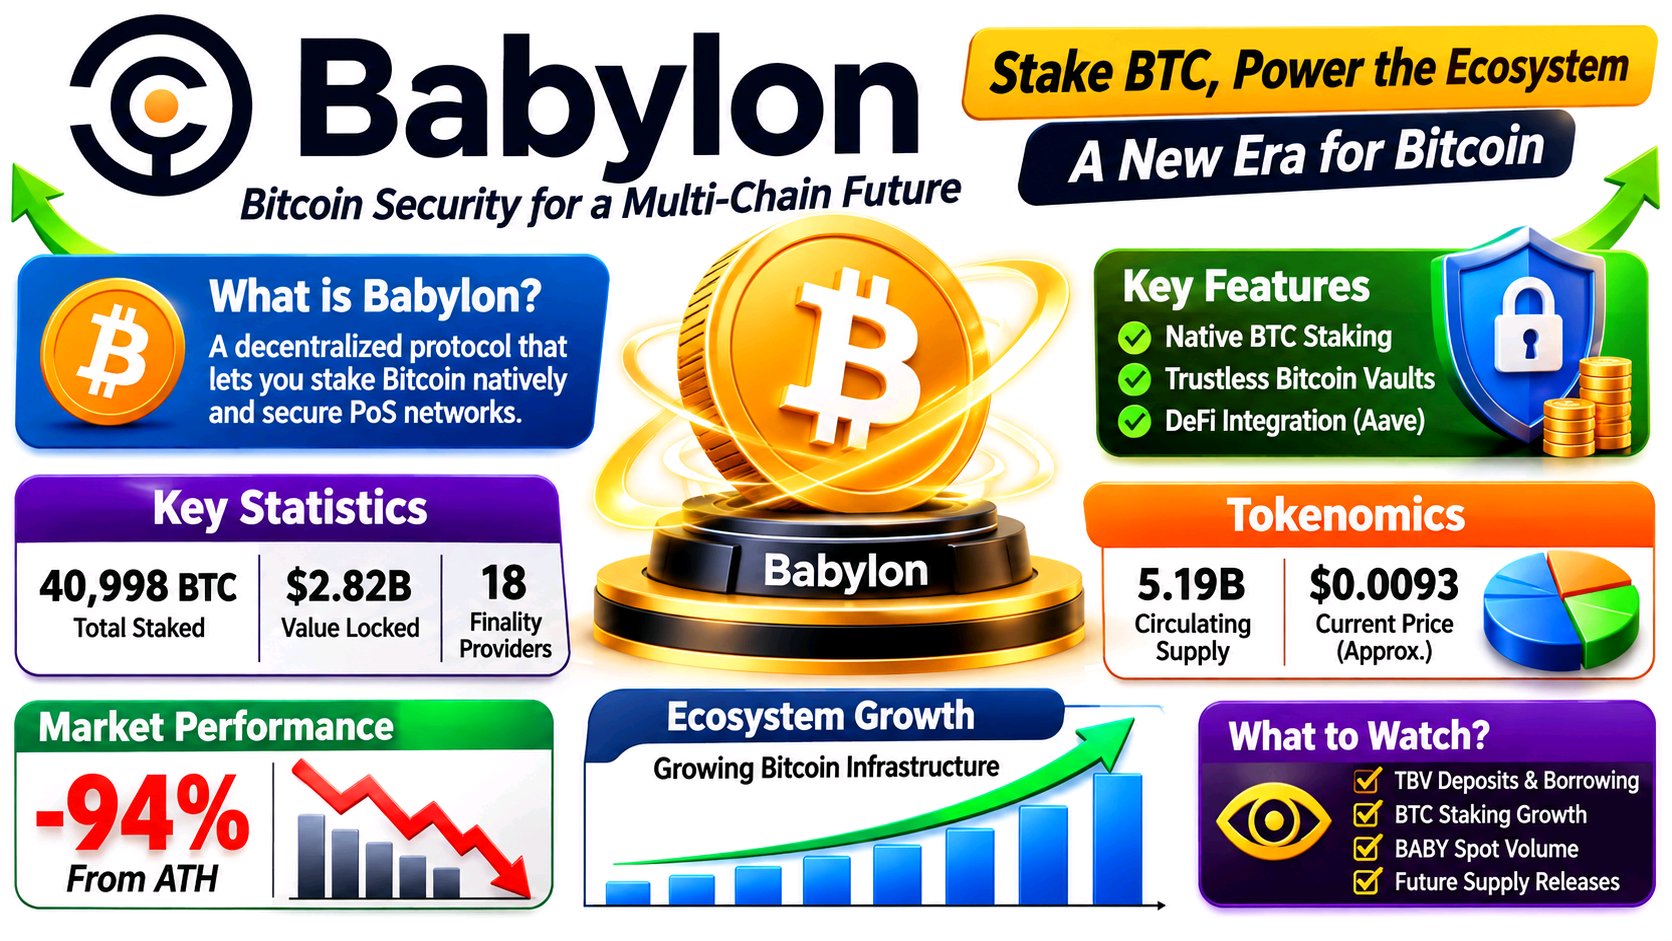
在 Babylon 中,最引起我關注的是其比特幣基礎設施與市場對 BABY 的定價之間的落差。 該協議的價值主張十分具體:BTC 在比特幣網路上進行原生質押,無需封裝或放棄託管權,而 Babylon Genesis 則為連接的網路協調安全性。其即時儀表板顯示約有 40,998 BTC 進行質押,價值約 28.2 億美元,並有 18 個活躍的終局性提供者(finality providers)。這是有實質投入的資本,而不僅僅是一個錢包數量的噱頭。 [1] Babylon 也正在超越單純的質押。其「去信任化比特幣金庫」(Trustless Bitcoin Vaults, TBV)旨在讓原生 BTC 能夠作為外部應用程式借貸的擔保品。Aave 的治理程序已推進了一項整合提案,Babylon 的文件也將 Aave v4 列為第一個 TBV 應用。但這只是一條基礎設施路徑,並不能證明大規模的借貸需求或手續費收入已經到來。 [2] BABY 的角色不如 BTC 那樣直接。它用於支付 Genesis 費用、支持治理與質押,並參與共同質押激勵。然而,BABY 的交易價格接近 0.0093 美元,較其報告的歷史高點下跌約 94%,流通量約為 51.9 億枚代幣。衍生性商品數據顯示,未平倉合約約為 590 萬美元,而每日現貨交易量不到 100 萬美元。因此,槓桿交易的規模超過了可見的現貨活動。 [3] 我會持續觀察實際的 TBV 存款與借貸情況、BTC 質押的持續性、BABY 現貨交易量的復甦,以及未來的代幣供應釋放。核心問題在於 Babylon 能否將比特幣的實用性轉化為能夠觸及 BABY 的持續性經濟活動,而不僅僅是擴大其周邊的基礎設施。 #ByXIMPACT $BABY1USDT
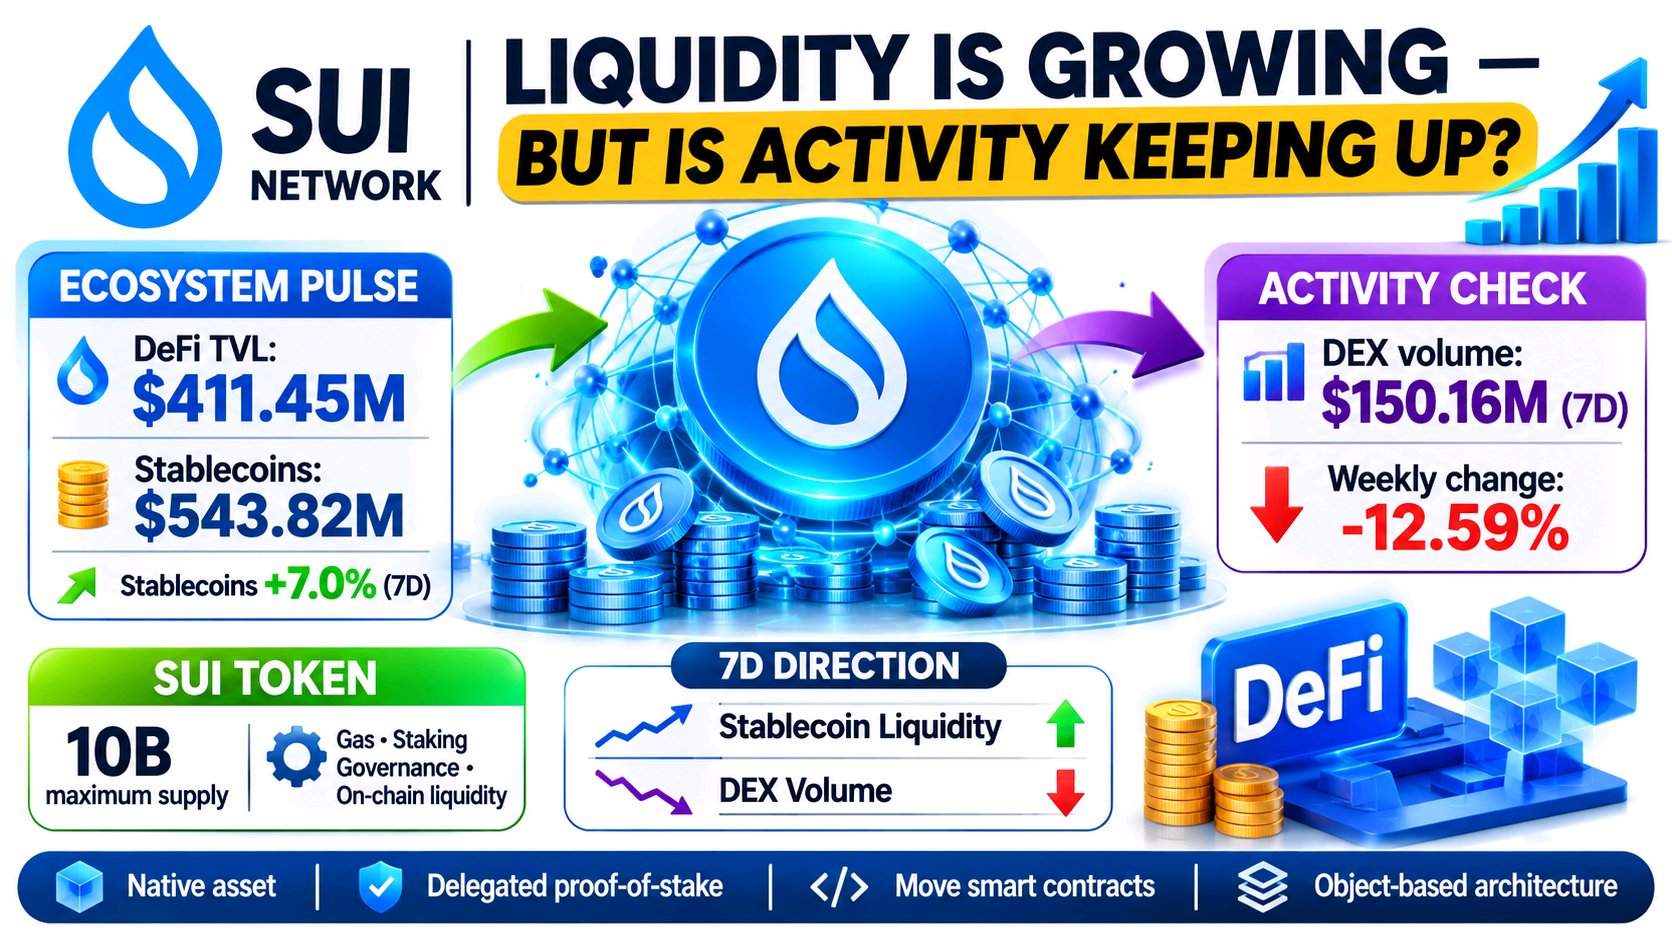
目前SUI最吸引我注意的,是穩定幣增長與實際DeFi活動之間的脫節。流動性似乎正在進入生態系統,但这並不代表用戶正在將其投入使用。 截至11月12日,DeFiLlama報告顯示Sui的DeFi TVL約為4.1145億美元,而穩定幣供應量已達到5.4382億美元,七天內增長了約7%。然而,每週DEX交易量卻下降了12.59%,至約1.5億美元。這種組合比任何單一頭條新聞都更值得關注。DefiLlama +1 我認為區分「可用流動性」與「生產性流動性」也很重要。Sui基於物件的架構、Move智能合約以及Mysticeti共識機制專為高效執行而設計,而SUI代幣本身則用於支付交易費用並透過委託質押來保障網絡安全。Sui Documentation +2 市場尚未對該生態系統給予回報。11月13日,SUI的交易價格接近0.80美元,七天內下跌了約7.6%。CoinGlass的數據也顯示,期貨交易量約為現貨交易量的6.2倍,未平倉合約接近4.81億美元。這表明衍生品在交易活動中扮演的角色遠大於現貨需求。CoinGlass +1 對我而言,下一個確認訊號應該來自DEX交易量伴隨穩定幣增長而上升,以及TVL的改善與更強勁的現貨參與度。我也會觀察未平倉合約是否能在沒有過度多頭持倉的情況下趨於穩定。 Sui具備基礎設施和流動性,但真正的問題在於這些流動性是否開始產生持續的經濟活動。這是我在得出更強結論前想要看到的差異。 #ByXIMPACT $SUIUSDT
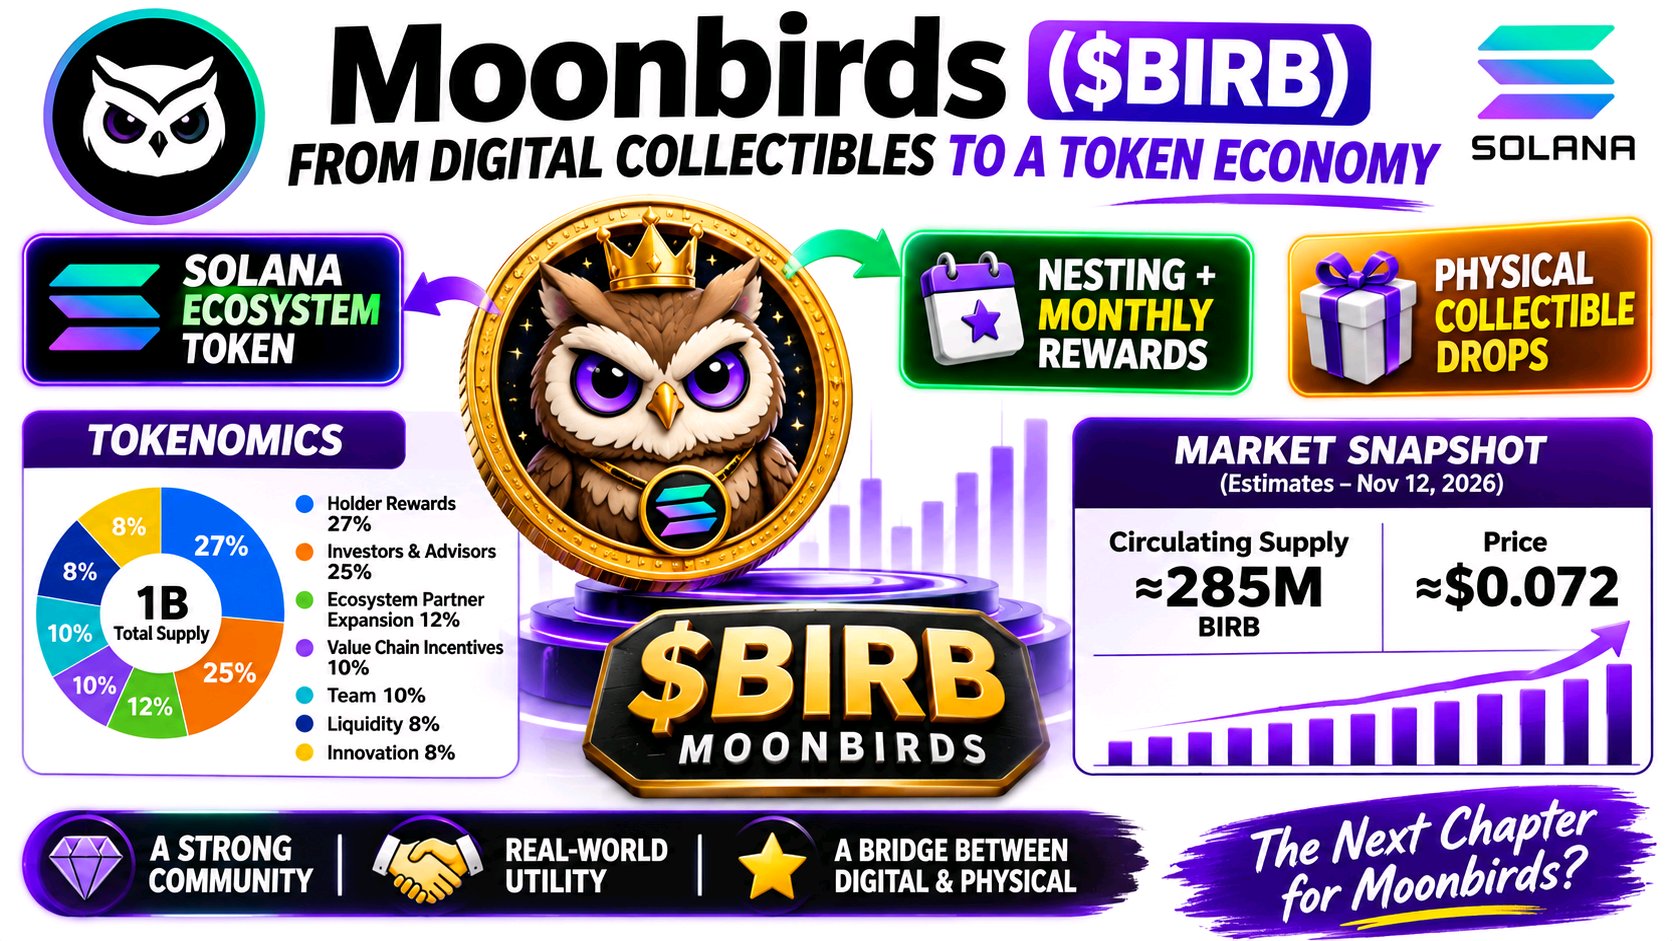
Moonbirds ($BIRB) 引起我注意的地方,在於它嘗試將一個既有的 NFT 身份轉變為更廣泛的代幣化生態系統。這種轉變固然有趣,但真正的考驗在於社群參與能否轉化為永續的經濟活動。 BIRB 運行於 Solana 鏈上,旨在支援生態系統激勵、社群獎勵、治理參與以及未來的整合。該項目已不再僅僅是關於擁有一款數位貓頭鷹收藏品;它正試圖將其智慧財產權與更廣泛的消費者導向經濟連結起來。 代幣經濟學揭示了一個重要細節。其最大供應量為 10 億枚 BIRB,其中 27% 分配給持有者獎勵,25% 分配給投資者和顧問,10% 分配給團隊,12% 分配給生態系統合作夥伴。根據官方時程表,團隊與投資者的份額有 12 個月的鎖定期,隨後開始每月歸屬(vesting)。這使得流通供應量與未來的分配情況成為需要密切關注的重要因素。moonbirds.com +1 更令人感興趣的發展是 Nesting(築巢)機制的演變。Moonbirds 現在引導持有者至其「收藏家個人檔案」(Collector Profile),在那裡可以持續獲得每月 BIRB 分配,且「築巢」的 NFT 還能賺取可用於兌換未來實體收藏品空投的「蛋」(eggs)。這將數位所有權與實體產品連結起來,而非僅僅依賴代幣投機。claim.moonbirds.com +1 然而,市場依然保持謹慎。11 月 12 日,BIRB 的交易價格約為 0.073 美元,現貨交易量約為 460 萬美元,對比期貨交易量則為 1720 萬美元。未平倉合約(Open interest)接近 860 萬美元,而其週跌幅逼近 18%。這顯示衍生品活動值得關注,但並不代表存在真正的生態系統需求。CoinGlass 我關注的重點將是實體收藏品活動、重複參與度和實際代幣使用量是否能同步成長。我也會持續觀察每月分配、流通供應量、現貨流動性,以及期貨部位是否開始能支撐而非主導價格走勢。Moonbirds 在數位文化與實體商業之間架起了一座有趣的橋樑,但這座橋樑能否為 BIRB 創造持久的需求呢? #ByXIMPACT $BIRBUSDT